







Your Simple Guide to Unpaid Invoice Mistakes and Better Records
Business bad debts can sometimes produce a federal tax deduction, but an unpaid invoice is not automatically deductible. The first question is whether the uncollected amount was already included in taxable income. A cash-method service business generally cannot deduct a fee it never received or reported as income. An accrual-method business may have a different result, subject to the other requirements.
The IRS bad-debt overview explains this starting point and the need to establish worthlessness. An old invoice, a disappointed owner and a bookkeeping write-off do not, by themselves, answer the tax question. You need to connect the debt, the income history, collection evidence and the relevant year.
This guide focuses on ordinary unpaid customer service invoices in US businesses. It explains five practical checks, a worked example and a review file you can discuss with your tax preparer. Loans, guarantees, purchased receivables, inventory transactions and personal debts can require different analysis.
Table of contents
- What business bad debts mean
- Why your tax accounting method matters
- Five checks before claiming a deduction
- A worked unpaid-invoice example
- Build a useful evidence file
- Keep the cash-flow decision separate
- Common mistakes to avoid
- Frequently asked questions
- Conclusion
What business bad debts mean
A business bad debt generally arises from a debt created or acquired in a trade or business, or closely related to it when the debt becomes partly or completely worthless. The business connection and the existence of a genuine debt both matter. An invoice entry is evidence to investigate, not a substitute for those facts.
For ordinary customer receivables, business bad debts concern amounts the customer owes for an actual transaction. Keep the contract, invoice, delivery or service evidence and the payment terms together. If the customer disputes whether the work was accepted or the amount is correct, resolve that issue before treating the whole balance as an uncollectible debt.
There is a difference between correcting an invoice and recognizing a bad debt. A duplicate invoice should be corrected as an error. A legitimate agreed price adjustment needs its own documentation. Neither should be disguised as a collection loss simply to clear a report.
The distinction also protects your customer relationships. A reminder based on an incorrect balance wastes time and can create avoidable disputes. Before reviewing business bad debts, make sure payments, credits and adjustments have been applied to the right customer account.
Our accounts receivable aging guide explains how to organize overdue balances for follow-up. Aging helps you identify which invoices deserve attention. It does not establish a deduction or prove that a particular debt has become worthless.
Why your tax accounting method matters
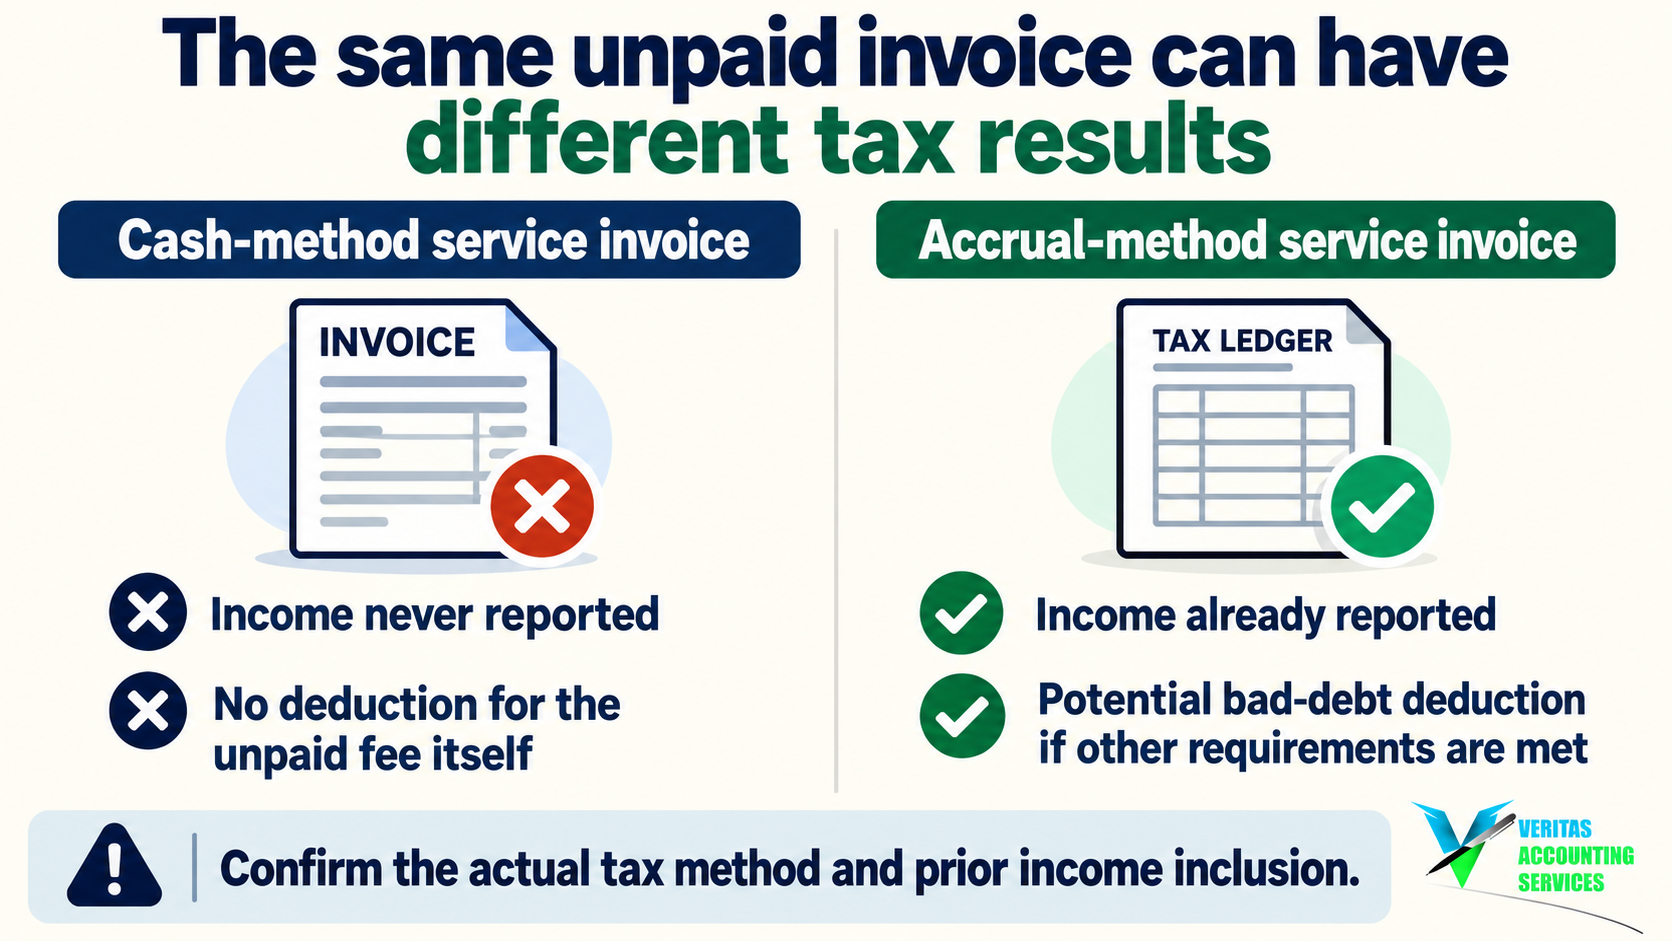
Under the cash method, income is generally reported when received, including amounts constructively received under the applicable rules. Under the accrual method, income is generally reported when earned, subject to the relevant tax rules. Your tax accounting method determines the timing; the setting on a management report is not conclusive.
The IRS accounting-methods publication explains these general differences. Its available edition is dated January 2022, so this article uses it for the basic method distinction, not for current inflation-adjusted eligibility limits. Confirm the actual method used on your return with the preparer.
For business bad debts from a cash-method service invoice, the unpaid fee itself generally has not entered taxable income. You cannot create an additional deduction for that missing fee merely because you spent time doing the work. Any actual business costs need their own normal treatment; do not count them again through the invoice balance.
For business bad debts, an accrual-method service business may already have included the fee in income even though the customer has not paid. If that receivable later becomes uncollectible, a deduction may be available after reviewing the debt, evidence, timing and applicable requirements. Prior inclusion is one condition, not the entire test.
Your financial books and tax return may also use different treatments. Ask for the tax reconciliation instead of assuming a book expense automatically appears as a deduction on the return. This article addresses federal income tax treatment, not a complete financial-reporting standard or an instruction to change accounting methods.
When examining business bad debts, identify the year and amount previously included in income. A statement that “we use accrual” is less useful than a clear connection to the particular receivable. Mixed transactions and changes in method should go to the preparer for specific review.
Five checks before claiming a deduction
1. Confirm the genuine debt and business connection
Identify who owes the money, why it is owed and which business owns the receivable. Match the invoice to the underlying agreement and service records. An amount that was never legitimately due cannot be made deductible by issuing an invoice after the fact.
Business bad debts are different from personal loans that happen to involve a business owner. Family arrangements, advances to related parties, guarantees and amounts that may actually be capital contributions require their own analysis. Do not copy the customer-invoice conclusion to those transactions.
Ask the reviewer to record the scope of the decision. For example, the file might cover a specific unpaid consulting invoice rather than every balance connected with the customer. Clear scope helps prevent another account from being written off without review.
2. Reconcile the amount and prior income inclusion
Start with the original invoice and subtract payments and valid credits. Confirm that a deposit has not been posted to a different account and that a payment has not been overlooked. A current customer statement should agree with the detail being reviewed.
For business bad debts, trace the remaining receivable to its tax history. Ask whether the unpaid portion was included in gross income for the current or an earlier year. Preserve the relevant return workpaper or preparer’s confirmation rather than relying only on a software label.
If the invoice includes several different components, identify them before calculating a potential deduction. This guide’s example assumes a simple service fee without sales tax, interest or other adjustments. Real invoices may require separate treatment of amounts that were never your taxable income.
3. Establish worthlessness from the facts
Being overdue and being worthless are different conditions. The IRS describes worthlessness by reference to the surrounding facts and circumstances and the absence of a reasonable expectation of repayment. The evidence needs to explain why collection is no longer reasonably expected, not merely why the owner is frustrated.
When reviewing business bad debts, retain reasonable collection steps and the outcome. Depending on the case, the record might include reminders, responses, failed payment arrangements and verified information about the debtor’s position. No single generic checklist guarantees a conclusion for every customer.
The IRS says a court action is not necessary if you can show that a judgment would be uncollectible. That is different from a blanket statement that collection efforts are unnecessary. Discuss the facts with the appropriate adviser, including legal issues where relevant, instead of automatically suing every debtor or abandoning every difficult account.
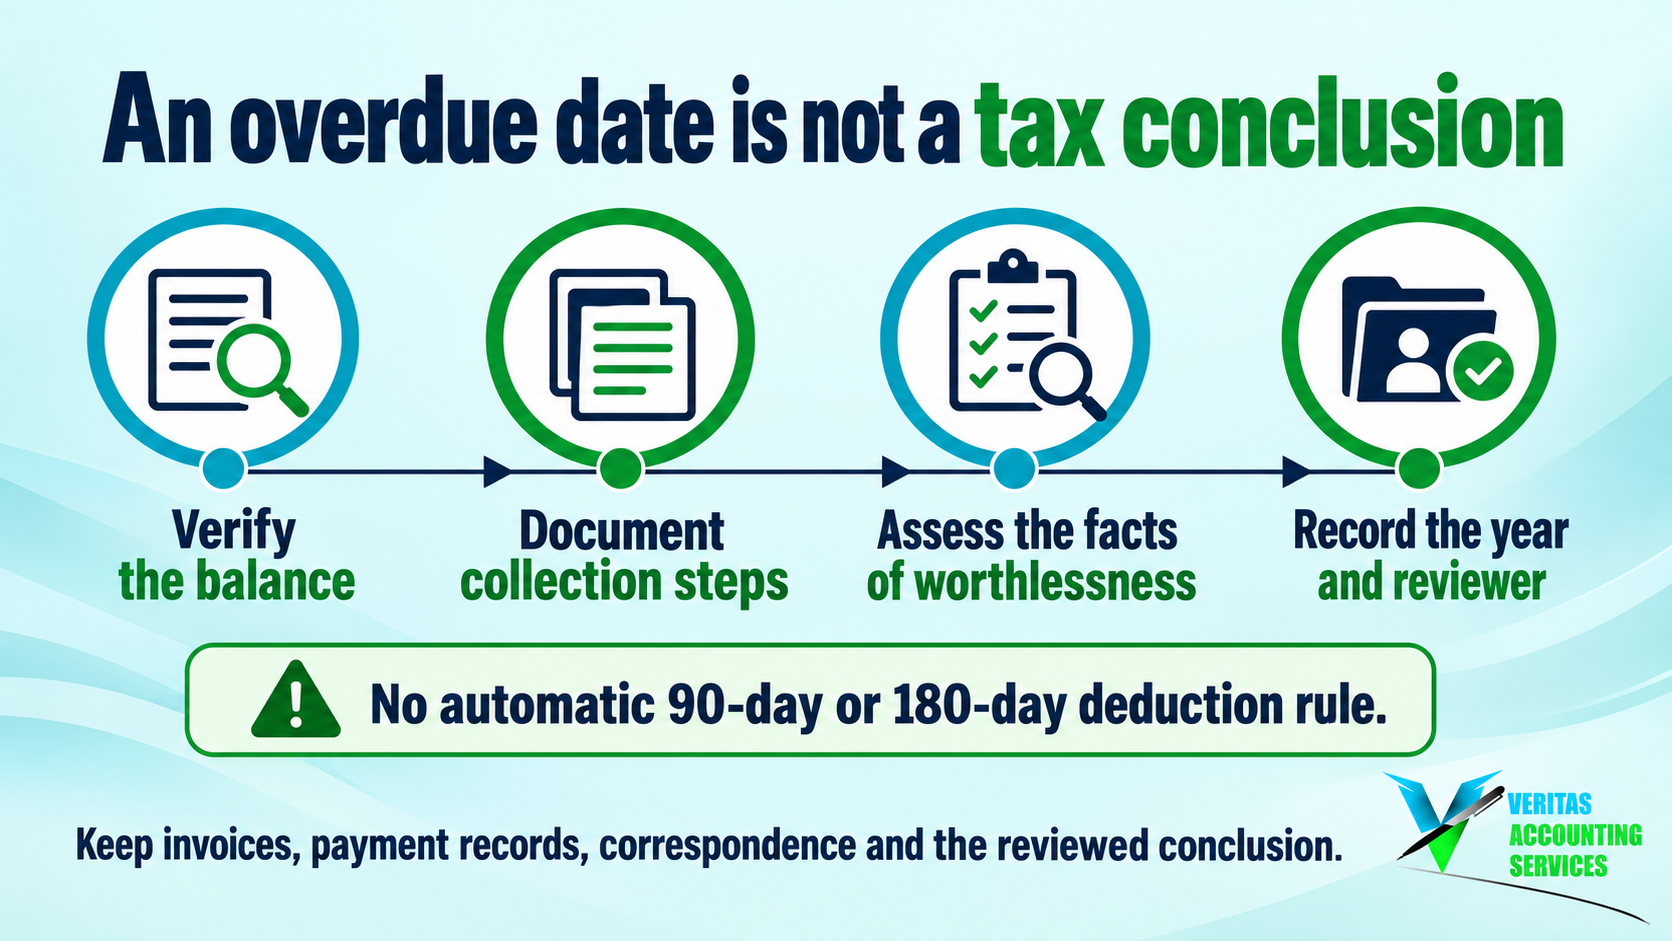
Business bad debts do not become deductible simply because a report moves them into a 90-day or 180-day bucket. Aging is a prompt to investigate. Record the events supporting the conclusion and the date the reviewer assessed them.
4. Review the year and charge-off requirements
The timing of a deduction for business bad debts matters. A totally worthless debt generally belongs in the year it becomes worthless, rather than whichever year produces the largest benefit. If a potential loss relates to an earlier year, ask the preparer about the correct return and applicable claim procedures.
The IRS small-business tax guide explains the general specific charge-off method for business bad debts. Under that method, a deduction for a partly worthless business debt is limited to the amount charged off on the books during the year. A general estimate or reserve is not the same as identifying and reviewing a specific debt.
The guide distinguishes totally worthless debts: an actual book charge-off is not required in the same way, although recording one may be useful and partial-worthlessness findings can affect the result. Do not turn that distinction into permission to leave the books unexplained. Have the preparer coordinate the tax conclusion and the accounting entry.
Business bad debts can involve partial losses, later total losses or prior deductions. Keep a history of amounts previously deducted so the same loss is not claimed twice. Specialized methods and exceptions exist; this guide does not establish eligibility for them.
5. Coordinate the books, return and later receipts
For business bad debts, give the bookkeeper an approved adjustment and keep the reason with it. Give the tax preparer the same supporting schedule and identify any book-to-tax difference. The two teams should not independently calculate different losses from different versions of the customer ledger.
Business bad debts also need a recovery process. If money arrives later, identify the original invoice and any earlier deduction before deciding how to record it. A closed customer account should not cause a real bank receipt to be ignored or posted to an unexplained suspense account.
IRS guidance says recovery of a previously deducted bad debt may need to enter gross income, subject to the tax-benefit rule. The amount previously deducted and whether it reduced tax affect the result. Keep that history available so a later receipt can be reviewed accurately.
A worked unpaid-invoice example
Suppose a US service business sends a genuine $6,000 invoice for completed work. The customer pays $1,500, leaving $4,500 unpaid. Assume there are no credits, sales taxes, financing charges, insurance recoveries or other adjustments. These are hypothetical amounts, not details from a client file.
In the accrual-method version of this example, assume the business previously included the full $6,000 in taxable income. The payment reduces the receivable to $4,500: $6,000 minus $1,500. That remaining amount is the starting point for reviewing business bad debts, not an automatic deduction.
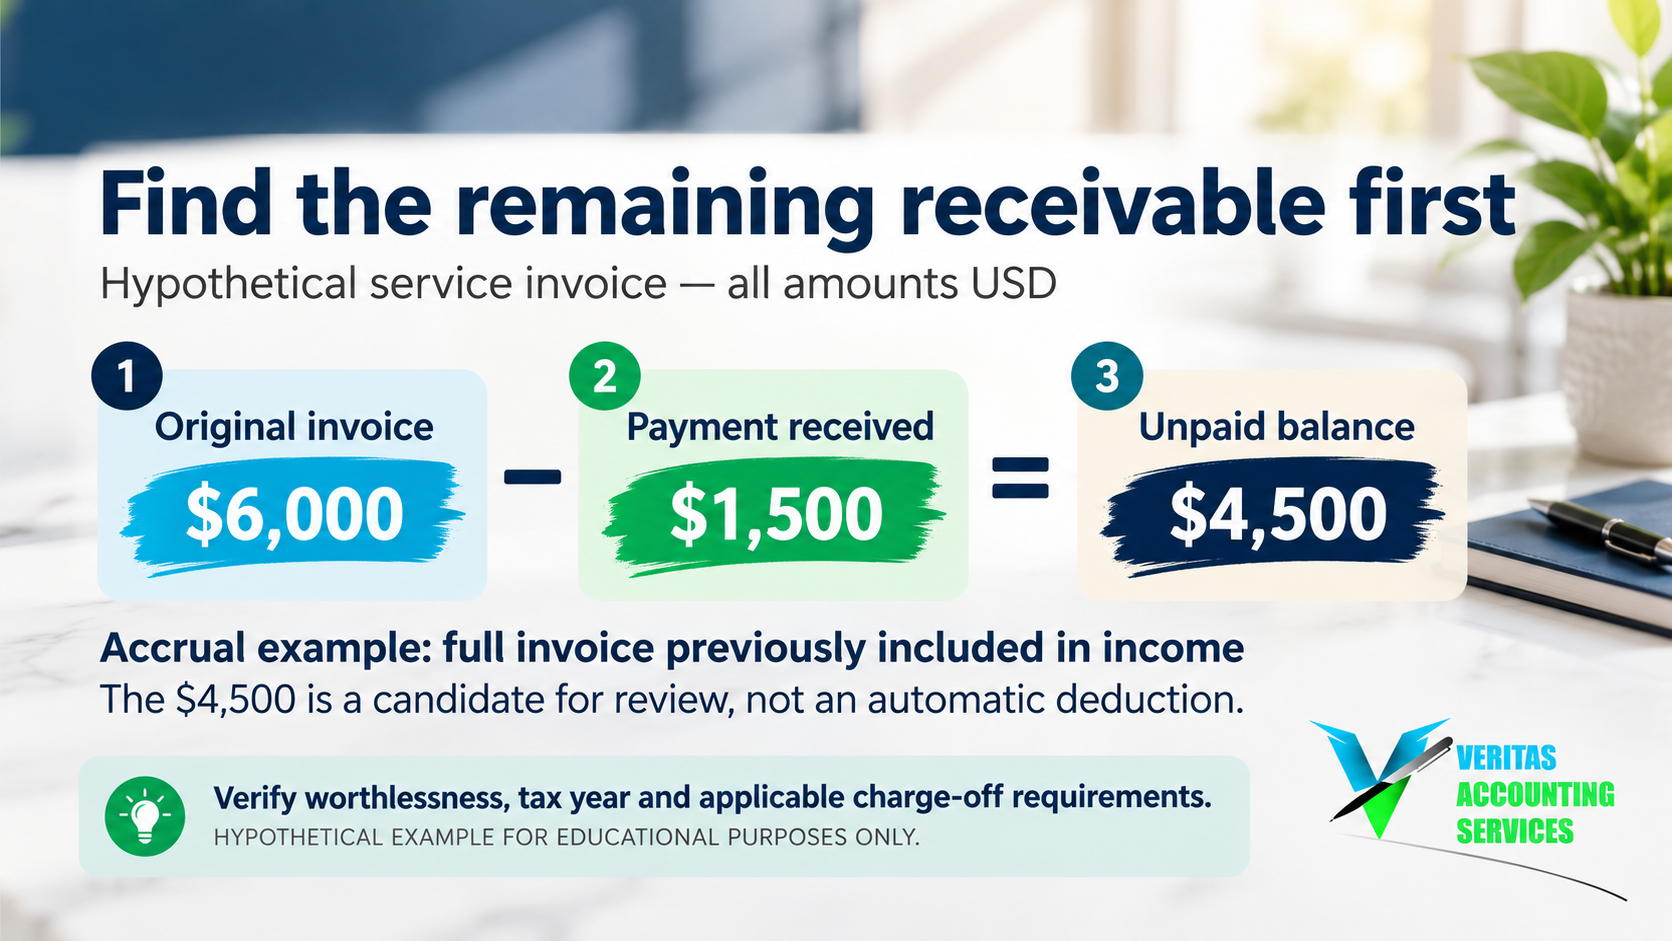
The reviewer of business bad debts must still decide whether the remaining debt became worthless, in whole or in part, in the relevant year and whether the applicable requirements are satisfied. If only part is supportably uncollectible, treating the entire $4,500 as worthless would overstate the conclusion. Prior deductions also need to be considered.
Now change the tax method. Suppose the business instead uses the cash method and has never included the unpaid $4,500 in taxable income. Under that assumption, there is no bad-debt deduction for the missing fee itself. The $1,500 actually received and any separately deductible costs follow their own rules.
The commercial loss feels similar in both versions: the business expected more cash than it collected. The tax starting point differs because the income history differs. Business bad debts cannot be analyzed from the bank shortfall alone.
A deduction also does not put the missing $4,500 into the bank. Any tax effect depends on the complete return and the applicable rules. Do not reduce next month’s collection effort or increase spending on the assumption that a write-off will reimburse the lost sale.
Build a useful evidence file
Create one review schedule for each specific customer balance being considered. Include the business entity, customer reference, invoice date, original amount, payments, credits and remaining amount. Link each total to the supporting detail so another reviewer can reproduce it.
For business bad debts, add the tax method, prior income inclusion, collection history, facts supporting worthlessness, proposed tax year and any charge-off. Identify who prepared the schedule and who approved the conclusion. Leave unresolved questions visible rather than converting them into an unexplained final number.
The IRS recordkeeping guidance emphasizes records that support income, expenses and return items. Choose a filing system suited to your business, but make the connection between evidence and tax treatment easy to follow. An attachment named “old invoices” is less useful than a clear reviewed schedule.
Our bookkeeping and tax records guide provides related operating context. Keep source documents, collection correspondence and the approved decision accessible to the people responsible. Limit broad sharing of customer information when a status summary will do.
Do not delete the original invoice or payment history merely because the balance is written off. Later collections, corrections and tax questions may still refer to it. Apply a record-retention policy based on the actual documents and applicable requirements, not a universal deletion date copied from another business.
Keep the cash-flow decision separate
When reviewing business bad debts, the owner needs two decisions: what to expect in the cash forecast and what tax treatment is supportable. A doubtful customer balance may deserve conservative cash planning before a tax deduction is established. Document the planning assumption without presenting it as a completed tax conclusion.
Business bad debts can expose weaknesses in customer approval, deposits, payment terms or follow-up. Use the review to identify a practical process change. For instance, decide who will resolve disputed work promptly and who can authorize new services for a customer with an unresolved old balance.
There is no need to turn the tax review into a promise of a new credit policy or a particular collection result. Different customers and contracts need different decisions. What matters is that someone owns the next action and that the cash forecast reflects a realistic expectation.
Our tax savings and cash-flow discussion explains why a potential tax reduction and available cash are different measures. Keep the proposed deduction separate from the amount you need to collect to meet payroll, rent or supplier payments.
Common mistakes to avoid
One mistake is writing off every invoice older than a chosen number of days. For business bad debts, replace that automatic rule with a review of the specific balance, collection evidence and relevant tax year. A payment that is late can still be collectible.
A second mistake is deducting unpaid cash-method service income that was never reported. Check the income history before computing the loss. Time spent on a project is commercially valuable, but an expected fee is not automatically a tax basis that can be deducted.
A third mistake is counting an already recorded cost again inside the unpaid fee. Review actual expenses separately under their own rules. Our expense classification guide explains why clear categories help prevent confusion about what an entry represents.
A fourth mistake is using a bookkeeping reserve as proof of a tax deduction. Business bad debts generally require the applicable specific-debt analysis, not simply a percentage applied to the whole aging report. Keep financial-reporting estimates and the tax calculation distinguishable.
Finally, do not ignore later collections. Match receipts to the original customer record and tell the preparer about any earlier deduction. A documented recovery process helps the books and return reflect what actually happened.
Frequently asked questions
Can a cash-method business deduct an unpaid service invoice?
Generally not for the unpaid fee itself if that amount was never included in taxable income. Actual paid or incurred costs need separate review under the business’s applicable rules. Do not claim the same expense twice by including it again in a proposed invoice write-off.
Are business bad debts deductible after 90 days?
There is no automatic deduction based only on that aging category. Review the genuine debt, prior income inclusion, collection steps, worthlessness and tax year. A report’s age column is an operating signal, not a tax determination.
Must I sue the customer first?
Not necessarily. The IRS says court action is unnecessary when a judgment would be uncollectible, but reasonable collection steps and evidence still matter. Review the particular facts and any legal issues with the appropriate adviser rather than assuming a lawsuit is always required or never useful.
Can only part of a business debt be deducted?
Potentially. Under the general specific charge-off method, partly worthless business bad debts have a charge-off limitation and other requirements. Nonbusiness debts follow different rules. Give the preparer reviewing business bad debts the specific facts and any prior deductions before deciding on an amount.
What if the customer pays after the write-off?
Record the receipt, identify the original debt and review the earlier tax treatment. A recovery of a previously deducted bad debt may be taxable, subject to the tax-benefit rule. The bookkeeping label alone does not determine the answer.
Conclusion
Business bad debts require more than an overdue invoice. Confirm the actual balance, the tax method and prior income inclusion, the evidence of worthlessness, the correct year and any charge-off requirements. Coordinate the approved result between the books and the return, and keep a process for later collections.
The useful next step is to select one doubtful customer balance and assemble its supporting file. Resolve the missing facts with your preparer before treating an accounting write-off as a tax deduction.
This article provides general federal tax information reviewed October 30, 2026. It is not individualized advice. Apply the guidance for the relevant tax year, business entity and specific debt, and review state treatment separately.
GET IN TOUCH
Schedule a FREE Call
Connect on our Socials!
