📩 Get A Quote : hello@veritasaccountingservices.com
A small outdoor-goods shop owner counts stock with a barcode scanner and paper count sheet beside a reminder that stock on the shelf is not always a tax deduction.

Inventory Tax Mistakes: A Simple Guide to Better Records

Cost of goods sold is not automatically the amount your business spent buying stock. Under a traditional inventory method, goods still on hand affect the calculation, and buying more before year-end does not necessarily create an immediate deduction. The first question is which tax inventory method your business actually uses.

For a small retailer, a rushed stock count can leave the tax preparer with a number that looks precise but lacks support. A bank withdrawal proves money moved. It does not explain which products arrived, what they cost, whether they were sold or whether some were taken home for personal use.

This guide explains five practical checks for US businesses that buy or make goods for sale. It uses a simple retail example and separates ordinary inventory calculations from small-business exceptions. It is a federal tax records guide, rather than a complete manufacturing, financial-reporting or state-tax manual.

Table of contents

What cost of goods sold measures

Think of the calculation as a bridge between goods available and goods remaining. For a straightforward reseller using a traditional inventory method, opening inventory plus net purchases, less closing inventory, produces the cost of goods sold. Production businesses can have additional cost components, so the simple retail formula is not a complete manufacturing schedule.

This is different from the selling price. A bottle purchased for $12 and listed for $30 does not become $30 of inventory cost simply because that is the price on its label. Keep the quantity record and the cost record connected, while showing sales values separately.

The IRS small-business tax guide explains the Schedule C calculation and the distinction between gross receipts, product costs and other business expenses. Schedule C provides a useful illustration for sole proprietors; a corporation or partnership uses its own return and applicable instructions.

For cost of goods sold, the method matters before the spreadsheet. A business may qualify for a small-business inventory exception, but that does not make every stock purchase immediately deductible. The practical checks below begin with the existing method so that a useful stock count is not mistaken for a new tax election.

Our inventory costs discussion considers overstocking and working capital. The narrower question here is how quantities, costs and tax methods support the product-cost figure on a federal return.

Five checks before preparing the return

1. Identify the method already used

Ask how the prior return calculated cost of goods sold, then obtain the inventory workpapers and a short description of the current tax method. A software setting called cash basis is not a complete explanation of how the business treats stock. The return preparer should be able to connect the method to the amounts carried into the current year.

The Schedule C instructions on inventory describe an exception for qualifying small-business taxpayers. Eligibility involves the applicable gross-receipts test and the tax-shelter restriction. Annual thresholds and related rules need a current-year check; do not copy an old dollar limit from an earlier publication.

Permitted alternatives include treating inventory as nonincidental materials and supplies or using an eligible financial-accounting treatment. Those alternatives have their own requirements. Under the nonincidental-materials method, recovery generally depends on customer delivery and payment or incurrence, whichever is later; calling stock supplies does not by itself accelerate the deduction.

For cost of goods sold, write down the method rather than relying on memory. Include who confirmed it and which return or workpaper supports it. If the business grew, changed ownership structure or inherited incomplete books, flag those facts for review rather than selecting a convenient treatment during the count.

2. Reconcile opening stock and purchases

When reviewing cost of goods sold, start with last year’s closing inventory and compare it with this year’s opening amount. If they differ, identify the reason and supporting adjustment. A changed opening balance can affect the calculation even when every current-year invoice is correct.

Next, review purchases using the supplier records, credit notes and receiving information. Separate merchandise from equipment, office costs and personal purchases. An invoice may contain several types of spending, so a single bank-feed category can hide details the tax preparer needs.

Cost of goods sold should not include a personal withdrawal of merchandise as though the goods were sold to a customer. Keep a simple log when an owner takes products for home or family use. Identify the item, date, quantity and cost so the adjustment is based on evidence.

Review supplier returns and allowances as well. A credit note can sit outside the original purchase entry and leave the stock-cost report too high. Ask the bookkeeper to explain how those credits reach the purchases total rather than assuming the payment balance will correct the calculation automatically.

3. Count the goods that belong in the calculation

To support cost of goods sold, set a clear count date and agree how movements during the count will be recorded. For example, keep a separate list of receipts and dispatches while staff count shelves. That practical control helps prevent one shipment from being included twice or omitted because it moved between locations.

Physical location alone does not settle ownership. Under the ordinary inventory rules, goods owned by the business can belong in inventory while in transit or held on consignment elsewhere. Goods belonging to another party do not become yours merely because they occupy your shelves. Check the contract and title facts when ownership is unclear.

For cost of goods sold, record quantities by a recognizable product identifier and unit. A carton and an individual unit are different measures. If one location counts cases of twelve and another records individual bottles, reconcile the units before multiplying by a cost.

List stock held at fulfillment centers, warehouses and other locations. Obtain the supporting report and reconcile transfers so the same goods are not counted twice. Mark unexplained differences for follow-up, rather than hiding them in a general adjustment that no one can reconstruct later.

4. Check cost, condition and classification separately

A stock count supports cost of goods sold by establishing how many items exist. A valuation review answers what amount belongs against them under the chosen method. Keep those two tasks distinct, with someone responsible for checking the unit costs and extending quantity times cost.

For cost of goods sold, review the treatment of freight and production costs with the preparer. Inbound freight on merchandise for resale is an inventory-cost consideration. Manufacturing can require additional labor and overhead analysis. A retailer should not copy a manufacturer’s cost schedule without understanding the difference.

The owner’s own unpaid time does not create a deductible wage cost. Likewise, using a selling price instead of the applicable inventory cost can distort the total. Our expense classification guide explains why the substance of a transaction matters more than its bank description.

Keep damaged, obsolete or slow-moving products visible on a separate exception list. A weak sales outlook is a reason to investigate valuation, rather than automatically remove the full cost from taxable income. Document the condition and ask which treatment is permitted under the business’s method before posting a tax adjustment.
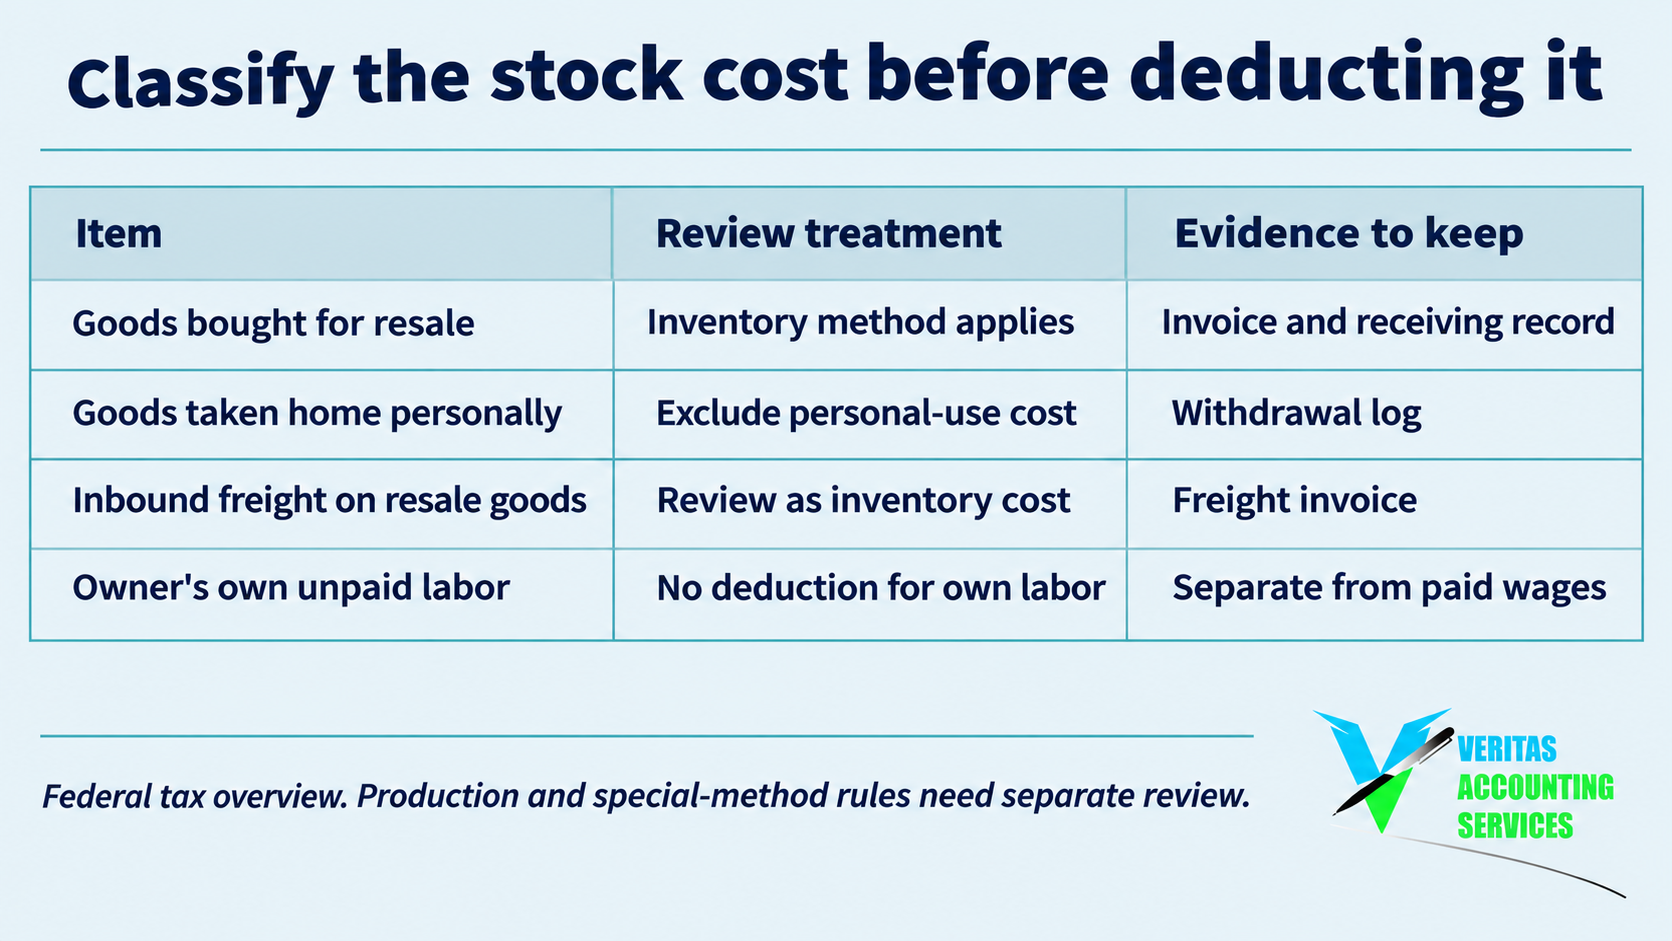
Comparison table for cost of goods sold records showing resale purchases, personal withdrawals, inbound freight and the owner's own unpaid labor, with review treatment and supporting evidence.

5. Review changes before implementing them

Before finalizing cost of goods sold, resist the temptation to switch methods simply to obtain a preferred tax result. A recurring treatment can be an accounting method, and changes can involve Form 3115 and adjustments. The IRS accounting-method guide explains why inventory methods require consistency and formal review.

For cost of goods sold, ask whether a proposed entry corrects a factual mistake, changes a valuation assumption or changes the tax method. Those are different questions. Label the proposed entry and retain the preparer’s reasoning before an approved adjustment is recorded.

The federal inventory regulation describes the small-business alternatives and their conditions. It also distinguishes an eligible inventory method from a simple decision to expense purchases. A method that matches eligible books and records needs its own analysis; it is not created by moving one entry at year-end.

Keep operational reporting useful even when a tax exception applies. The owner still needs to know which products exist, where they are and how much cash is tied up. Tax simplification and sensible stock control can work together without forcing the management report to be the tax calculation.
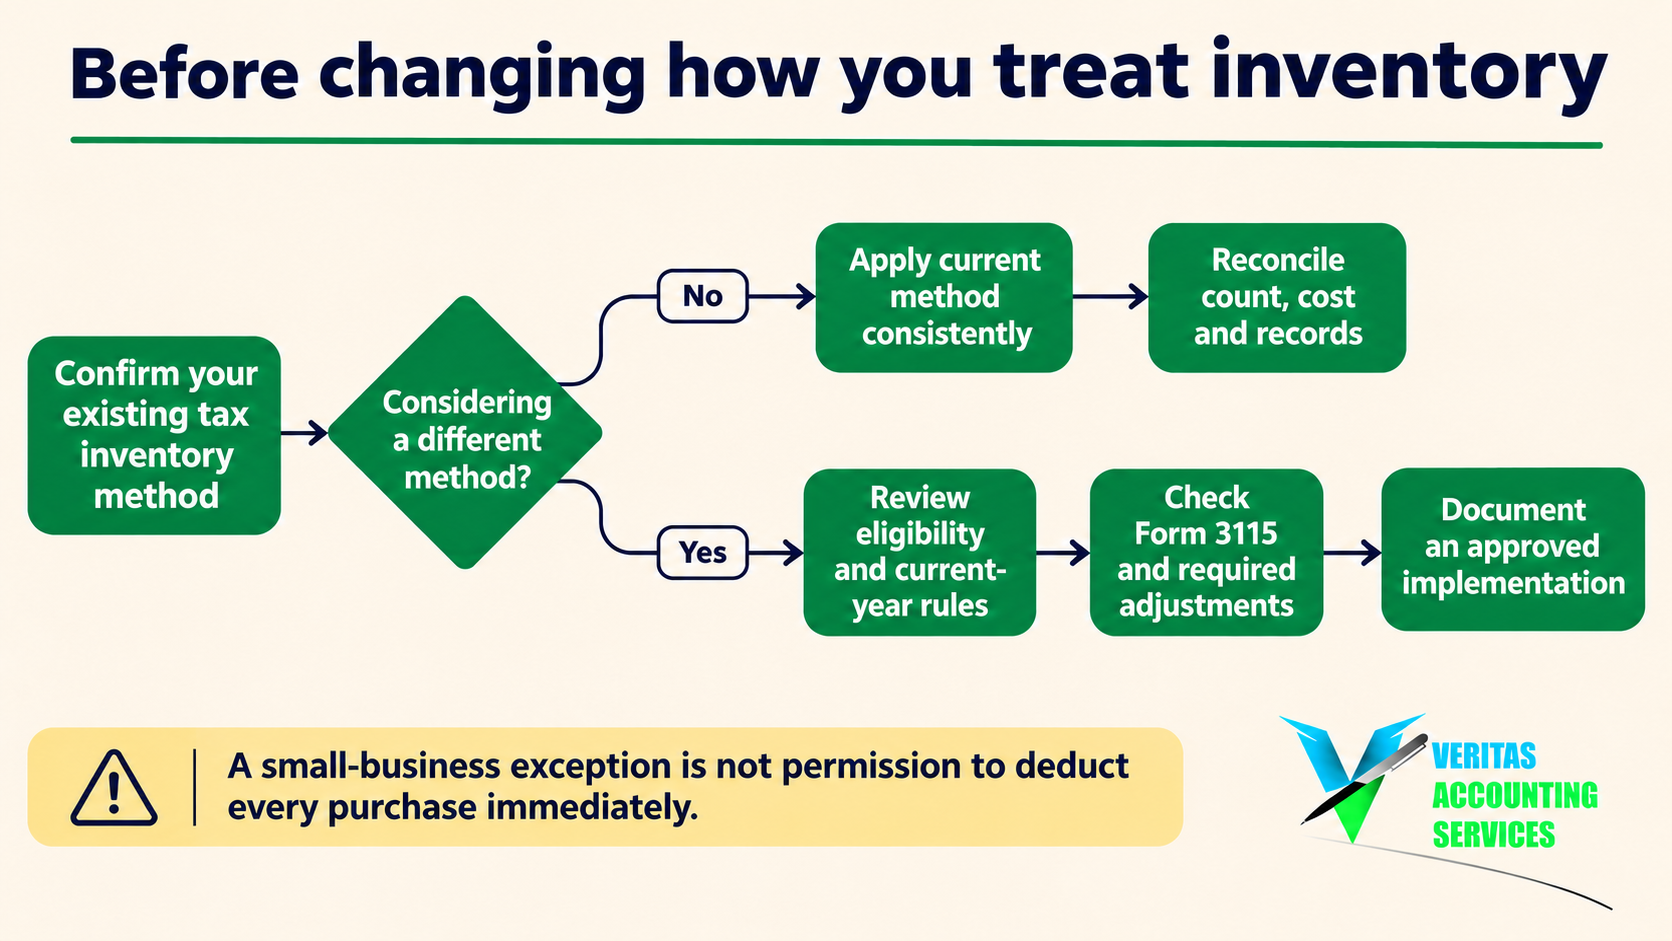
Decision tree beginning with the existing tax inventory method, distinguishing consistent application from a proposed change requiring eligibility, Form 3115 and adjustment review.

A worked retail example

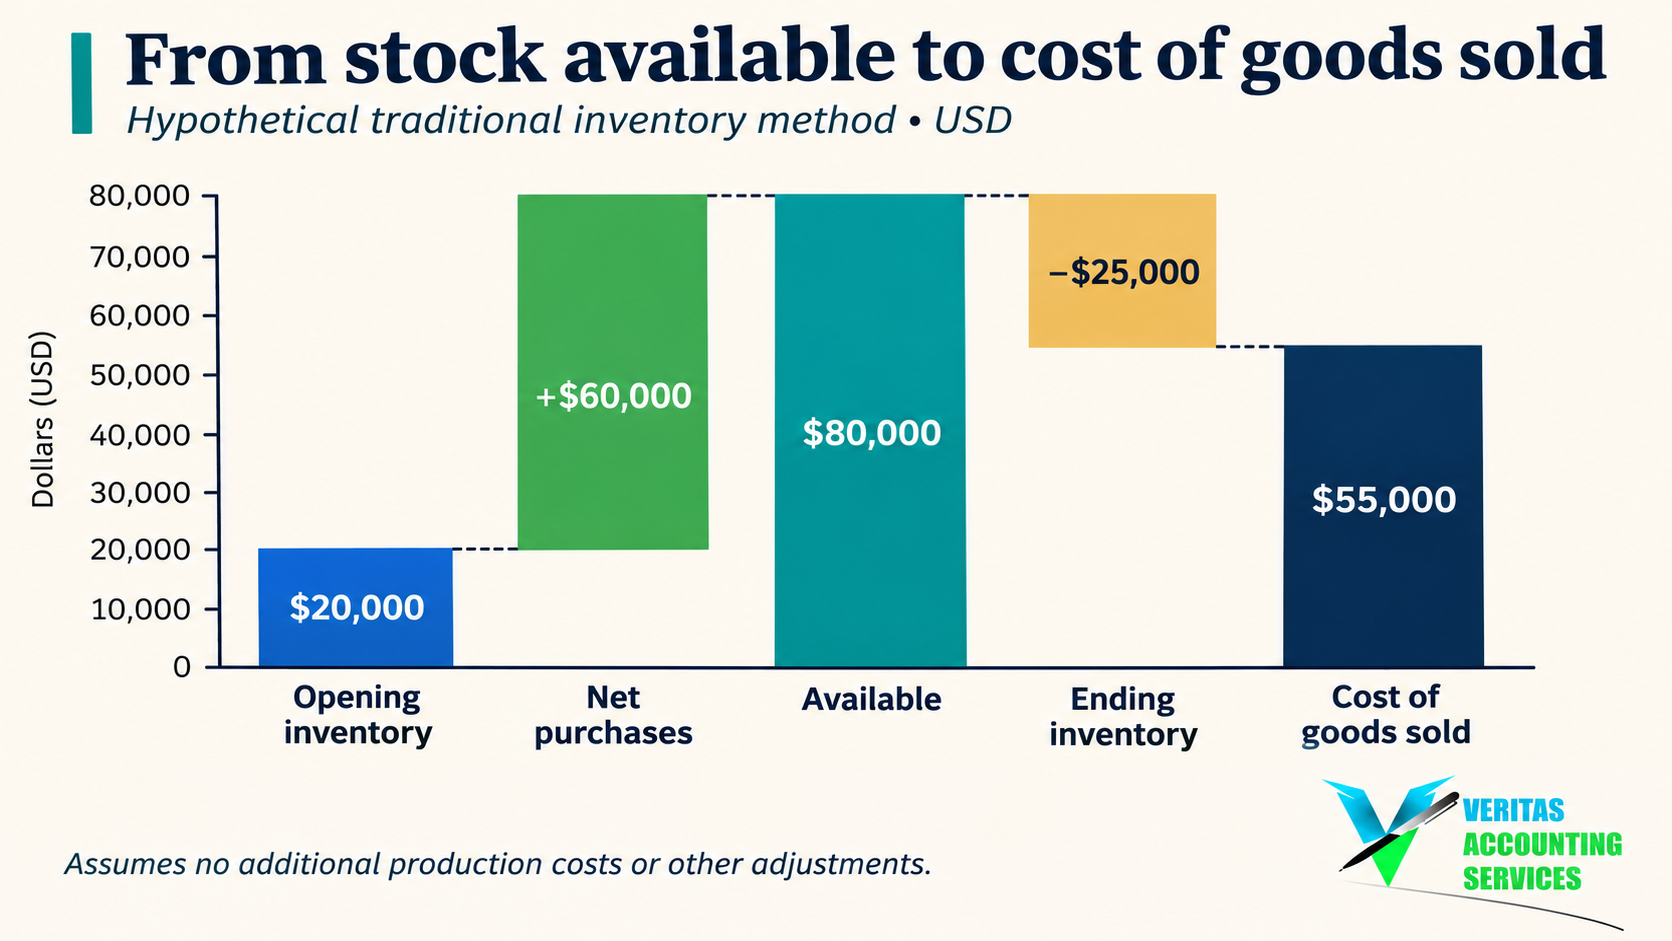
Suppose a small retailer uses a traditional inventory method and has $20,000 of opening inventory. Its net purchases of resale goods are $60,000 after the relevant purchase adjustments. A supported closing count and valuation show $25,000 remaining. Assume there are no additional production costs or other adjustments.

The cost of goods sold is $20,000 plus $60,000 less $25,000, or $55,000. The example does not calculate a tax bill. It only illustrates the product-cost calculation under the stated method, with hypothetical figures that do not describe a Veritas client.

ComponentHypothetical amount
Opening inventory$20,000
Add net purchases$60,000
Goods available$80,000
Less closing inventory$25,000
Cost of goods sold$55,000
Hypothetical cost of goods sold waterfall in USD: opening inventory $20,000 plus net purchases $60,000 gives $80,000 available, less $25,000 closing inventory gives $55,000.

Now suppose the closing inventory were mistakenly entered as $20,000 instead. With everything else unchanged, the calculation would produce $60,000. The $5,000 difference is a recordkeeping error, not an extra $5,000 of cash or a justified tax saving. Correcting the closing figure also protects the next year’s opening record.

Cost of goods sold must therefore be reviewed alongside the quantities and valuation evidence. A spreadsheet can add correctly while using the wrong inputs. Before approving the total, ask which document supports each component and whether the same cost was also deducted elsewhere.

Build a stock-count file someone can review

Create one folder for the count date with a short index. Include the location list, count sheets, supplier-cost support, adjustments and final reconciliation. Give files clear names so the reviewer can move from a summary amount to the underlying items without asking staff to repeat the count.

For cost of goods sold, a useful count sheet records the product code, description, location, quantity, unit of measure, applicable unit cost and extended value. Add the counter’s name, review date and explanation of unusual items. These are practical controls rather than a claim that the IRS mandates this exact template.

Keep evidence of ownership questions with the relevant goods. A warehouse report may show a location and quantity without explaining whose property the items are. Attach the purchase or consignment information needed for the preparer to resolve the question, and avoid substituting an assumption for missing records.

Link the final inventory report to the general ledger and the tax workpaper. If those totals differ, provide a bridge explaining the difference. A management report can present cost of goods sold for a different purpose; the reviewer needs to know which adjustments connect it to the return.

The IRS recordkeeping overview emphasizes records that support income, expenses and return entries. Our bookkeeping and tax records guide adds practical context for keeping the information organized. A readable evidence trail is more useful than a folder full of unnamed screenshots.

Investigate differences before posting adjustments

An inventory difference is a question to resolve, rather than a direction to post a single loss entry. Start by checking quantity units, receiving dates, duplicate product codes and movements between locations. Then review the cost assigned to the items and the accounting period involved.

For cost of goods sold, distinguish a missing supplier credit from missing physical stock. One affects the cost record; the other may involve a count problem, an unrecorded sale, damage or another event. Each explanation needs its own support and may lead to a different correction.

Keep a cost of goods sold exception register with the amount, possible reason, evidence requested, responsible person and resolution. Keep the original report and the approved revised version. That makes it possible to explain a change without reconstructing it from the final journal entry alone.

Avoid forcing cost of goods sold to produce the margin you expected. An unusual margin can prompt investigation, but it is not proof that the inventory total must be changed. Pricing, discounts, sales mix and recording differences can all be useful questions for the review.

Connect inventory decisions to cash flow

The business can spend cash on goods before the tax method permits recovery of their cost. That timing difference makes a stock purchase different from a guaranteed current deduction. Consider expected sales and funding needs before placing a large order for tax reasons.

For cost of goods sold, keep the cash forecast separate from the tax calculation. Supplier payment terms affect when money leaves the bank; product movement affects what remains available to sell. Neither report should be silently substituted for the other.

Our tax savings versus cash flow discussion explains this broader decision. A good purchasing decision should make commercial sense before any possible tax effect. Review slow-moving lines and future commitments while the count information is still current.

Questions to take to your tax preparer

When reviewing cost of goods sold, ask the preparer to confirm the inventory method, the relevant tax-year rules and the records still missing. Bring the prior closing balance, current count, purchase adjustments and unresolved ownership or valuation questions. The aim is a supported calculation, rather than a request to approve a number without context.

For cost of goods sold, ask which costs are recovered through inventory and which belong elsewhere. Confirm that personal withdrawals and duplicate deductions have been addressed. If a method change is proposed, request the implementation steps and any required filing review before the books are changed.

Agree who will supply the remaining evidence and when. A short list of open questions is easier to complete than a general request to clean up inventory. Retain the final explanation with the workpapers so next year’s opening position is understandable.

Frequently asked questions

Is cost of goods sold the same as inventory purchases?

No. Under a traditional inventory method, opening stock, closing stock and applicable purchase adjustments affect the result. Production businesses can have additional costs. Start with the method actually used rather than treating the total supplier payments as the final deduction.

Can a small business deduct all unsold stock immediately?

Not automatically. A qualifying small-business exception permits specified inventory methods, each with conditions. The nonincidental-materials alternative does not simply allow an immediate deduction when goods are bought. Check eligibility and the selected method with the preparer.

Should I value stock using its selling price?

Not just because a price tag is available. Use the valuation basis permitted under the business’s inventory method and retain cost support. A management report showing potential sales revenue serves a different purpose from a supported tax inventory figure.

Do products at a fulfillment warehouse count?

Review ownership and the applicable method. Under ordinary inventory rules, your owned goods may belong in inventory even when held elsewhere. Reconcile the warehouse report with your own locations and transfers so items are not omitted or counted twice.

What if the count reveals damaged or obsolete goods?

Document the items, quantities and condition, then review the permitted tax treatment. Slow sales alone do not establish a particular write-down. Keep the operational concern visible while the tax preparer considers the method and evidence.

Can software calculate cost of goods sold for me?

Software can calculate from its settings and recorded transactions. It cannot resolve missing goods, mixed units or an unsupported method by itself. Review inputs, exceptions and the reconciliation before accepting a report as the return figure.

Conclusion

Reliable cost of goods sold starts with the inventory method and ends with evidence someone else can follow. Connect opening balances, purchases, ownership, quantities and permitted costs before relying on the final total.

Before the next count, prepare a location list and identify who will check quantities, costs and exceptions. A clear handoff gives your bookkeeper and tax preparer a useful starting point and helps you understand the money still sitting on the shelves.

This article provides general US federal tax information reviewed November 4, 2026. It is not individualized advice. Confirm the applicable tax year, business facts and current return instructions; state requirements and financial-reporting rules can differ.

GET IN TOUCH

Schedule a FREE Call

Contact us

Connect on our Socials!

A freelance business owner holding a tape measure stands in the doorway of a dedicated home office lit by morning sunlight.

Your Simple Guide to Home Office Mistakes and Better Records

A home office deduction may be available when a qualifying part of your home is used for business. Owning a desk, working remotely or paying household bills does not establish eligibility by itself. Check how the space is used, why it qualifies and which calculation method fits the facts before putting an amount on the return.

For a US sole proprietor, the main questions are practical: Is this an actual business area? Is its use regular and, where required, exclusive? Does it meet a qualifying business-use test? After those questions, you can compare the simplified option with actual expenses and apply the relevant income limitation.

This guide focuses on a sole proprietor filing Schedule C. It does not treat a corporate shareholder, partner, employee, daycare provider or landlord as having identical rules. The examples are hypothetical and the discussion covers federal tax. State treatment and unusual arrangements need their own review.

Table of contents

Home office deduction: start with eligibility

The IRS business-use-of-home overview describes several ways a home can qualify. For an ordinary office, these include exclusive and regular use as a principal place of business or as a place to meet clients in the normal course of business. A separate unattached structure has another qualifying route.

A home office deduction also has special rules for certain inventory storage and daycare uses. Those exceptions have conditions; they are not a general waiver for every room with a laptop. Identify the relevant route before comparing amounts or choosing a tax-software category.

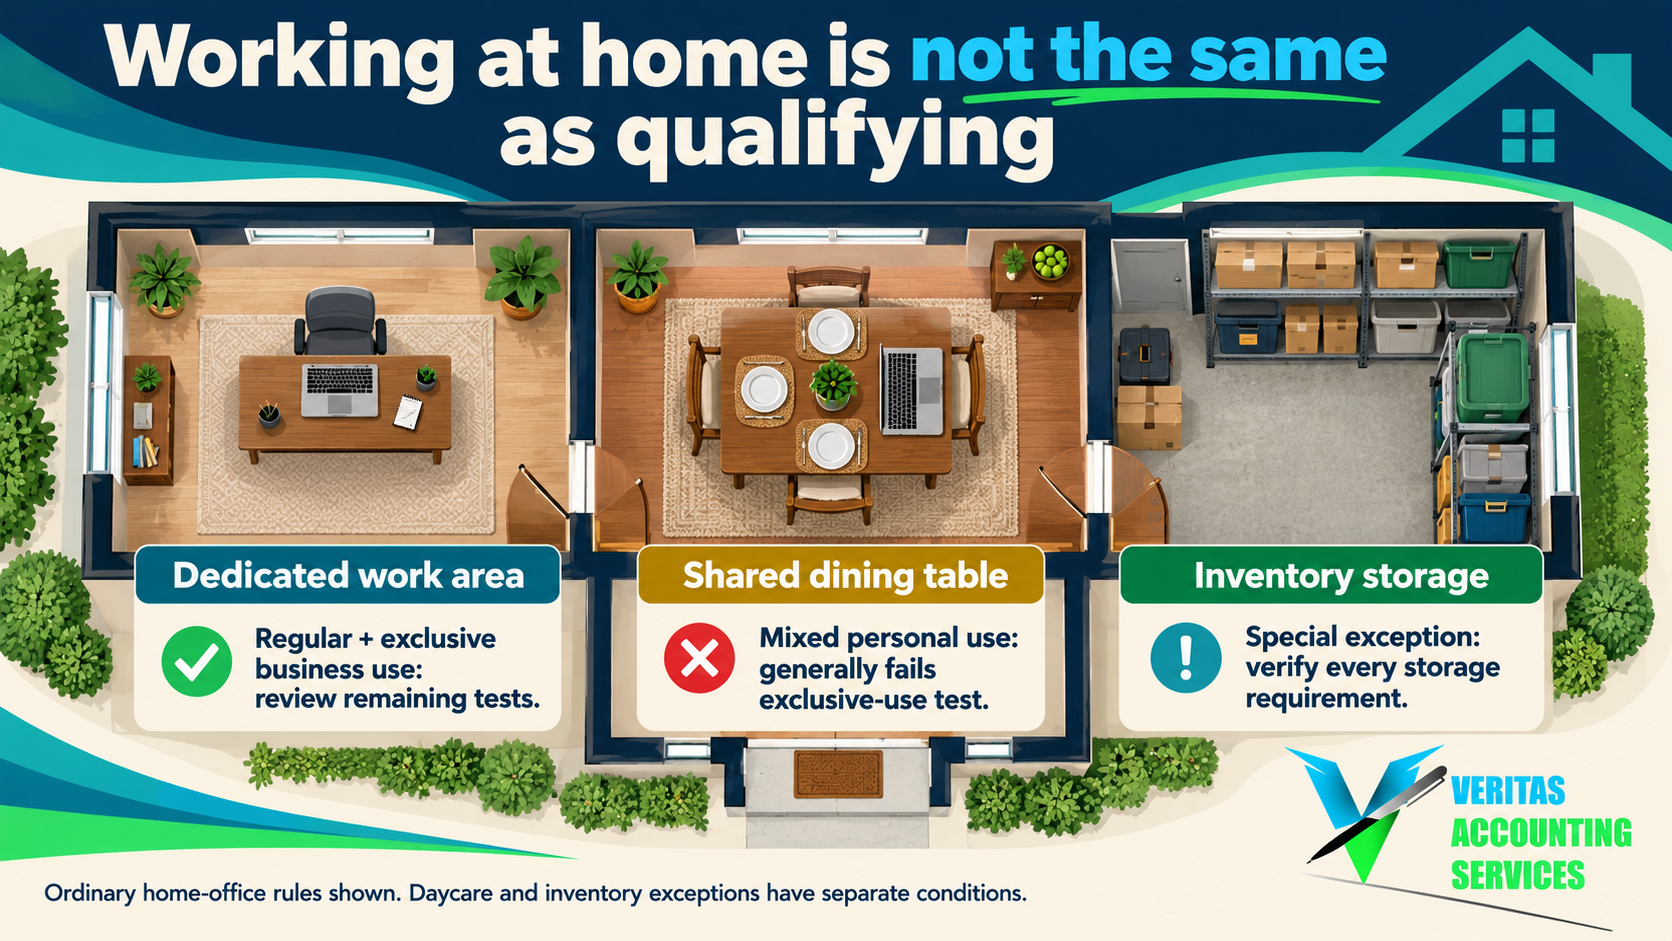
Imagine a consultant who sends proposals from a dining table that the family uses for meals. The work may be genuine, but the same area also serves a personal purpose. Contrast that with a separately identifiable area used only and regularly for the consultant’s business. The second arrangement still needs the remaining tests reviewed, but the space-use facts are different.

For the home office deduction, describe what happens in the space rather than relying on the room’s name. A room labeled office on a floor plan can still be used personally. Conversely, qualifying space need not be an entire enclosed room with a permanent wall around it.

Illustrative floor-plan comparison for the home office deduction showing a dedicated work area, a mixed-use dining table and inventory storage with separate exception requirements.

The IRS Publication 587 provides more detail. The currently available edition is for 2025. This article uses its general eligibility, allocation and recordkeeping principles alongside current IRS topic and simplified-option guidance; it does not apply an old annual equipment limit to a later return.

Five checks before choosing a method

1. Identify the business and the person claiming the expense

A home office deduction begins with a trade or business, not simply an activity performed at home. Make clear which business uses the area and who is preparing the claim. Managing personal investments or handling household paperwork should not be mixed into the explanation of an operating business.

If you operate through a corporation, do not copy a sole proprietor’s Schedule C entry into your personal return. Reimbursements and entity arrangements raise separate issues. Partners also have specific reporting and reimbursement considerations. The correct starting point is the actual legal and tax structure.

The simplified option does not create a personal deduction for ordinary employee home-office expenses. The IRS simplified-option page specifically distinguishes employee expenses from qualifying self-employment use. Someone can have wages and a separate business, so identify which activity actually uses the space instead of deciding from employment status alone.

Our accountable plan guide explains the separate employer reimbursement process. Use it for that question rather than assuming a corporate reimbursement and an owner’s home office deduction follow the same filing route.

2. Confirm regular use and the exclusive-use requirement

For the home office deduction, regular use requires more than occasional or incidental business activity. Explain the normal pattern: what work happens there, when it happens and how the area supports the business. The IRS evaluates the facts and circumstances; there is no universal shortcut based on owning a particular desk.

Exclusive use means the identified area is used only for the business when that requirement applies. A shared family recreation space generally fails this test even if substantial work also happens there. A photo taken with personal items removed does not change the actual pattern of use.

The IRS allows a room or another separately identifiable area, without requiring a permanent partition. Measure the area you can support. Do not claim an entire bedroom merely because a small work area occupies one corner while the rest continues to serve personal purposes.

For a home office deduction involving inventory or product samples, check the exception carefully. Publication 587 describes requirements including a wholesale or retail selling business, regular storage, a suitable separately identifiable area and the home as the business’s only fixed location. Daycare has its own rules. Ask about the applicable exception instead of assuming exclusivity never matters.

3. Explain why the location qualifies

Regular and exclusive use does not complete every home office deduction test. An ordinary office also needs a qualifying business-use basis, such as being the principal place of business. The IRS considers the importance of activities at different locations and the time spent at those locations.

A home office can qualify as the principal place of business when it is used exclusively and regularly for administrative or management activities and there is no other fixed location where substantial administrative or management activities are conducted for that business. This can matter for an owner who performs customer work elsewhere.

Examples of administrative work include billing, maintaining records, ordering supplies and arranging appointments. Keep the description specific to the business. The important question is not whether the home contains the biggest workspace, but whether the relevant legal conditions fit the actual activities and locations.

For the home office deduction, tell the preparer about any outside office, workshop or recurring business location. Using a home address on invoices is not conclusive. Meeting clients at home and using a separate structure are additional routes with their own conditions, rather than reasons to ignore the eligibility analysis.

4. Measure the space and document changes

The home office deduction calculation needs defensible measurements. Keep a simple sketch showing the qualifying area and explain the measurement method. Under actual expenses, you also need an appropriate business-use allocation. Do not copy a percentage from a previous return after the layout or use has changed.

Dates matter as well as area. Record when qualifying use began, ended or changed. If a former office becomes a guest room, or you move during the year, the prior full-year calculation may no longer fit. Give those dates to the preparer before the worksheet is finalized.

For the simplified home office deduction, part-year use or area changes involve average monthly allowable square footage. IRS guidance limits the area counted for any month to 300 square feet and counts a month only when there are at least 15 days of qualified use. A full-year example should not be applied automatically to a room first used near year-end.

If another person or another qualifying business uses the space, flag that too. The same square feet cannot simply be claimed twice. Publication 587 discusses allocation and multiple-business situations; a shared household does not multiply the available area without regard to actual use.

5. Review the method, income limit and earlier claims together

A home office deduction is not necessarily the largest amount produced by a calculator. Compare the available methods only after eligibility is established. Then review income limitations, prior actual-expense carryovers and any depreciation history that could affect the decision.

The IRS allows a choice between simplified and actual-expense methods for a tax year. Its guidance says the choice is made on a timely filed original return and cannot later be changed to the other method for that same year. A different method may be chosen for a subsequent year.

For the home office deduction, explain any previous claims before deciding that a simpler worksheet solves everything. The simplified method has different carryover and depreciation treatment. A preparer needs the earlier records to understand those effects, even if the current year’s area measurement seems straightforward.

Compare simplified and actual expenses

The IRS simplified-option comparison explains the central difference. The simplified calculation generally uses $5 for each eligible square foot, with a maximum of 300 square feet. This creates a maximum full-year calculation of $1,500 before the income limit and other applicable adjustments.

The simplified home office deduction changes the calculation and recordkeeping burden; it does not relax eligibility. A personally used area does not become qualifying because the standard rate is easy to apply. For the home office deduction, keep the space, dates and business-use explanation even if you do not allocate household bills under this method.

Actual expenses use qualifying costs and an appropriate business allocation. Direct costs relating only to the qualifying business area and indirect costs benefiting the home generally receive different treatment. An expense unrelated to the business part should not be included merely because it appears on the same household statement.

QuestionSimplified optionActual-expense method
Starting calculation$5 times eligible area, subject to the 300-square-foot cap and adjustmentsQualifying actual costs and supported business allocation
EligibilityBusiness-use tests still applyBusiness-use tests still apply
Depreciation of the homeNo home depreciation for simplified yearsReview business-use depreciation and later sale effects
Income limitationApplies; unused simplified amount does not carry forwardApplies; some disallowed expenses may carry forward
RecordsSupport eligibility, area, dates and incomeAlso support actual costs, allocation and relevant property history
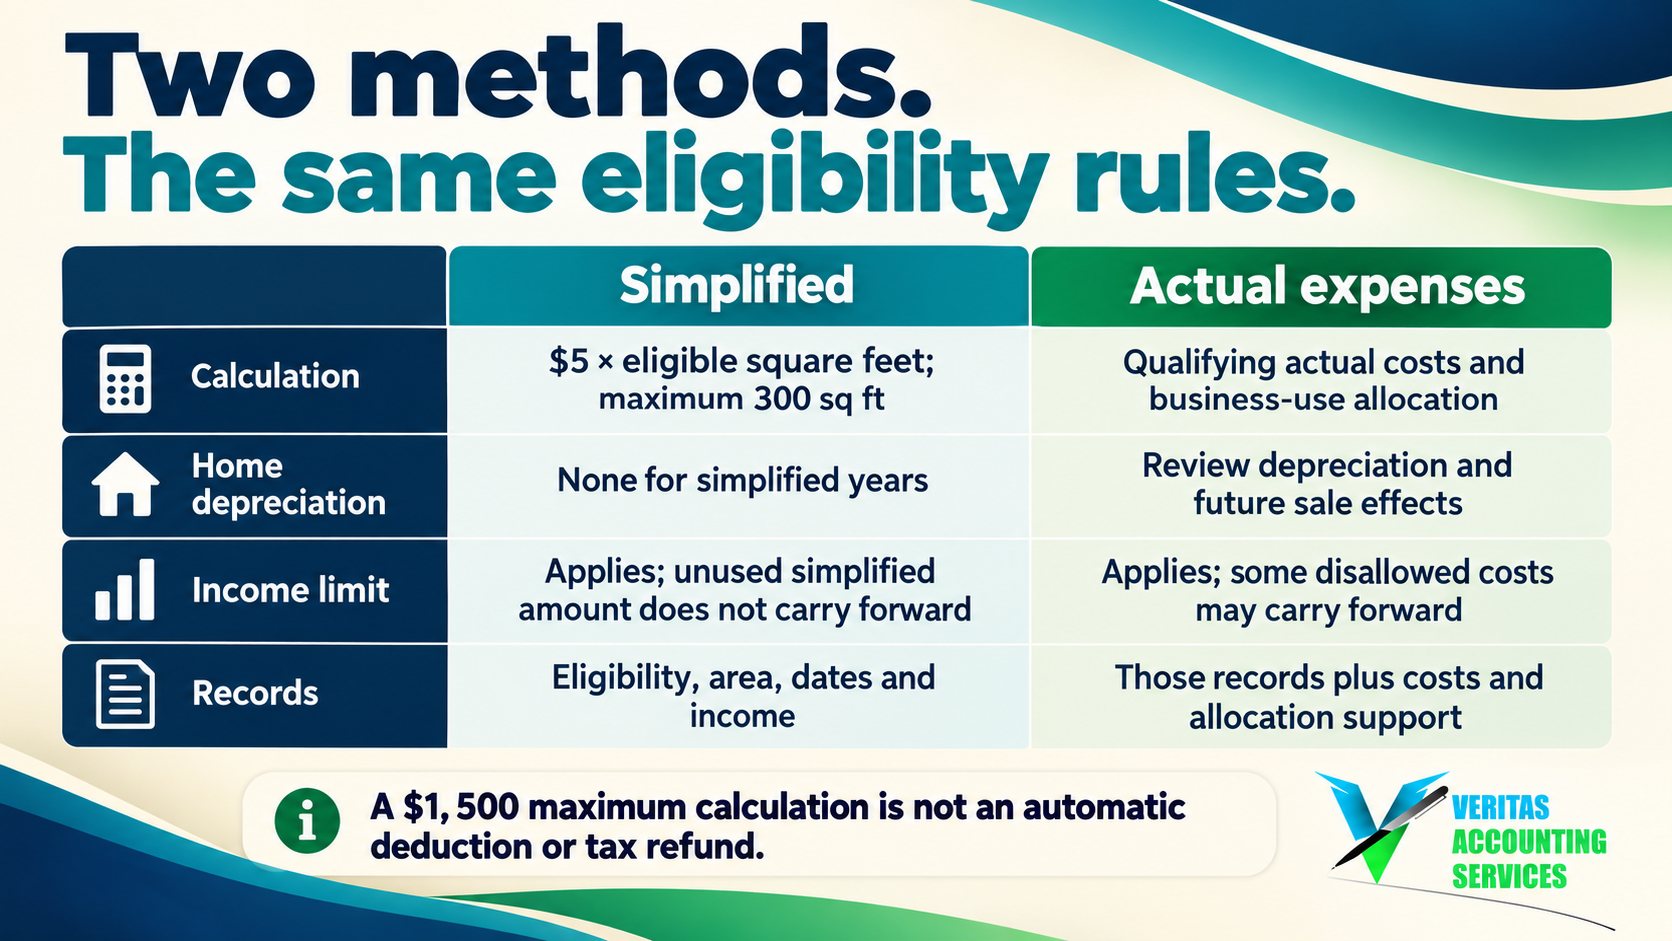
Comparison of simplified and actual-expense home office deduction methods, covering calculation, home depreciation, income limits and required records.

For the home office deduction under the simplified option, do not also deduct the actual home-use costs it replaces. Otherwise allowable home-related itemized deductions remain subject to their own rules. Business equipment, supplies and other costs unrelated to the use of the home itself require separate analysis; they are not automatically absorbed into the area calculation.

The actual-expense home office deduction can involve depreciation and consequences when the home is sold. The simplified option does not generate depreciation for the years it is used, but it does not erase earlier actual-method history. Avoid treating a method switch as permission to discard old property records.

Our expense classification article explains why a clear category matters. For a home office deduction, keep household costs, ordinary operating expenses and equipment purchases distinguishable so the preparer can review each under the correct rules.

See how the income limit changes an example

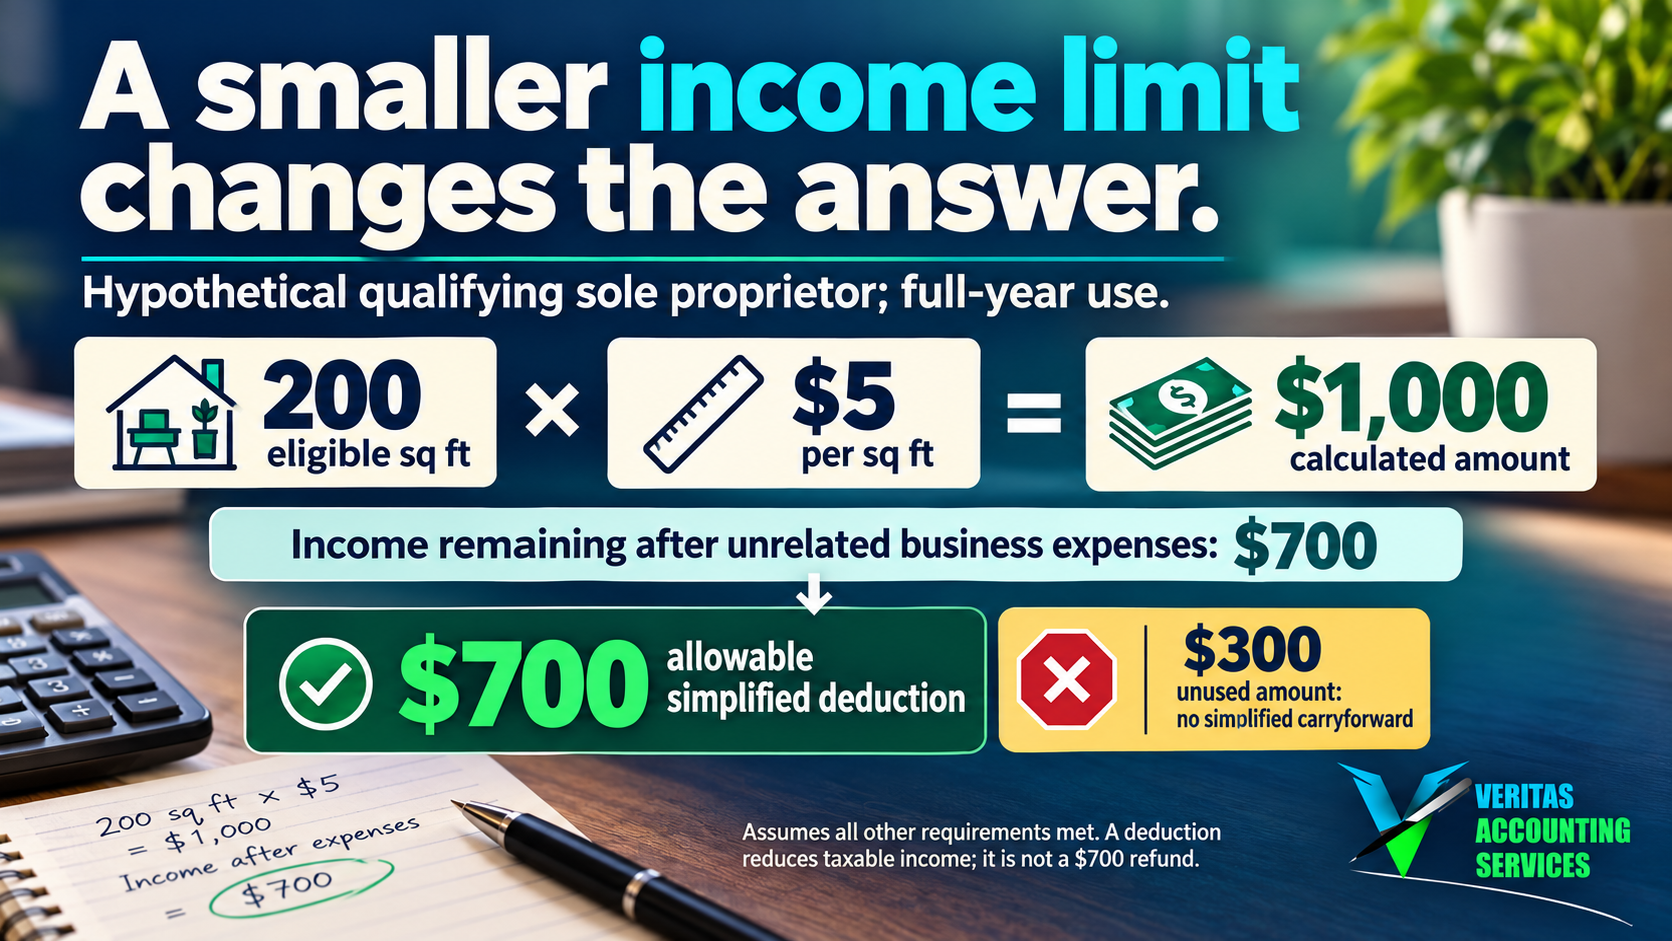
Suppose an eligible sole proprietor uses 200 square feet exclusively and regularly for a qualifying business throughout the year. Assume all other requirements are met and the simplified option is properly selected. The initial calculation is 200 multiplied by $5, or $1,000.

Now assume gross income attributable to the qualified business use, reduced by business deductions unrelated to use of the home, leaves $700. The home office deduction under the simplified method cannot exceed that remaining amount. In this illustration, the allowable deduction is $700 rather than the initial $1,000 calculation.

Hypothetical simplified deduction calculation showing 200 eligible square feet times $5 equals $1,000, reduced by a $700 income limitation to a $700 deduction with $300 unused and no simplified carryforward.

The $300 difference does not become a simplified-method carryforward. That is different from the possibility of carrying forward certain disallowed actual-method expenses. The example does not establish that the simplified option is better or worse for this owner; a proper comparison requires the alternative calculation and relevant history.

A home office deduction is a deduction, not a dollar-for-dollar tax refund. The final tax effect depends on the entire return and applicable rules. No tax rate is assumed here, and the $700 result should not be described as $700 cash saved.

If the area qualified for only part of the year, the initial amount would need an area-and-date adjustment before considering the income limit. If the space failed eligibility, the arithmetic would not rescue the claim. Check the facts in the same order used in the example.

Build a useful evidence file

For the home office deduction, keep one short explanation of the business use with the measurements and dates. Include what work occurs there, how personal use is excluded where required and why the location qualifies. A reviewer should be able to understand the claim without recreating the whole year from memory.

Under actual expenses, retain the bills and supporting calculation for the amounts claimed. Distinguish a payment from an invoice, and distinguish an expense from an improvement needing different treatment. When the household pays one combined amount, document how the business portion was determined instead of posting the whole charge as business.

Keep earlier home office deduction worksheets and relevant depreciation records available. Purchase, improvement and basis documents can remain important for later calculations. Do not apply a casual document-deletion rule to property history simply because the current year uses a simplified method.

Our bookkeeping and tax records guide provides related operating context. A tidy folder helps, but the evidence must explain the business facts as well as the amount. Label uncertain items so the adviser can resolve them before filing.

Separate household cash flow from tax treatment

A home office deduction does not make a rent payment, utility bill or renovation free. The household still needs enough cash to pay the full bill. Keep the tax calculation separate from the decision about what the household and business can afford.

Before expanding the work area, identify the practical reason: more capacity, better concentration or a genuinely useful business setup. Then consider the cash commitment. Buying a larger home or remodeling solely to pursue a deduction can create costs far beyond any possible tax benefit.

For the home office deduction, avoid transferring money between personal and business accounts without a clear explanation of what it represents. The accounting entry should match the arrangement and entity. Ask the preparer how the approved deduction or reimbursement should be reflected rather than assuming every transfer is rent or an expense.

Our tax savings versus cash flow article discusses the broader distinction. Use a household budget for payment decisions and a supported tax worksheet for the deduction. Neither replaces the other.

Questions to resolve before filing

Review the home office deduction before the return is ready for signature. Confirm the business identity, actual use, qualifying route, measured area, dates and selected method. Discuss income limitations and previous claims with the person responsible for the return.

Tell that person about changes that could alter the answer: a move, shared use, another fixed office, a new entity or a room returning to personal use. These are facts to assess, not automatic disqualifications in every case. Early disclosure leaves time to choose the correct treatment.

The IRS simplified-method FAQs address elections, area changes and income limits. Use the current instructions for the return being filed. A general guide should help identify the right questions, while the final claim reflects your own facts.

Frequently asked questions

Can I claim a home office deduction for a shared dining table?

Under the ordinary exclusive-use rule, using the same area personally and for business generally prevents a claim for that area. Working many hours there does not remove the personal use. Inventory storage and daycare exceptions have separate requirements and should not be assumed to cover ordinary desk work.

Do I need a separate room?

Not necessarily. IRS guidance recognizes another separately identifiable space and does not require a permanent partition. The claimed area must still satisfy regular use, exclusive use where required and the applicable qualifying business-use test.

Is the simplified option an automatic $1,500 deduction?

No. It generally starts at $5 per eligible square foot, capped at 300 square feet. Eligibility, qualified-use dates, area changes and the income limitation can reduce or eliminate the amount. A smaller qualifying area produces a smaller starting calculation.

Can I deduct actual home-use expenses as well as the simplified amount?

You cannot combine the simplified amount with the actual home-use costs it replaces. Otherwise allowable itemized deductions and business costs unrelated to use of the home need separate treatment under their own rules. Keep those categories clear when supplying records.

Can I change methods after filing?

The IRS says the method chosen on a timely filed original return cannot later be changed to the other method for that same year. A different home office deduction method may be selected for another year. Review the decision and earlier history before filing.

Conclusion

A supportable home office deduction starts with the use of the space, not the largest possible calculation. Confirm eligibility, measure the qualifying area, document dates and compare the methods with income limits and earlier claims in view.

Start today with a simple sketch and a short description of what actually happens in the work area. Add the relevant records and take unresolved questions to your preparer before the return is finalized.

This article provides general US federal tax information reviewed November 2, 2026. It is not individualized advice. Confirm the rules for the relevant tax year, entity and facts, and review state treatment separately.

GET IN TOUCH

Schedule a FREE Call

Contact us

Connect on our Socials!