📩 Get A Quote : hello@veritasaccountingservices.com
Flower shop owner compares a bank statement with a ledger after closing.

When the Bank Balance and Your Books Disagree

A bank reconciliation check helps you explain why the balance on a business bank statement differs from the cash balance in your books. The difference may have a simple explanation. A deposit recorded on the last day of the month might show up at the bank the next morning, or the bank may have posted a fee you haven’t entered. Your job is to find evidence for each difference and decide what belongs in the books.

Consider a flower shop preparing to close the month. The bank statement ends at $9,850, while the bookkeeping report shows $10,630. The owner wants to know whether the books are missing something and whether the balance is useful for planning next week’s purchases. This guide walks through five checks with that fictional example, then shows what to save and what still needs follow-up.

Table of contents

Start the bank reconciliation check with the same period

Pull the official statement for the account and period you intend to reconcile. Write down the ending date and balance, then open the cash ledger for the same account through that date. If you have separate checking, savings and card accounts, confirm the account name and last few digits before starting. One bank reconciliation check per account keeps an error in one register from being hidden by an unrelated balance in another.

Use the statement ending balance rather than the available balance on the bank’s current homepage. An available balance can reflect activity or holds after the statement date. For example, when you reconcile October on November 4, a November 3 deposit may already be included in today’s available balance. Including it as part of October’s statement activity would make the difference harder to explain.

Compare your beginning reconciliation balance with the previous completed reconciliation. If the figures differ, look for a change to a previously cleared transaction, such as a deleted check or an edited deposit. Document the change before matching the new period. If you’re taking over an account that has never been reconciled, ask the owner or previous bookkeeper for the last reliable statement and supporting ledger. Agree on where to start and keep a list of gaps that need reconstruction.

The IRS guide to starting a business and keeping records explains checking account reconciliation and why statements and books can differ. The bank reconciliation check in this guide is a management bookkeeping routine. It compares activity and supports the records you keep. Veritas also covers how to organize the source documents behind the ledger. Good bookkeeping and tax records

Match transactions before changing anything

Work from the statement lines and match each deposit, withdrawal or transfer to supporting records. Use the amount, the reference and the business purpose together. A statement may abbreviate a payee or post a transaction on a different date from the receipt. A small gap in date can make sense, but a match needs a defensible link to the same transaction.

If two payments are the same amount, check invoice numbers or the payment confirmation before matching either one. A flower shop might pay $180 twice to the same wholesale supplier in one week. A match based on the first amount you find can leave the wrong bill showing as paid, even when total cash looks right. The bank reconciliation check should help you match the right underlying item as well as the right number.

Merchant payouts are another common source of confusion. Suppose several card sales appear in the point-of-sale report and the processor sends one deposit covering the batch. Use the payout report to connect the bank deposit to the underlying activity. For a payout that contains fees, refunds or adjustments, trace those lines to the processor’s report before changing any sales entry. If the deposit is already recorded in the books, match the imported bank-feed line to that record where appropriate. Adding it as a new sale can count the same activity twice.

Transfers need similar care. If you move $800 from business checking to business savings, look for a withdrawal in checking and a corresponding deposit in savings. Verify both legs against the transfer confirmation and match them to the records in each account. If only one side has cleared by the statement cutoff, note the timing and verify the other side in the next period. This step keeps an ordinary transfer from showing up as new sales or an expense simply because you imported two bank lines.

After you’ve matched the clear items, make two short lists. One is for entries in your books that the bank hasn’t posted by the statement date. The other is for bank entries you can’t find in your books. The next bank reconciliation check is much easier when those two lists remain separate. If you’re working with a bookkeeper, send the statement line, relevant receipt or payout report and a short description for each uncertain item. That gives them enough context to investigate without making a guess.

Separate timing from missing entries

A deposit in transit is money already recorded in the books that the bank hasn’t posted by the statement cutoff. Check the deposit receipt or processor payout record, then look at the next statement or subsequent posted activity to see whether the money arrived. If you can trace the item, show it on the bank side of your bank reconciliation check. The worksheet explains the delay. You already recorded the deposit once.

An outstanding check is a payment already recorded in your books that hasn’t cleared the bank. Check the payee, number, amount and issue date against the payment record. List it on the bank side as a subtraction from the statement balance. The payment will reduce the bank balance when it clears. If a check stays outstanding longer than expected, investigate delivery and payment status before reissuing or reversing it.

A fee on the bank statement that you haven’t recorded is a different kind of item. Verify the charge and record it in the appropriate account. Bank interest credited to the account can also require a book entry. Use the actual statement date and amount, and keep the statement line with the record. A bank reconciliation check gives you a reason for the change and leaves evidence the next reviewer can follow.

If a withdrawal is unfamiliar, gather the transaction details and check with the people who use the account. Follow up with the bank promptly if you suspect an unauthorized transaction. Keep the item visible with a status, a named owner and the next review date. A quick entry to make the difference disappear can obscure the very activity you need to investigate.
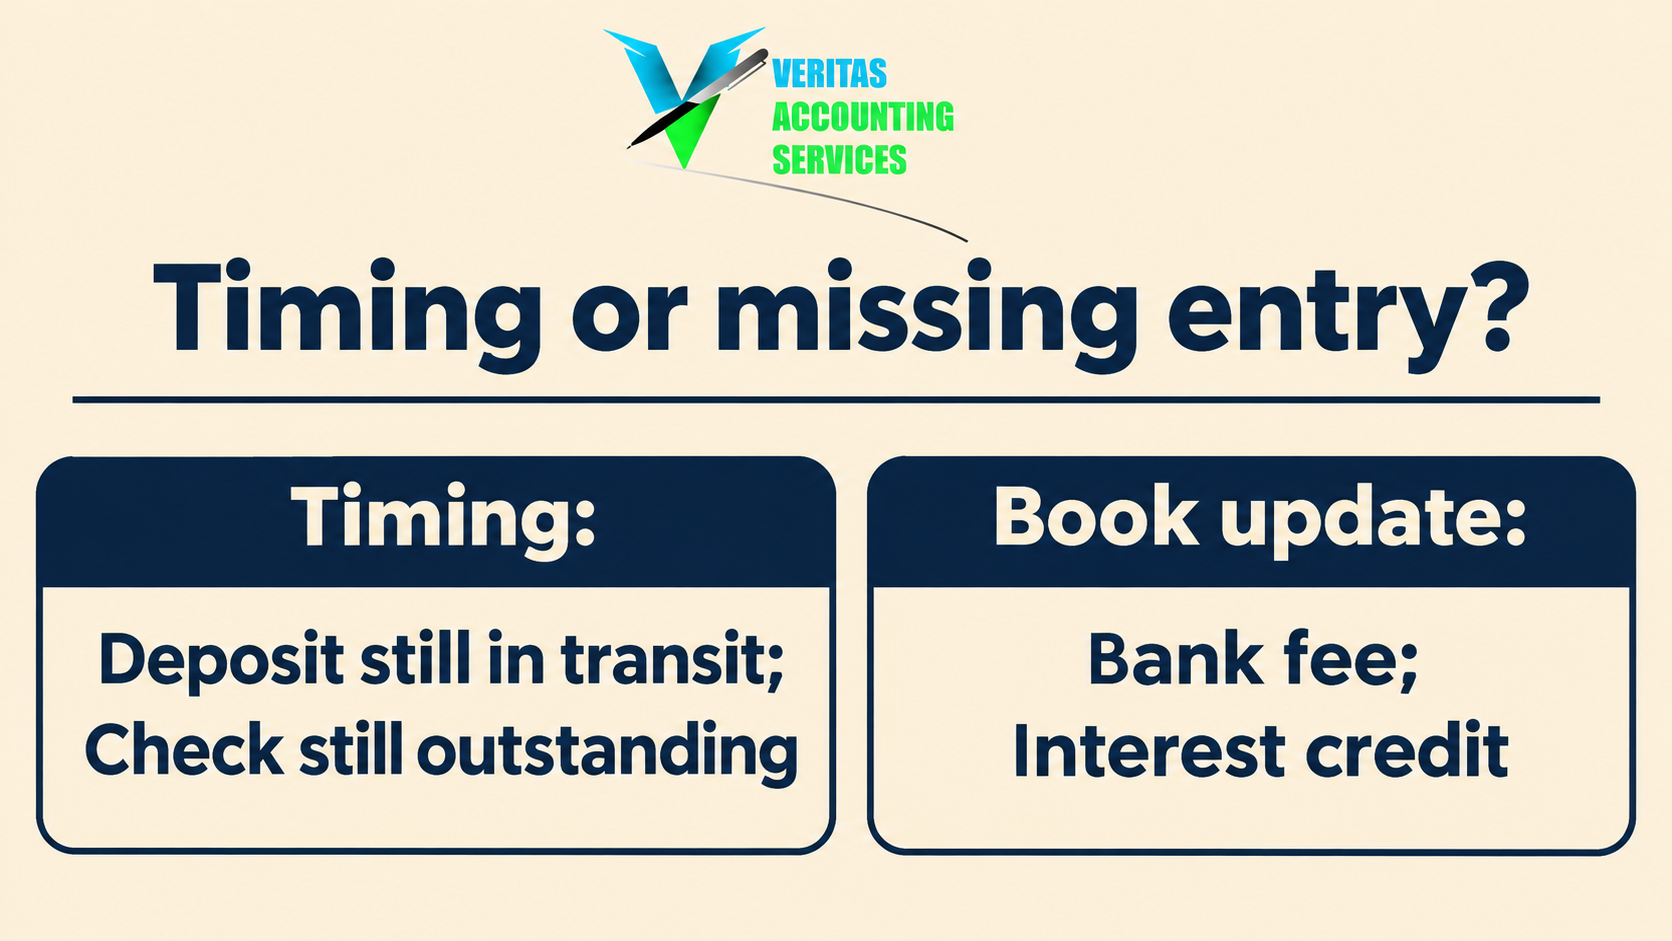
A bank reconciliation check separates deposits in transit and outstanding checks from book updates such as fees and interest.

Use the bank reconciliation check to test the cutoff

Try a specific cutoff test for any large item close to month-end. Look at when the business recorded it, when the bank posted it and which date the statement ends. Suppose the shop deposited a check at closing on October 31 and the bank posted the credit on November 2. If the deposit is already in the October books and you can verify it with the deposit record, the two dates explain the difference. Your November bank reconciliation check should show the deposit clearing without a second entry.

If the records disagree about the amount, the cutoff alone won’t explain the difference. A $1,200 deposit in the books and a $1,020 bank credit require a closer look at the deposit slip, what the bank accepted and whether part of the deposit was handled separately. Record what you learned before deciding whether a book correction or a bank inquiry is appropriate. If the original transaction is unclear, ask the person who handled the deposit while they can still recall what happened.

Work through the two balances

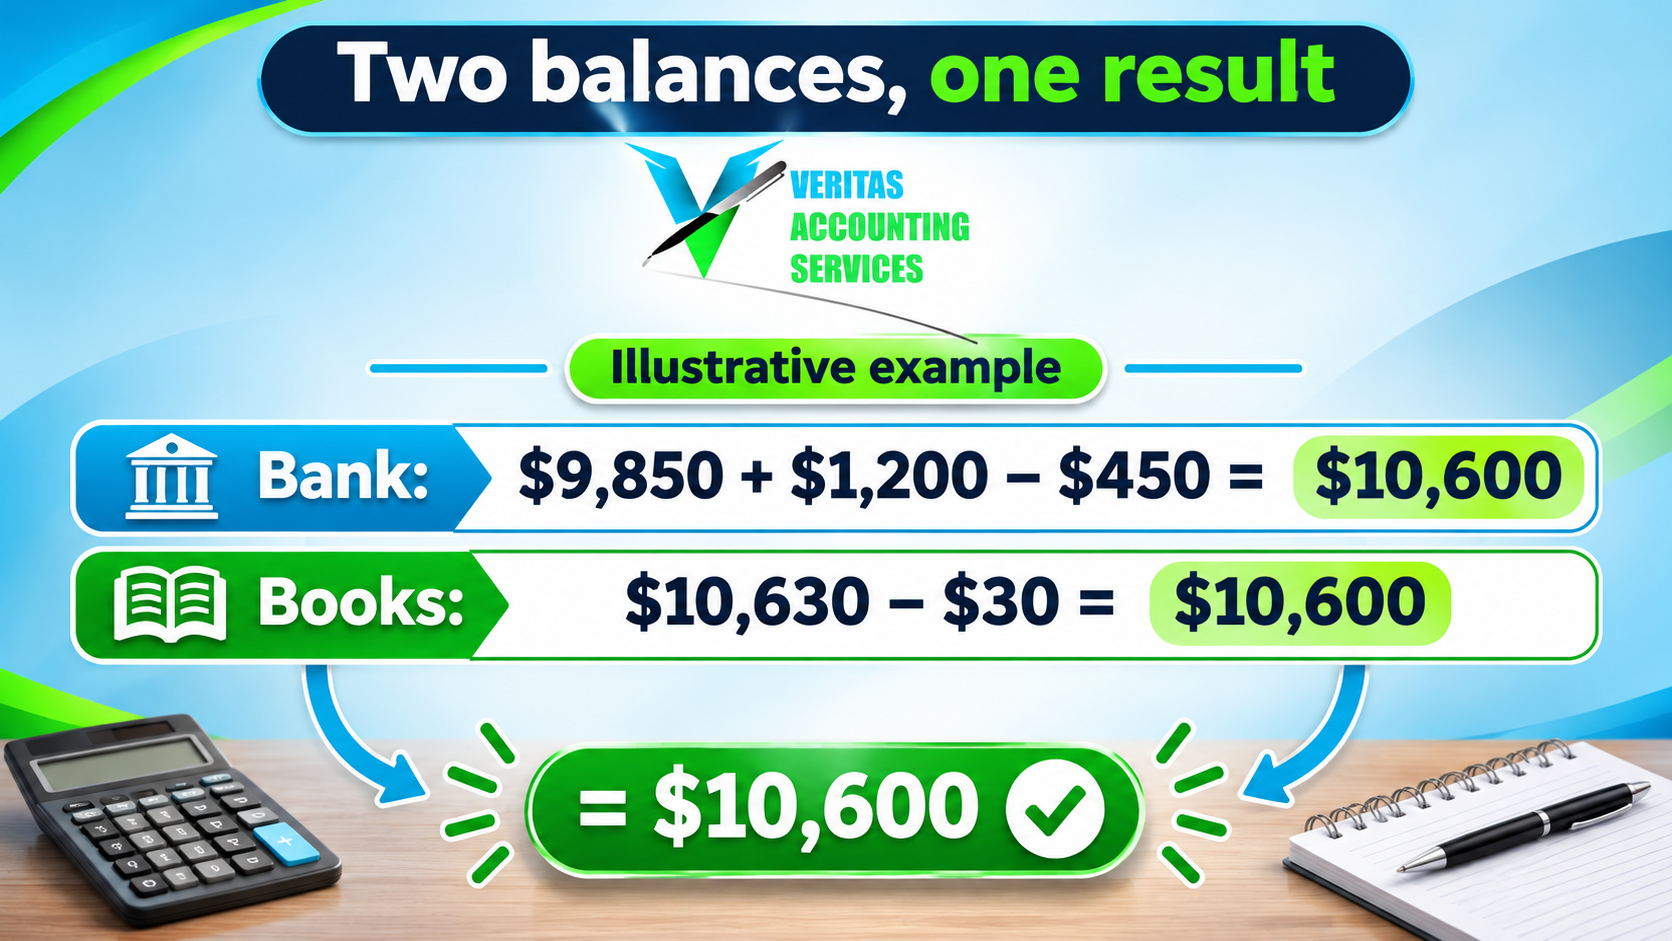
Here is the shop’s bank reconciliation check for the fictional month. The $1,200 deposit was recorded before the statement closed and appeared at the bank afterward. A $450 supplier check was recorded but had yet to clear. The bank also deducted a $30 fee that the shop hadn’t entered.

SideStarting balanceAdjustmentsAdjusted balance
Bank statement$9,850Add $1,200 deposit in transit and subtract $450 outstanding check$10,600
Books$10,630Subtract $30 bank fee$10,600
Worked example shows the adjusted bank and book balances both reaching $10,600.

On the bank side, $9,850 plus $1,200 equals $11,050. Subtracting $450 gives $10,600. On the book side, $10,630 minus the $30 fee gives the same $10,600. The fee is the bookkeeping change in this example. The deposit and check stay on the timing list until they clear. Keep the two sides visible so the reviewer can see why each adjustment was made.

The starting difference was $780. That number by itself gives the owner little information. The bank reconciliation check breaks it into items with different next steps. The shop needs to enter the fee, confirm the deposit posted and monitor the check. It can assign those steps separately and avoid changing entries for transactions already recorded.

Use the bank reconciliation check in cash planning

The $10,600 adjusted amount explains the statement-date balance after considering the listed items. To decide whether to pay a supplier today, also look at the bank’s current available funds, holds, payments still in transit and upcoming commitments. A deposit in transit might help explain the books even if you can’t spend it today. Review payroll and rent before deciding how much cash you can commit. A bank reconciliation check and a cash forecast answer related questions at different points in time. Veritas cash flow management guide

For example, if the owner schedules a supplier payment based on the adjusted month-end figure alone, a pending withdrawal could reduce the money available for the batch. Check which transactions already affect the available balance so you don’t subtract them twice. Then bring the reconciled records into your next payment review and confirm any new bills or bank activity since month-end. Veritas vendor payment review

Review open items before closing

A bank reconciliation check can balance while legitimate timing items remain open. Give each item a date, reference, amount and expected clearing date or next step. Review older items before carrying them forward. An old deposit may signal that you need to locate a receipt or talk to your bank. An uncleared check may require contact with the payee. Document what happened before taking corrective action. If an old amount needs to be reversed, confirm with your bookkeeper how to handle it and keep the original record traceable.

Save the statement, reconciliation report and supporting notes in a folder for the account and month. Include links or references for deposits in transit, payment confirmations and corrections. The IRS business recordkeeping overview explains how records support financial statements and items reported on tax returns. A saved bank reconciliation check makes it easier to explain what was known when the month was closed. Veritas guide to common bookkeeping problems
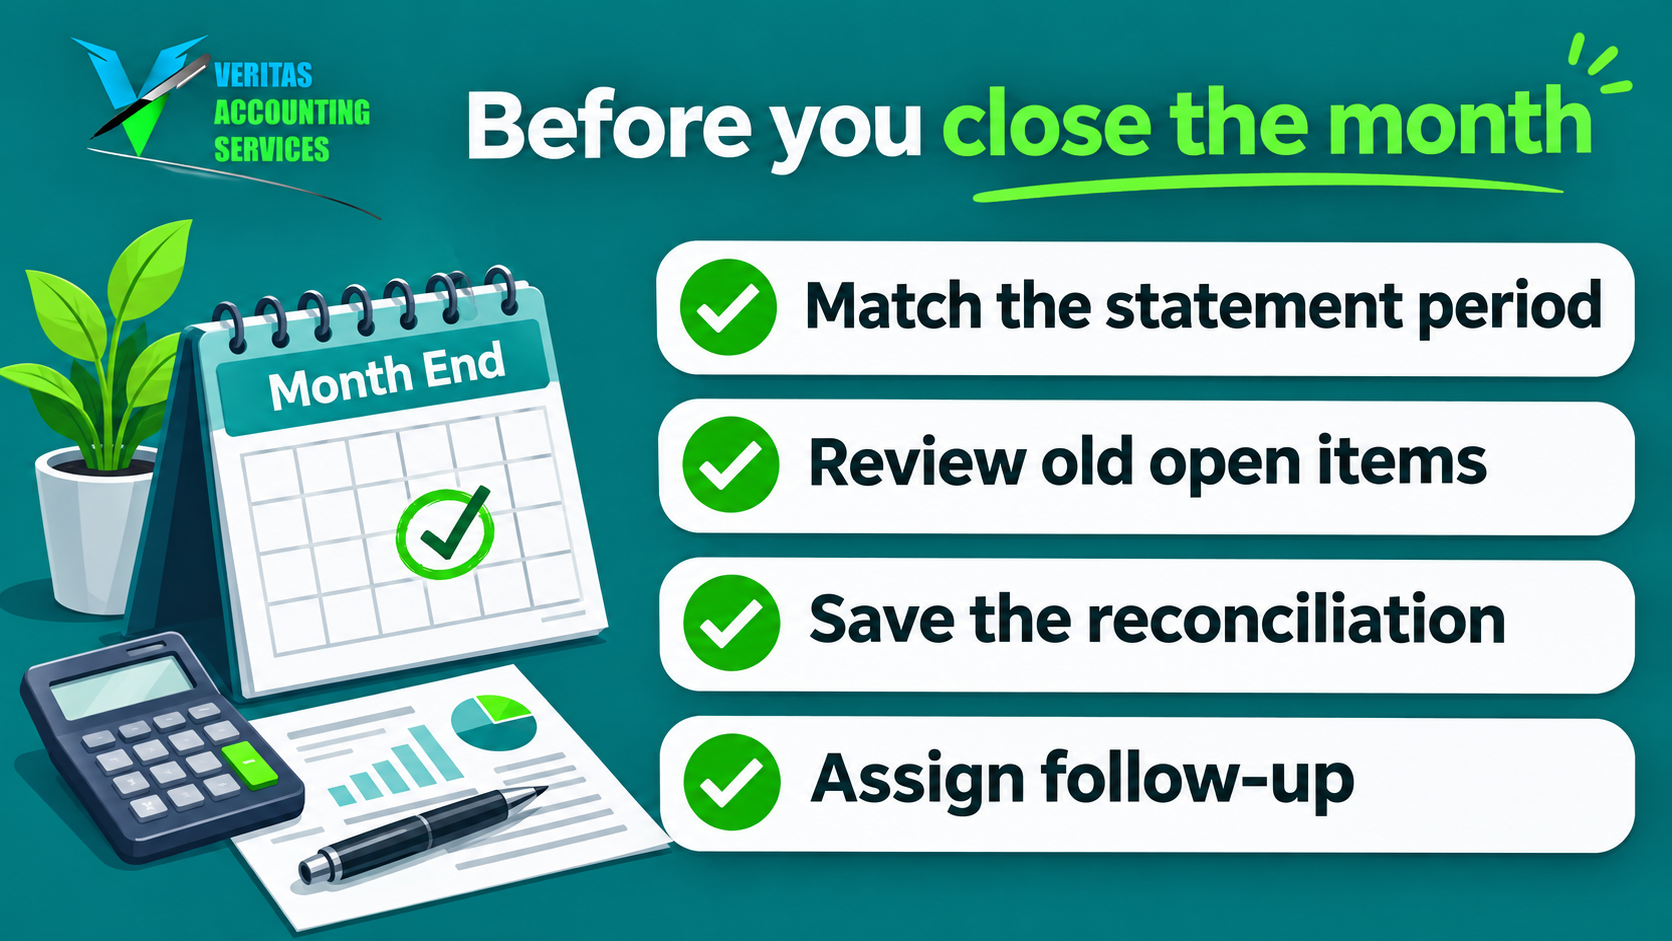
Month-end checklist covers statement period, old open items, saving the reconciliation and assigning follow-up.

If you work alone, do a second pass focused on unfamiliar payments, duplicate amounts and older open items. If two people share the work, have one prepare the reconciliation and the other review adjustments and evidence where practical. Give the reviewer enough context to tell a timing difference from an actual correction. A short note such as “$450 check issued October 28, supplier confirmed receipt November 4, still open as of review” is more useful than “check pending.”

Track what happens after the statement date

Use a separate follow-up date for each open item. For the flower shop, a deposit should be easy to find once it posts, so the owner can check the next day’s bank activity and note the actual clearing date. The supplier check may take longer. The owner can first confirm delivery, then look for it on the next statement. Record those outcomes against the original items so the next bank reconciliation check shows what changed.

If you correct a ledger entry, save the reason, the original reference and the revised record. For instance, if the $30 fee was entered after the first review, run the book balance again before marking the month complete. This final bank reconciliation check catches a correction posted to the wrong bank account or the wrong date. The reviewer can then see both the original issue and the evidence that it was resolved.

Hand off the bank reconciliation check

Keep a standard folder structure and pick a regular review date. Set one person to retrieve statements and payout reports, one person to prepare or review the bank reconciliation check, and a backup who knows where the files are. A concise handoff should show the period, adjusted balance, unresolved items, and who needs to answer each question. Include the next check date if you need to wait for a statement or a supplier response.

When the same mismatch keeps returning, look at how the transaction first enters the system. If every processor payout needs manual reconstruction, save the batch report when the payout arrives. If transfers repeatedly show up as expenses, agree on a matching method and check both accounts together. If deposits routinely lack support, make it part of closing the shop to save the deposit confirmation with the day’s receipts. Use each bank reconciliation check to identify a recurring cause you can address upstream.

Frequently asked questions

Can I rely on a bank feed instead of doing a bank reconciliation check?

A bank feed can help import and match transactions. Compare the result with the bank statement for the actual period and confirm the statement ending balance. Feed activity can miss an item, show it late or suggest the wrong match. Review exceptions, confirm transfers and keep the statement with the final reconciliation. That gives you a clear record of what you checked even if you change bookkeeping systems later.

What if my bank reconciliation check is off by a small amount?

Start with the amount and date. Look for a fee, rounding, a partial payment or a transaction recorded with the digits in the wrong order. Verify against the underlying record before correcting anything. If you still can’t explain it, record the difference as unresolved and ask your bookkeeper how to proceed. A small difference can point to a repeatable issue, such as the way fees are being recorded.

Do I have to wait for every check to clear before closing?

You can document a verified outstanding check on the reconciliation and follow up afterward. Keep the amount and payee visible, and confirm how it clears in the next bank reconciliation check. If the check appears lost, stale or disputed, check the facts with the payee and bank before sending a replacement. Once resolved, document which payment actually settled the obligation.

How often should I run a bank reconciliation check?

Monthly is a practical starting point for many small businesses because a regular statement provides a cutoff. If your business has frequent deposits or a tight cash position, you can also match activity weekly and use the month-end statement to finish the formal review. Choose a routine that fits the volume and gives someone enough time to investigate exceptions before records are used for decisions.

Conclusion

A bank reconciliation check works best when every difference has a reason and a next action. Start with the same statement date, match transactions, and separate delayed bank activity from missing book entries. Compare both adjusted balances, then save the evidence and assign follow-up on the items that are still open. The result gives you a clearer record of the month and a more reliable starting point for cash planning.

GET IN TOUCH

Schedule a FREE Call

Contact us

Connect on our Socials!

A hardware shop owner checks a delivery invoice at the receiving counter beside the headline Pay vendor bills with a plan.

Vendor Bills and a Simple Routine for Better Cash Planning

A vendor payment review gives a small business owner one place to answer a deceptively simple question: which bills should leave the bank this week? The answer takes more than opening the latest supplier emails. Some invoices are already paid, some are due before your next review, and some need a delivery check or a credit before you send money. Meanwhile, a healthy bank balance on Monday can look very different after payroll on Wednesday.

You can build a weekly routine around five checks: collect the bills, verify what you owe, sort the list, test the batch against available cash and match each payment afterward. The goal is to know what is due, who owns each exception and what cash remains after the run. The examples below use a fictional US hardware shop, but the routine also works for a service business that buys materials or pays subcontractors.

Table of contents

Collect the bills in one place

Start the vendor payment review with a complete list. Give suppliers a single billing address or portal and have anyone who receives a bill elsewhere route it there. Decide who checks that inbox when the usual person is out. If a supplier emails a bill and later mails a paper copy, attach the copy to the existing record so the second arrival doesn’t become a second payable.

For each bill, capture the vendor, invoice number, invoice date, due date, amount, open balance and the person who can confirm the purchase. Include a status that tells the next person what to do: awaiting receipt, ready to approve, approved, scheduled, paid or disputed. If you rely on a spreadsheet, give each row a link or file reference to the actual bill and keep one shared working copy. If you use bookkeeping software, check whether a bill is already in the system before entering it from email.

An open bill list is only as complete as your intake process. Add a short check for recurring bills expected before the next run, such as a lease or a regular supplier delivery. If you expect a bill and can’t find it, put the expected amount in your cash forecast as an estimate and assign someone to request the invoice. Keep the forecast entry distinguishable from an approved bill. This makes the missing invoice visible without turning an estimate into permission to pay it.

Keep the invoice with its supporting documents as you go. The IRS guide to business records explains how supporting records identify the business expense and document payment. Your vendor payment review can make those records easier to find later by linking them to the bill while the people who received the goods still remember the details. For more on making this habit part of ordinary bookkeeping, see why good tax records start with good bookkeeping.

Verify what you owe

Before a bill joins the vendor payment review batch, compare what the supplier billed with what you ordered and what arrived. A hardware shop could match the invoice to a purchase order and the signed receiving slip. A service business might match it to a statement of work and a manager’s confirmation that a milestone was delivered. Smaller purchases may have fewer documents, but someone should still be able to explain what was bought and confirm that the amount is right.

For example, suppose the shop ordered 20 boxes of fasteners and received 18. The invoice lists 20. Ask the supplier whether the other two boxes are on the way or whether it will issue a corrected bill or credit. Record the reason for the hold, who contacted the supplier and when to follow up. If you and the supplier agree to pay the undisputed amount first, record that agreement and keep the remaining amount visible until it is resolved. Don’t silently clear the entire balance when a partial payment goes out.

Check the supplier statement for credits and prior payments as well. The statement helps you identify what the supplier thinks is open. Your records can reveal a payment in transit, a credit they haven’t applied or a missing invoice. Follow up on the mismatch with supporting documents. If the vendor payment review leaves someone responsible for the follow-up and gives them a date, the same unresolved item is less likely to show up week after week without explanation.

Treat a request to change the payee or bank details as a separate exception. Use a phone number or contact you already trust to confirm the change independently. If possible, have another person review the change and the first payment. A familiar logo and email signature do not verify the destination. The FBI’s business email compromise guidance specifically recommends verifying changes to payment procedures or account numbers. A routine bill can stay open while you confirm where the money should go.

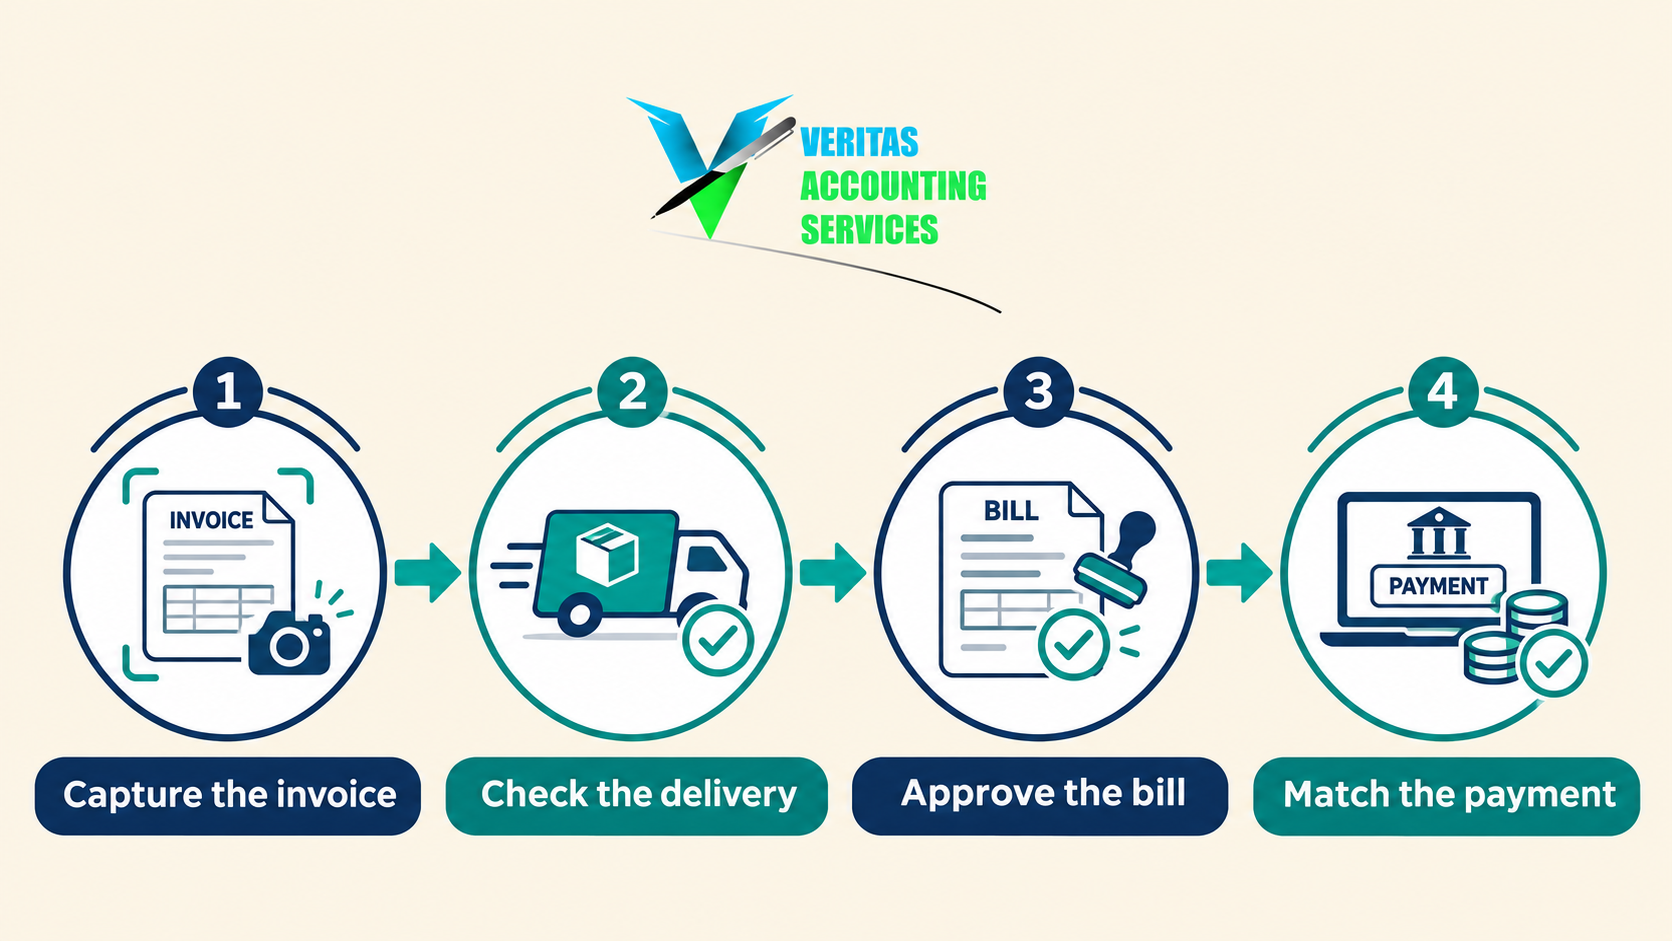
A vendor payment review diagram shows invoice capture, delivery check, bill approval and payment matching.

Sort the vendor payment review

Build your list around due dates and the next payment run. A bill due next Tuesday may belong in Friday’s run if you only pay on Fridays. Consider how long each payment method takes and whether your terms require the vendor to receive payment by the due date. Leave time for weekends, holidays and the approval process. Keep a separate exception list so that a disputed bill or suspicious account change doesn’t accidentally enter the approved batch.

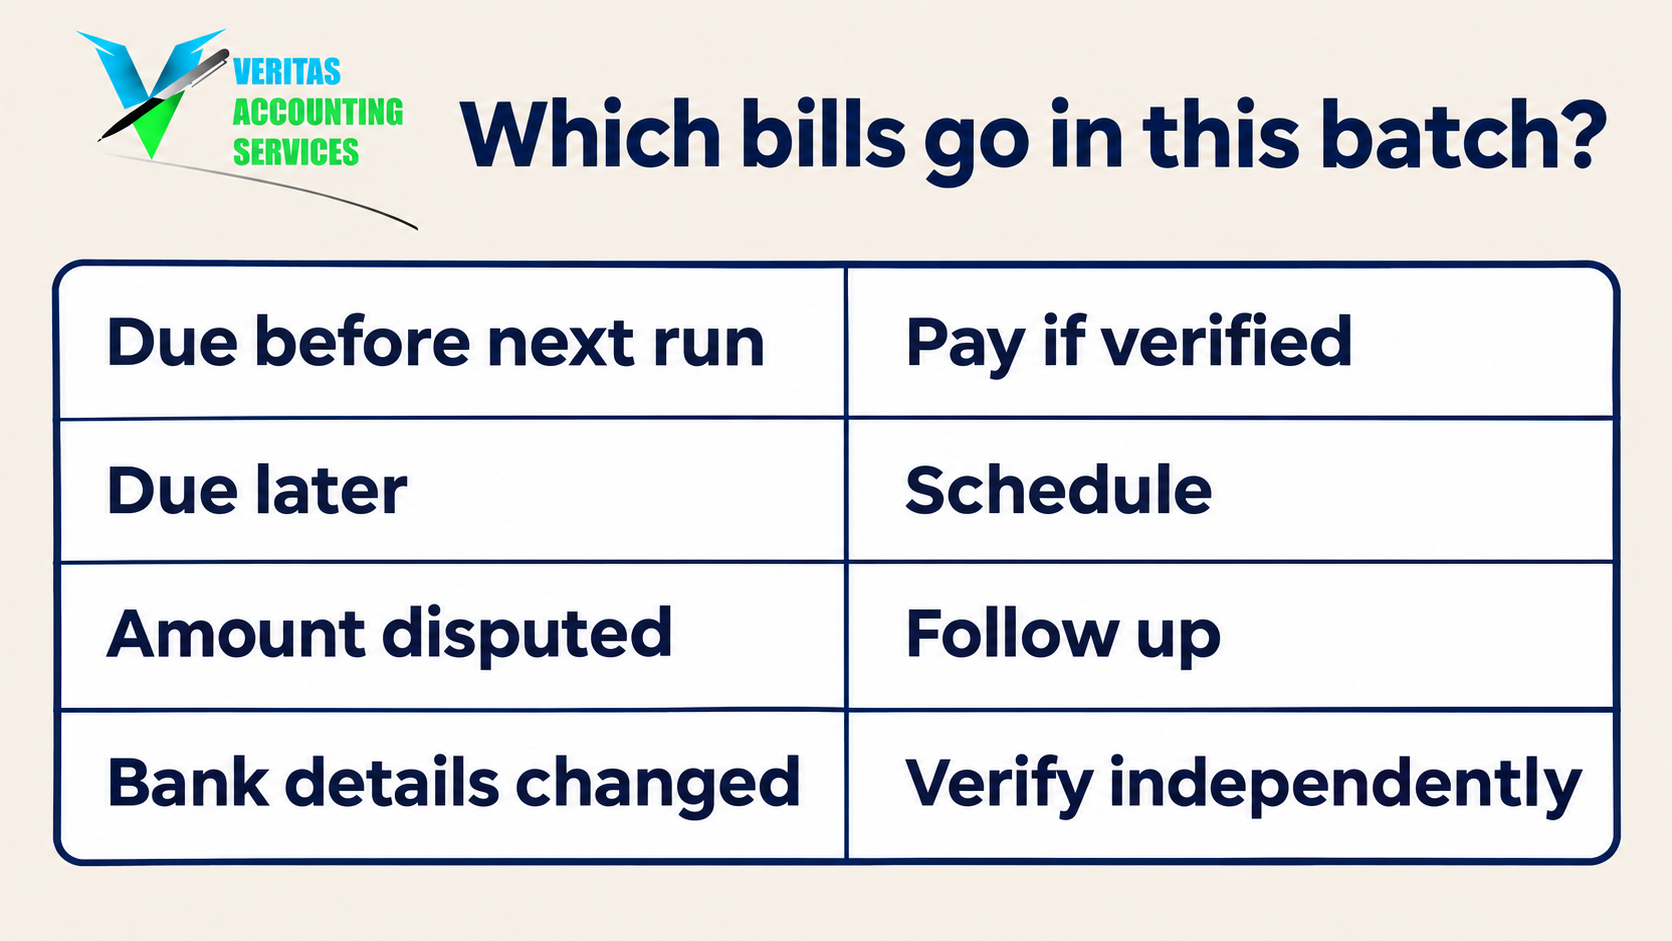
A simple way to organize a vendor payment review is to give every open item one next action:

What you seeWhat to do
Due before the next runPay in this batch if verified, approved and funded.
Due after the next runSchedule the bill and confirm the next review date.
Amount or delivery disputedDocument the issue and follow up with the vendor.
Payment details changedVerify the destination independently before release.

An overdue balance deserves a look, even if you can’t pay it today. First check whether it is genuinely unpaid or simply unmatched. If it’s unpaid and you need more time, contact the supplier early, propose a specific plan and document any agreement. Record the amount and date promised so the next vendor payment review reflects what you told the supplier. Don’t assume that changing a due date in your books changes the contract.

There may be trade-offs among bills that are all due soon. One supplier could provide the materials you need to finish a customer job. Another might offer an early payment discount. A practical vendor payment review records the reason for each decision and considers the cost of postponement, the supplier relationship and the effect on near-term cash. Treat an early payment discount as an option to evaluate. Check the actual terms, how much cash the early payment uses and whether that leaves enough for commitments that arrive first.

If the list seems to change every time you open it, separate status from payment date. For example, a verified $700 invoice can be approved today and scheduled for next Thursday. A $500 invoice with a quantity dispute stays on hold, with its original due date visible and a separate follow-up date. Keeping those dates distinct helps you explain to a teammate why two invoices due on the same day are moving through the vendor payment review differently.

A table sorts bills due soon, bills due later, disputes and changed bank details into their next actions.

Test the batch against available cash

A vendor payment review needs a cash check before you release the batch. Start with cash you can actually use and look ahead to the next scheduled review. Account for pending withdrawals, payroll, rent and other commitments that fall in that window. Check whether pending withdrawals already affect the balance you’re using so you don’t subtract them twice. Treat expected deposits separately and ask what happens if a large receipt arrives a few days late. The SBA guide to managing business finances discusses using financial information to manage cash flow. For a broader view, see Veritas’s guide to cash flow management.

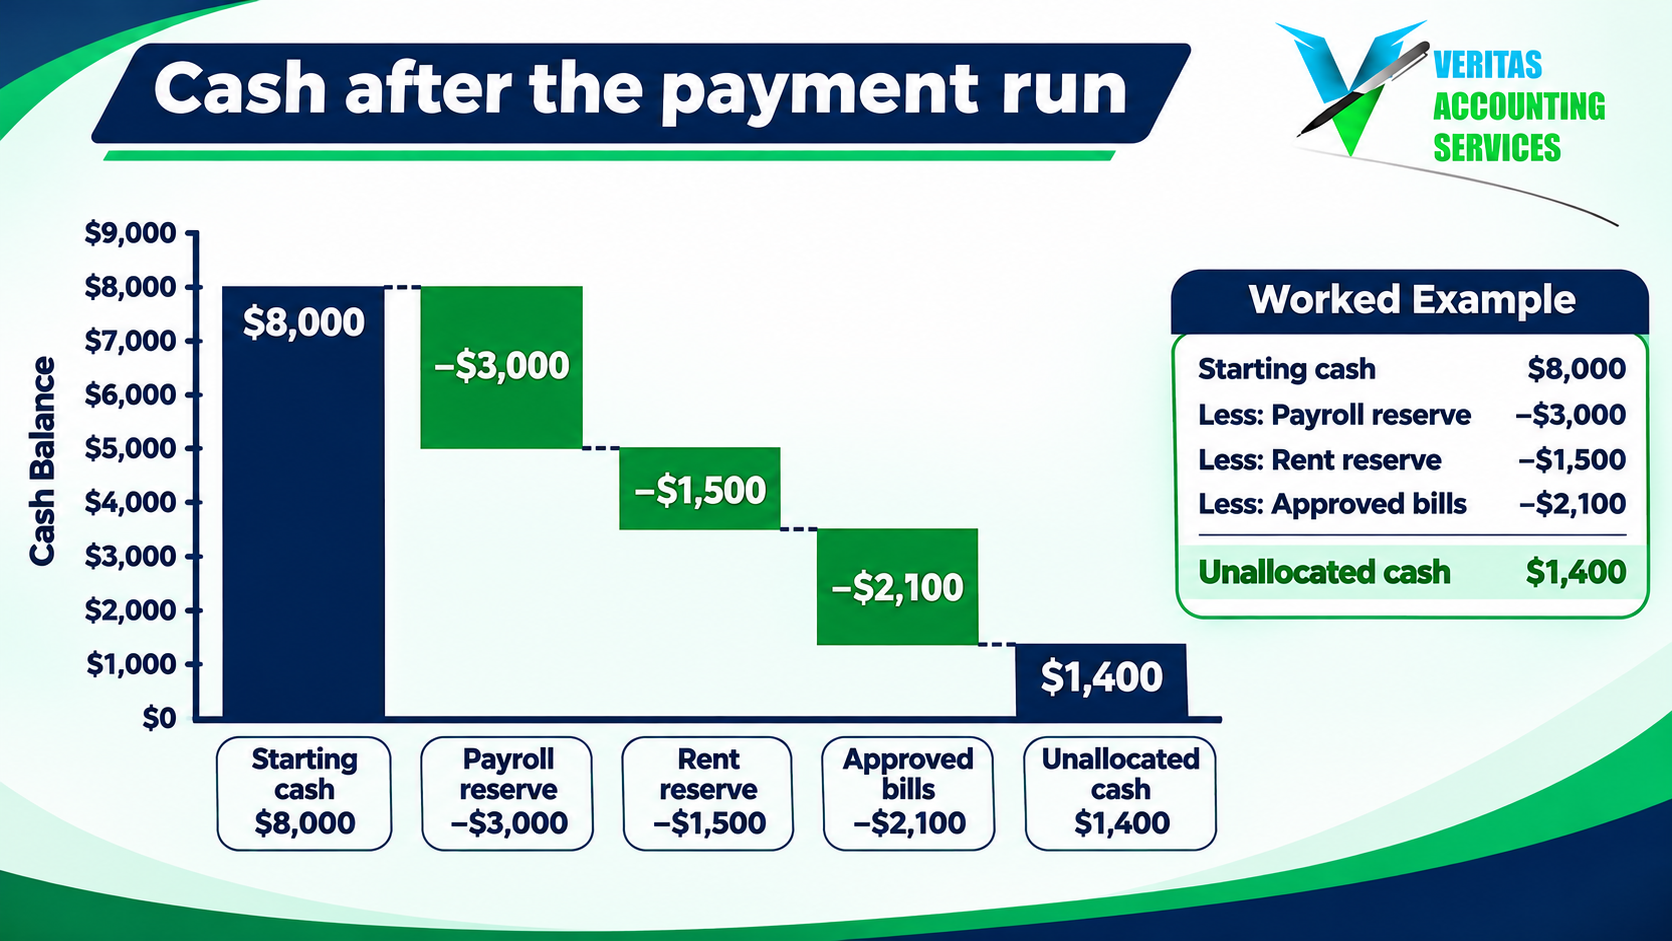
Suppose the hardware shop has $8,000 of usable cash on Monday. Before the next review, it plans to reserve $3,000 for payroll and $1,500 for rent. The verified bills in this run total $2,100. It has $1,400 left unallocated after setting aside those amounts. That figure is a planning balance for the commitments shown. If a $900 utility payment was omitted, the revised balance would be $500. If the owner requires a $1,000 buffer, the batch as shown meets it, but the revised plan with utilities falls short by $500.

A fictional cash example subtracts $3,000 payroll, $1,500 rent and $2,100 approved bills from $8,000, leaving $1,400 unallocated.

Give the owner an actionable cash decision

Use the vendor payment review to show both the amounts and the timing. The shop might expect a $2,400 customer receipt later in the week. Show the plan with that receipt arriving on time and with it arriving late. If the batch only works with money that hasn’t arrived, the owner needs to decide whether to wait for cleared funds, ask a supplier for agreed terms or change the batch. Make those decisions before releasing payments and check what each one means for the actual due date and delivery schedule.

Also distinguish a current cash forecast from an accounting report. The open bills list answers what you owe and when it falls due. A cash forecast also includes expected receipts and commitments that may not appear as vendor bills. A profit report answers a different question about business performance for a period. The vendor payment review brings the first two views together for a particular decision. It won’t explain every reason why cash and profit differ. The Veritas article on tax savings and cash flow explores another example of why a cash decision needs its own analysis.

For the first few runs, write down what surprised you. Maybe freight invoices normally arrive after the goods, or a payment platform deducts a recurring fee on a different date from the invoice. Add a reminder for predictable omissions and keep one owner for each uncertain item. A reliable vendor payment review becomes easier to run once you’ve resolved the recurring causes of last-minute changes.

Match payments and close the loop

Before releasing a batch, have the approver review the actual payees, amounts and dates against the approved list. If one person runs the business alone, take a separate pass after preparation and check the final bank screen against the list before submitting. Make sure a bill marked scheduled hasn’t already been set up in the bank portal. Save the payment confirmation and record which invoices the payment covers. When one transfer pays several invoices, the reference should make it possible to trace each invoice to its share of that transfer.

After release, use the next vendor payment review to check which transactions cleared. Match a bank-feed payment to the existing bill payment in your bookkeeping system when appropriate. Creating a new expense from an imported withdrawal after the bill and its payment have already been recorded can double count the cost. Follow up on returned transfers and uncleared checks, keep their status clear and check with your bank or supplier before issuing a replacement. The IRS guide to starting a business and keeping records discusses supporting documents and bank reconciliation. Veritas also covers the problems that build up when bookkeeping falls behind.

Give exceptions their own short handoff. A useful line might read: “Invoice 1843, missing two boxes, Taylor to contact supplier Monday, review again Tuesday.” If the supplier confirms a credit, link the confirmation to the original bill and check how the credit is applied in the books. If a payment failed, keep a record of both the original attempt and the corrected payment. The next person should be able to tell which amount remains open without reading an entire email thread.

Make the vendor payment review easy to hand over

Set a recurring time for the vendor payment review and designate a backup. A lean routine can start with a brief meeting or an approval note that shows cash available, proposed payments, exceptions and decisions needed. Give the owner a batch total and enough detail to understand any unusual payment. The person checking the list should know who approves a new vendor, how to confirm changed instructions and where to find the confirmation afterward.

At month-end, compare open bills and major supplier statements, and look for old deposits, unapplied credits, repeat invoice numbers and balances that seem out of date. The vendor payment review handles the weekly decisions; a month-end look can uncover older items that never make it into the current run. If the cleanup gets complicated, bring the invoice, statement and bank record together before making adjustments. That’s more useful to your bookkeeper than an instruction to clear all old balances.

When you start, keep a short record of what you changed in each vendor payment review. For example, an owner might move the normal run from Friday to Thursday after learning that a supplier needs a full business day for processing. Update the schedule, tell the backup and keep the old confirmation available for matching. If the vendor payment review still generates repeated urgent requests, sort them by cause. Missing invoices call for better intake, while late approvals may call for a clearer cutoff. A single adjustment based on a recurring cause can save more effort than adding another sign-off to every routine bill.

Frequently asked questions

Do I need accounting software for a vendor payment review?

You can start with a shared list if it captures the bill, open balance, due date, approval and payment reference. Decide who edits it and where the supporting documents live. As invoice volume or the number of approvers grows, software can make it easier to control access, track changes and match payments. Keep a process for reviewing what the software imports or suggests.

How should a vendor payment review handle possible duplicates?

Search the supplier name, invoice number and amount, and check your payment history before entering or paying it. Differences in formatting can hide duplicates, such as a leading zero in the invoice number. Conversely, recurring bills can have the same amount and still be separate obligations. Check the service dates and documents. Mark a potential duplicate for investigation so the vendor payment review doesn’t silently drop a legitimate bill or pay the same obligation twice.

Should I track unpaid bills if I use cash basis bookkeeping?

An owner can keep an operational list of bills due even when payments drive the timing of many entries under the business’s accounting method. The list supports scheduling and cash planning. Ask your bookkeeper how to enter and report those bills in your system so that your management list and financial or tax reports are used for the right purpose. The vendor payment review itself does not determine whether or when an item is deductible.

How often should I do a vendor payment review?

Weekly is a starting point if it gives you enough time to meet your terms and review approvals. A business with daily replenishment, tight cash or frequent urgent purchases may need a shorter cycle. Keep a clear exception process for bills that can’t wait, and apply the same verification and approval steps to those payments. A payment outside the normal run should still appear in your records before the next person prepares a batch.

Conclusion

A vendor payment review works when every bill has an owner, a status and a next action. Start with the bills due before the next run. Confirm what you received, resolve mismatches, set aside cash for other commitments and check the final payment details. After the batch goes out, keep the confirmations and match the transactions as they clear. This gives the owner a clear view of which suppliers have been paid, what remains open and how much cash is available for the next decision.

GET IN TOUCH

Schedule a FREE Call

Contact us

Connect on our Socials!