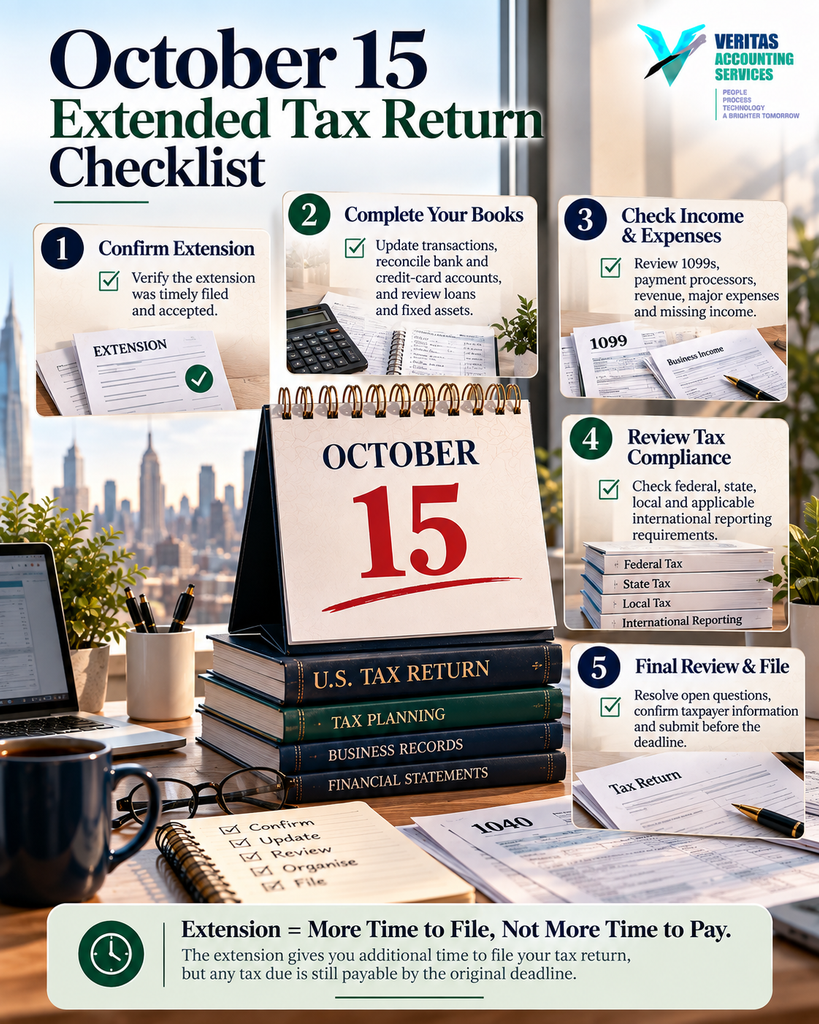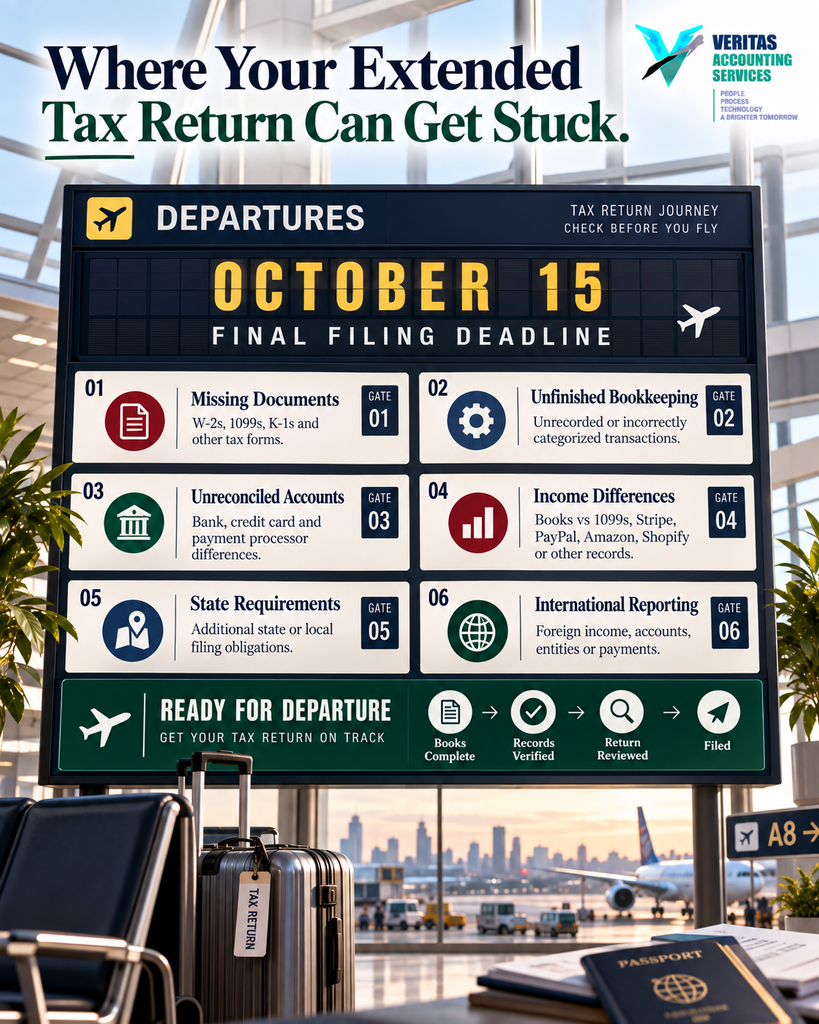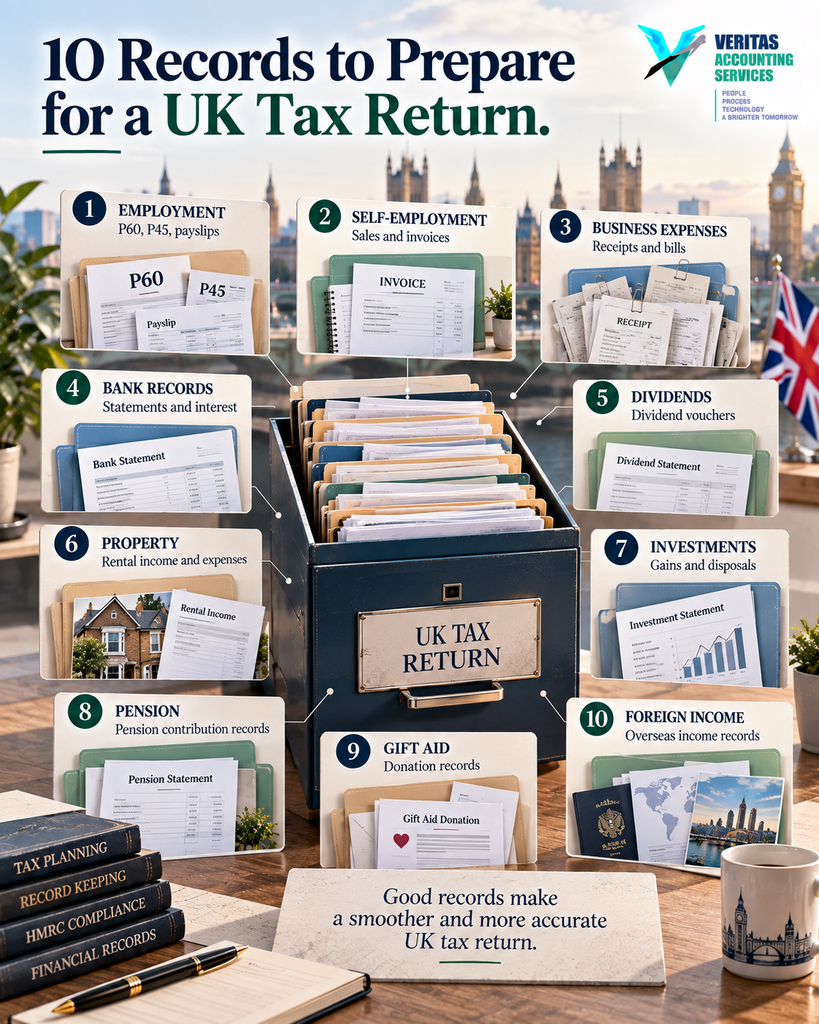

Tax preparation is often treated as a once-a-year activity. A business owner gathers receipts, downloads tax forms, sends everything to the accountant and expects the tax return to come together.
In reality, a good tax return usually starts months before tax season.
It starts with the quality of the bookkeeping.
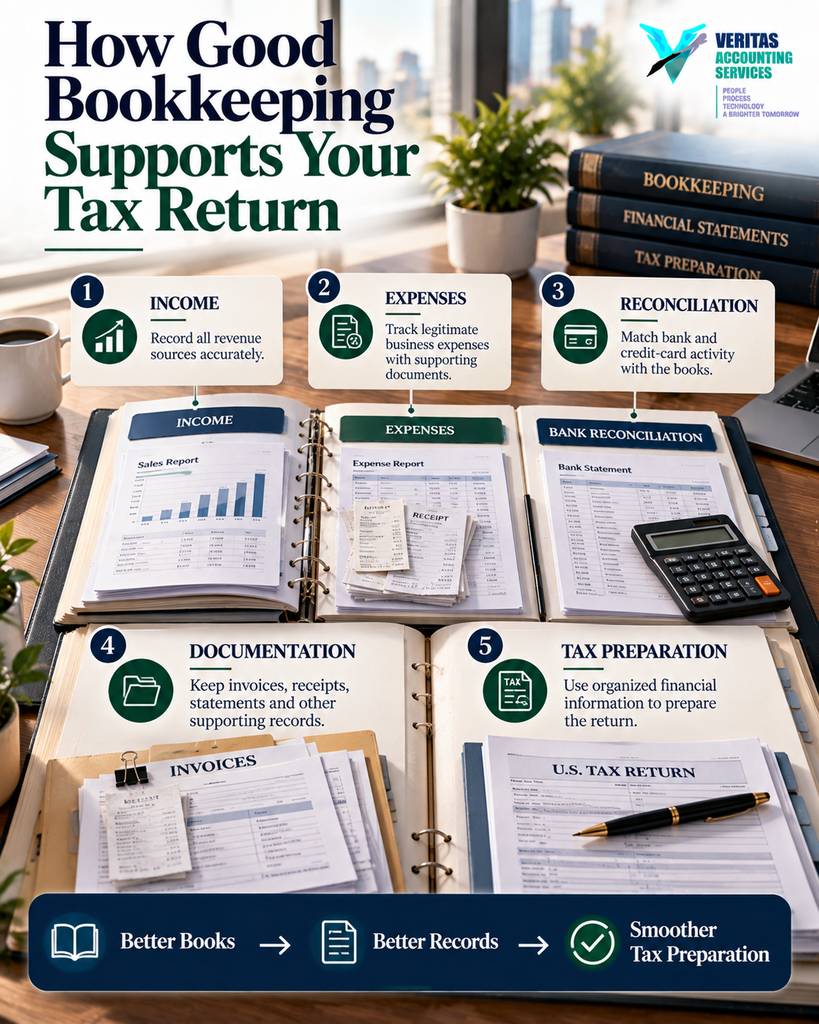
When income is recorded correctly, expenses are properly classified, bank accounts are reconciled and supporting documents are organized throughout the year, tax preparation becomes much more straightforward. When the books are incomplete or inconsistent, tax preparation can turn into a time-consuming cleanup exercise.
The IRS states that good business records help taxpayers monitor their business, prepare financial statements, identify income, track deductible expenses, prepare tax returns and support the items reported on those returns.
That is why bookkeeping should not be viewed simply as an administrative task. It is part of the foundation of tax compliance and financial management.
Table of Contents
- Why Bookkeeping and Tax Records Are Connected
- Accurate Income Starts With Accurate Books
- Expense Tracking Makes Tax Preparation Easier
- Bank Reconciliation Catches Problems Early
- Proper Classification Matters
- Supporting Documents Strengthen Your Records
- Good Bookkeeping Helps With Year-End Tax Planning
- Balance Sheet Accounts Matter Too
- What Happens When Bookkeeping Is Poor
- A Simple Monthly Bookkeeping Process
- What Business Owners Should Review Before Tax Filing
- Frequently Asked Questions
- Final Thoughts
Why Bookkeeping and Tax Records Are Connected
Your tax return does not exist separately from your accounting records.
For a business, the tax preparer needs reliable information about revenue, expenses, assets, liabilities and other transactions to prepare an accurate return.
The IRS does not prescribe one particular bookkeeping system for every business. Instead, businesses can generally choose a system appropriate for their operations as long as it clearly and accurately reflects income and expenses.
That could mean accounting software, spreadsheets or another organized recordkeeping system.
The important point is not the software itself.
It is whether the underlying records are complete, accurate and supported.
Good bookkeeping creates a structured record of what happened during the year. Tax preparation then becomes the process of using those records to determine the appropriate tax reporting.
Poor bookkeeping reverses that process.
The tax preparer first has to figure out what actually happened before the return can be prepared.
Accurate Income Starts With Accurate Books
One of the most important purposes of bookkeeping is making sure business income is complete.
A business may receive money through multiple channels:
- Business bank accounts
- Credit cards
- ACH payments
- Checks
- Stripe or PayPal
- Shopify or Amazon
- Payment processors
- Cash
- Other platforms
If only the main bank account is reviewed, some income can potentially be missed or duplicated.
The IRS recommends maintaining records that identify the source and amount of gross receipts. Supporting records can include invoices, bank deposits, receipt records and applicable information returns such as Forms 1099-NEC and 1099-K.
Good bookkeeping brings these different sources together.
For example, if a business records $500,000 of revenue in its accounting system but its payment processor reports $520,000 of gross transactions, that difference should not simply be ignored.
There may be legitimate explanations.
Refunds, processing fees, timing differences, chargebacks and accounting methods can all create differences.
But the difference should be investigated before tax filing.
Expense Tracking Makes Tax Preparation Easier
The same principle applies to expenses.
Business owners make hundreds or thousands of payments during a year. If expenses are recorded months later, receipts can disappear, business purposes can be forgotten and transactions can become difficult to classify.
Good bookkeeping records expenses when they occur and connects them with appropriate supporting documentation.
The IRS notes that supporting documents for business expenses can include invoices, receipts, account statements, credit-card records and other evidence showing the amount and business nature of the expense.
This is particularly important for expenses that require additional documentation or judgment.
Examples may include:
- Travel
- Meals
- Vehicles
- Contractor payments
- Equipment
- Professional fees
- Advertising
- Software
- Insurance
- Business-use-of-home expenses
The goal is not to create as many deductions as possible.
The goal is to accurately identify legitimate business expenses and maintain records that support them.
Bank Reconciliation Catches Problems Early
Bank reconciliation is one of the most valuable bookkeeping procedures for tax preparation.
A bank balance in accounting software should not simply be assumed to be correct because it looks reasonable.
A proper reconciliation compares the accounting records with the actual financial institution statement and investigates differences.
This can identify:
- Missing transactions
- Duplicate transactions
- Incorrect amounts
- Outstanding checks
- Deposits in transit
- Incorrect transfers
- Personal transactions
- Bank fees that were never recorded
Suppose a business owner believes the books are complete because the accounting software shows a $75,000 bank balance.
After reconciliation, the actual bank statement shows $71,500.
That $3,500 difference may be caused by several transactions that were never recorded or incorrectly entered.
If the books are used to prepare the tax return without resolving that difference, the tax preparer may be working from incomplete information.
Good bookkeeping addresses these issues during the year rather than during the final days before tax filing.
Proper Classification Matters
Recording a transaction is only the first step.
It also needs to be classified appropriately.
For example, a $10,000 payment could potentially represent:
- An ordinary business expense
- Equipment
- A loan payment
- A shareholder or owner distribution
- A prepaid expense
- A security deposit
- A personal transaction
These transactions may have very different accounting and tax consequences.
A business owner may see money leaving the bank account and simply categorize it as an expense.
But not every cash outflow is an expense.
Loan principal, equipment purchases, owner distributions and certain prepaid costs may need different treatment.
Good bookkeeping helps create a cleaner distinction between income, expenses, assets, liabilities and equity.
That distinction becomes particularly important when the tax return is prepared.
Supporting Documents Strengthen Your Records
A number in an accounting system is not necessarily enough by itself.
Supporting documentation provides evidence for the underlying transaction.
The IRS identifies documents such as invoices, receipts, deposit slips, paid bills and canceled checks as examples of records that support entries in business books and tax returns.
For an equipment purchase, for example, the business may need to retain information about:
- Purchase date
- Purchase price
- Invoice
- Payment
- Business use
- Improvements
- Depreciation
- Section 179 deduction, if applicable
- Disposal information
Asset records are particularly important because they can affect depreciation during ownership and the calculation of gain or loss when the asset is sold.
The same principle applies to ordinary business expenses.
A well-organized bookkeeping system should make it possible to connect the transaction recorded in the books with the document supporting it.
Good Bookkeeping Helps With Year-End Tax Planning
Tax planning becomes much more useful when the underlying financial information is current.
Imagine a business owner waits until December to discover that the year-to-date profit is significantly higher than expected.
At that point, there may be fewer opportunities to evaluate legitimate planning strategies.
With updated bookkeeping, the business owner and tax professional can review financial performance throughout the year.
They can ask questions such as:
How much revenue has the business generated?
What are the major expense trends?
Are there unusual transactions?
Are estimated tax payments sufficient?
Are there equipment purchases being considered?
Are there significant changes in payroll?
Are there outstanding receivables?
Are there opportunities or issues that should be addressed before year-end?
Good bookkeeping therefore supports not only tax preparation but also tax planning.
Balance Sheet Accounts Matter Too
Many business owners focus almost entirely on the profit and loss statement.
That can be a mistake.
Tax and accounting information can also depend on balance sheet accounts.
Important areas may include:
- Accounts receivable
- Accounts payable
- Loans
- Fixed assets
- Accumulated depreciation
- Inventory
- Credit cards
- Payroll liabilities
- Sales tax liabilities
- Owner equity
- Intercompany balances
If these accounts are not reviewed regularly, errors can remain hidden.
For example, a loan balance may not agree with the lender’s statement. A fixed asset may have been expensed instead of capitalized. An old receivable may no longer be collectible. A credit-card balance may contain transactions from a previous period.
Good bookkeeping includes these accounts in the review process rather than focusing only on income and expenses.
What Happens When Bookkeeping Is Poor?
Poor bookkeeping does not automatically mean a business has violated tax rules.
But it can make accurate tax preparation significantly more difficult.
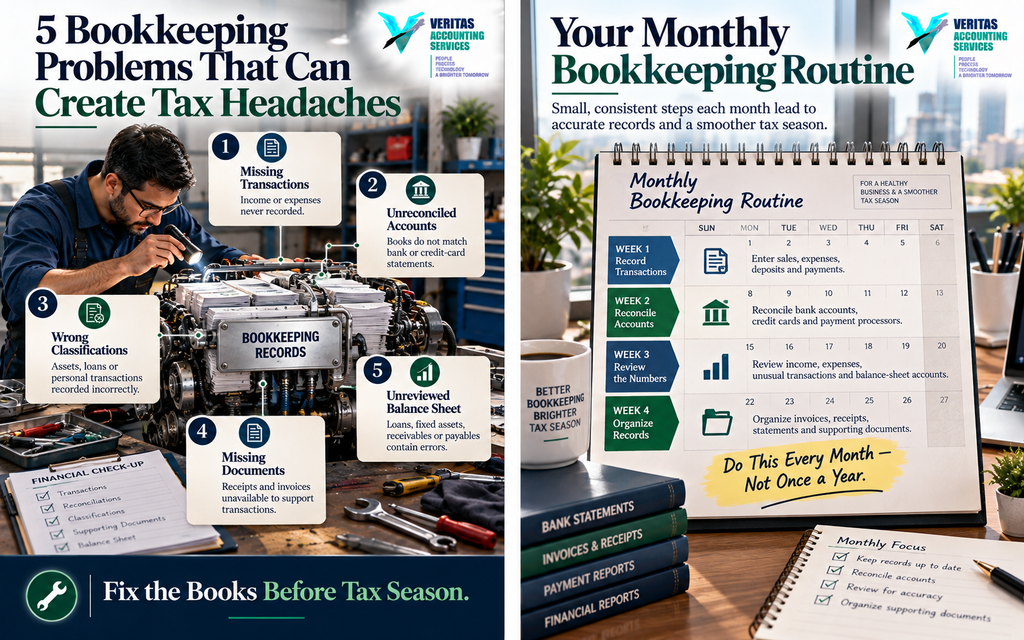
Common problems include:
Missing income
Some revenue sources may not be recorded or may be recorded twice.
Unsupported expenses
The business may know that money was spent but lack documentation showing what the payment was for.
Incorrect classifications
Capital purchases, loan payments and owner transactions may be incorrectly treated as expenses.
Unreconciled accounts
Bank and credit-card balances may not match the actual statements.
Year-end surprises
The business owner may not know the actual financial position until tax preparation begins.
More tax preparation time
The tax preparer may need to spend additional time investigating transactions and requesting documents.
Delayed filing
If significant bookkeeping issues are discovered late, preparing the tax return can take longer.
The underlying problem is often not the tax return itself.
It is the quality of the information feeding into the tax return.
A Simple Monthly Bookkeeping Process
Business owners do not need to wait until tax season to review their records.
A simple monthly process can make a significant difference.
Step 1: Record all transactions
Make sure income, expenses, transfers, deposits and payments have been entered.
Step 2: Reconcile bank accounts
Compare every business bank account with its corresponding statement.
Step 3: Reconcile credit cards
Make sure credit-card transactions and balances agree with the statements.
Step 4: Review income
Compare accounting revenue with invoices, payment processors and other relevant records.
Step 5: Review expenses
Look for unusual transactions, missing receipts and potentially incorrect classifications.
Step 6: Review balance sheet accounts
Check loans, fixed assets, accounts receivable, accounts payable and other significant balances.
Step 7: Save supporting documents
Organize invoices, receipts, statements and other records in a consistent system.
The IRS notes that electronic recordkeeping systems can be used as long as they meet the applicable recordkeeping principles and maintain complete and accurate records.
This monthly process is much easier than attempting to reconstruct an entire year at tax time.
What Business Owners Should Review Before Tax Filing
Before sending financial information to your tax preparer, review the following:
Income
Confirm that all revenue sources have been recorded and investigate differences with 1099s and payment processor reports.
Expenses
Review major expense categories and make sure significant transactions have appropriate documentation.
Bank and credit cards
Make sure all accounts are reconciled through year-end.
Fixed assets
Review equipment, vehicles, computers and other significant purchases.
Loans
Compare loan balances with lender statements and identify principal and interest appropriately.
Payroll
Confirm payroll reports and tax filings are complete and consistent with the books.
Owner transactions
Review personal expenses, distributions, contributions and other owner-related transactions.
Inventory
If applicable, review inventory balances and year-end counts.
Supporting documents
Make sure invoices, receipts, statements and other important documents are available.
This does not replace professional tax review, but it gives the tax preparer a much stronger starting point.
Frequently Asked Questions
Is bookkeeping the same as tax preparation?
No. Bookkeeping records and organizes business transactions, while tax preparation uses financial and other information to determine and report the taxpayer’s tax obligations. The two processes are closely connected.
Why is good bookkeeping important for taxes?
Good bookkeeping helps organize income, expenses and supporting records. The IRS states that business records should support the income, expenses and credits reported on tax returns.
Can accounting software replace supporting documents?
No. Accounting software can help organize transactions, but supporting documentation remains important. The IRS notes that invoices, receipts, statements and other documents can support entries in the books and tax return.
How often should a business update its books?
Monthly bookkeeping is a practical approach for many small businesses. Businesses with high transaction volume may benefit from more frequent updates.
Do I need to reconcile my bank account every month?
Monthly reconciliation is a strong bookkeeping practice because it can identify missing, duplicate or incorrectly recorded transactions before they become larger problems.
How long should business records be kept?
The required retention period depends on the type of record and the transaction. The IRS says records should generally be kept as long as needed to substantiate the income or deductions reported on a tax return. Employment tax records generally have a longer specific retention requirement of at least four years.
Can good bookkeeping help with an IRS examination?
Yes. Complete records can help substantiate reported items and make it easier to explain transactions if the IRS examines a return.
Final Thoughts
Tax preparation should not begin when tax season arrives.
It should begin with the way your business records transactions throughout the year.
Good bookkeeping creates a reliable financial history. It helps identify income, track expenses, reconcile accounts, maintain supporting documents and understand the financial position of the business. The IRS specifically recognizes these functions as important reasons businesses should maintain good records.
More importantly, good bookkeeping gives business owners better information before tax season arrives.
Instead of asking an accountant to reconstruct the year, the business can provide organized financial records that are ready for review.
That can make tax preparation more efficient, reduce unnecessary questions and help identify issues while there is still time to address them.
Good tax records do not start with the tax return. They start with good bookkeeping throughout the year.
If your books are behind, unreconciled or difficult to understand, getting them organized before tax preparation can make a significant difference. Veritas Accounting Services provides bookkeeping, accounting and U.S. tax support for businesses and international clients.
GET IN TOUCH
Schedule a FREE Call
Connect on our Socials!