




Buying Equipment to Save Taxes? Here’s What You Need to Consider
Buying equipment before year-end can be an effective tax-planning strategy for a business. But there is an important distinction many business owners overlook: a tax deduction does not make an equipment purchase free.
If your business genuinely needs a new machine, computer system, vehicle, tools, or other qualifying property, tax rules may allow you to recover some or all of the cost through depreciation, Section 179, or the additional first-year depreciation deduction. For 2026, the IRS says the Section 179 maximum deduction is $2.56 million, with a phaseout beginning when qualifying property placed in service exceeds $4.09 million. Certain qualified property acquired after January 19, 2025, may also qualify for 100% additional first-year depreciation.
But the tax benefit should be only one part of the decision.
Before you make a large purchase simply because someone says it will “save taxes,” consider the equipment’s business purpose, timing, financing, cash flow impact, business-use percentage, eligibility, and long-term value.
Table of Contents
- Why Businesses Buy Equipment for Tax Reasons
- How an Equipment Tax Deduction Works
- Section 179 and 100% Bonus Depreciation
- The Equipment Must Actually Be Used in the Business
- Timing Matters: “Placed in Service” Is Important
- Business Use Matters
- A Tax Deduction Does Not Mean Free Equipment
- Consider Cash Flow Before Buying
- Compare Buying With Other Options
- Keep Proper Documentation
- Common Mistakes to Avoid
- A Simple Example
- Questions to Ask Before Buying
- Frequently Asked Questions
Why Businesses Buy Equipment for Tax Reasons
Business owners often reach the end of a profitable year and start looking for legitimate ways to reduce taxable income.
Equipment purchases naturally come into the conversation.
Perhaps a construction company needs a new machine. A trucking company needs a vehicle. An e-commerce company needs warehouse equipment. A professional firm needs computers and servers. A manufacturer needs production machinery.
If the equipment is genuinely needed, purchasing it may also create a tax benefit.
However, the order of thinking matters.
The better question is not:
“How much tax can I save if I buy this?”
Instead, ask:
“Does my business need this equipment, and if so, how should I structure the purchase from both a tax and financial perspective?”
That difference can prevent a business owner from spending $50,000 simply to avoid paying a much smaller amount in taxes.
An equipment tax deduction can reduce taxable income, but it does not normally reimburse the entire purchase price.
How an Equipment Tax Deduction Works
Equipment used in a trade or business may generally be depreciable if it meets the applicable requirements. The IRS explains that depreciable property generally must be owned, used in a business or income-producing activity, have a determinable useful life, and be expected to last more than one year.
Depending on the property and the taxpayer’s circumstances, the cost may be recovered through regular depreciation or accelerated methods.
For example, suppose a business purchases qualifying equipment for $50,000.
The tax treatment might allow the business to deduct some or all of the qualifying cost in the year the equipment is placed in service, depending on the applicable rules and elections.
But the tax savings depend on the business’s actual tax situation.
If a business receives a $50,000 deduction and its marginal federal tax rate is 24%, the federal income tax reduction associated with that deduction could be approximately $12,000, before considering other tax effects & tax deduction
The business still spent $50,000.
That is why an equipment tax deduction should be viewed as part of the economics of a purchase, not the reason to purchase something the business does not need.
Section 179 and 100% Bonus Depreciation
Two provisions frequently come up when business owners discuss equipment purchases: Section 179 and additional first-year depreciation, commonly referred to as bonus depreciation.
They are not exactly the same.
Section 179 allows qualifying businesses to elect to expense eligible property rather than recover the cost through regular depreciation over time. For tax years beginning in 2026, the maximum Section 179 expense deduction is $2.56 million, and the limitation begins to phase down when the cost of Section 179 property placed in service exceeds $4.09 million. The IRS also lists a $32,000 Section 179 limit for certain sport utility vehicles for 2026.
There are also business-income limitations and other eligibility rules that need to be considered.
The rules for bonus depreciation are different. The IRS states that the 100% additional first-year depreciation deduction generally applies to certain qualified property acquired after January 19, 2025.
The exact treatment depends on the property, acquisition date, placed-in-service date, taxpayer and other circumstances.
This is why simply hearing “equipment is 100% deductible” can be misleading.
The actual tax treatment & tax deduction should be determined based on the specific purchase and the taxpayer’s circumstances.
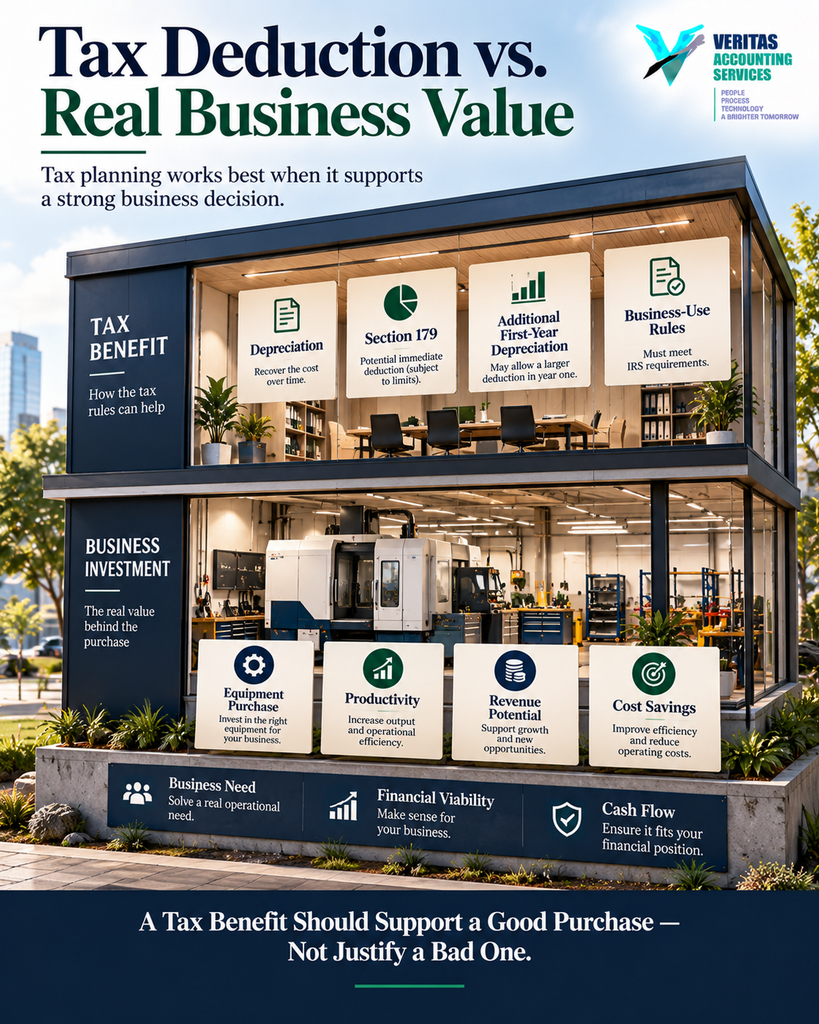
The Equipment Must Actually Be Used in the Business
One of the first questions to ask is whether the equipment has a genuine business purpose.
The IRS generally does not allow depreciation for property used solely for personal activities. If property is used for both business and personal purposes, the deductible depreciation is generally limited to the business or investment use portion.
For example, purchasing a computer primarily for personal use and occasionally using it for business does not automatically turn the entire purchase into a business deduction.
Similarly, vehicles and other property with mixed use require careful attention to documentation and applicable rules.
Before purchasing, business owner should document why the equipment is necessary for the business and how it will be used.
Timing Matters: “Placed in Service” Is Important
Another common misunderstanding is that simply purchasing equipment before December 31 automatically creates a deduction for that year.
The relevant concept is often the placed-in-service date.
The IRS explains that property is generally placed in service when it is ready and available for its specific business or income-producing use. It does not necessarily mean the date you first physically use the property.
Consider a business that orders a machine in December but the machine is delivered and installed several weeks later.
The purchase date and placed-in-service date may be different.
If year-end tax planning depends on the deduction being available in a particular tax year, the business should determine whether the equipment actually meets the placed-in-service requirement for that year.
This is particularly important for large purchases made near year-end.
Business Use Matters
The percentage of business use can significantly affect the tax treatment.
Suppose a business purchases equipment for $40,000 and uses it 80% for business and 20% for personal purposes.
The business portion may be relevant when determining the depreciable basis, depending on the applicable rules.
The IRS specifically explains that when property is used for both business and personal purposes, depreciation is generally limited to the business or investment use portion.
Certain property also has additional substantiation and business-use requirements.
Therefore, maintaining a clear record of how equipment is used is important.
For vehicles and other property where personal use can be significant, businesses should be particularly careful about maintaining supporting records.
A Tax Deduction Does Not Mean Free Equipment
This is the most important financial lesson.
Imagine a business owner is considering purchasing equipment for $100,000.
Someone says:
“Buy it before year-end. You’ll get a $100,000 deduction.”
The business owner might think:
“That means I save $100,000.”
That is not how a deduction works.
A $100,000 deduction generally reduces taxable income by $100,000, subject to the applicable rules. It does not mean the government reimburses the business $100,000.
If the combined marginal tax effect were 30%, for illustration, a $100,000 deduction might reduce taxes by approximately $30,000.
The business still spent $100,000.
The equipment may be an excellent purchase if it increases productivity, reduces labor costs, expands capacity, improves quality or generates additional revenue.
But buying unnecessary equipment simply for the deduction can destroy cash that the business could have used more effectively elsewhere.
Consider Cash Flow Before Buying
Tax planning and cash-flow planning should happen together.
Before purchasing equipment, consider:
How much cash will remain after the purchase?
Will the business still have enough money for payroll?
Are accounts payable and upcoming taxes fully covered?
Will the business need additional working capital?
Will the equipment generate additional revenue?
Will maintenance, insurance, software or operating costs increase?
If the purchase is financed, what will the monthly payment be?
A tax benefit received today may not compensate for a cash-flow problem that lasts for the next two years.
This is particularly important for seasonal businesses or businesses with uneven monthly revenue.
A good equipment tax deduction should support a sound business decision rather than replace one.
Compare Buying With Other Options
Buying is not always the only option.
Depending on the business and the equipment, you may also consider leasing, financing, renting or delaying the purchase.
Each option can produce a different financial and tax result.
For example, leasing may preserve cash and avoid a large upfront payment. Buying may provide ownership and potential depreciation benefits. Financing may allow the business to acquire an asset while spreading cash payments over time.
The right comparison should include:
Purchase price
Financing cost
Monthly cash requirement
Expected useful life
Maintenance costs
Expected resale value
Tax treatment
Expected business benefit
The tax impact should be included in the comparison, but it should not be the only factor.
Keep Proper Documentation
If you claim an equipment tax deduction, documentation matters.
Keep the purchase invoice, payment records, financing documents, serial numbers, installation records and evidence supporting business use.
For larger assets, maintain information about when the property was acquired and when it was placed in service.
If the equipment has mixed business and personal use, maintain records that support the business-use percentage.
The IRS states that taxpayers must keep records showing business, investment and personal use of property when applicable.
Good documentation also helps your accountant determine the appropriate tax treatment and makes future reviews easier.
Common Mistakes to Avoid
Buying equipment the business does not need
A deduction should not be the primary reason for making an unnecessary purchase.
Assuming every purchase qualifies
Not every asset receives the same tax treatment. Eligibility depends on the type of property and the applicable tax rules.
Ignoring the placed-in-service date
Buying equipment before year-end does not automatically mean it qualifies for the intended tax year.
Forgetting business-use limitations
Mixed personal and business use can affect the deductible amount.
Looking only at the federal deduction
State tax rules may differ from federal rules, so businesses should consider the overall tax impact.
Ignoring cash flow
A tax deduction can reduce taxable income while the actual cash leaves the business immediately.
Failing to plan for future years
Taking a large deduction today can affect the timing of deductions available in future years.
The goal should be sustainable tax planning rather than simply maximizing one year’s tax deduction.
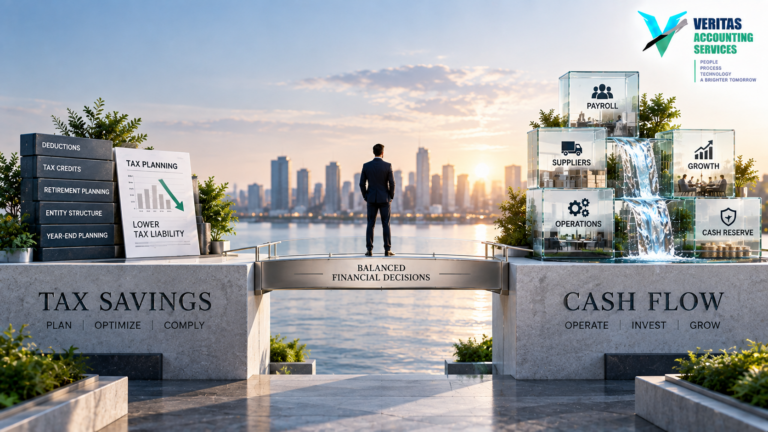
A Simple Example: Tax Savings vs. Purchase Cost
Consider a business that is considering a $60,000 piece of equipment.
The owner expects the equipment to improve production capacity and believes it will generate additional revenue.
The business also expects to qualify for an accelerated tax deduction under the applicable rules.
If the entire $60,000 were deductible and the relevant marginal federal tax rate were 25%, the simplified federal tax effect would be approximately $15,000.
That does not make the equipment cost $15,000.
The business still spends $60,000, although the tax benefit can reduce the after-tax economic cost.
Now consider a different situation.
Suppose the business does not actually need the equipment and buys it only because the owner expects a tax deduction.
The business has exchanged $60,000 of cash for an asset that may provide little economic value.
Even if the tax benefit is real, the decision may not make financial sense.
The better strategy is to purchase equipment because it serves the business first and then structure the purchase efficiently from a tax perspective.
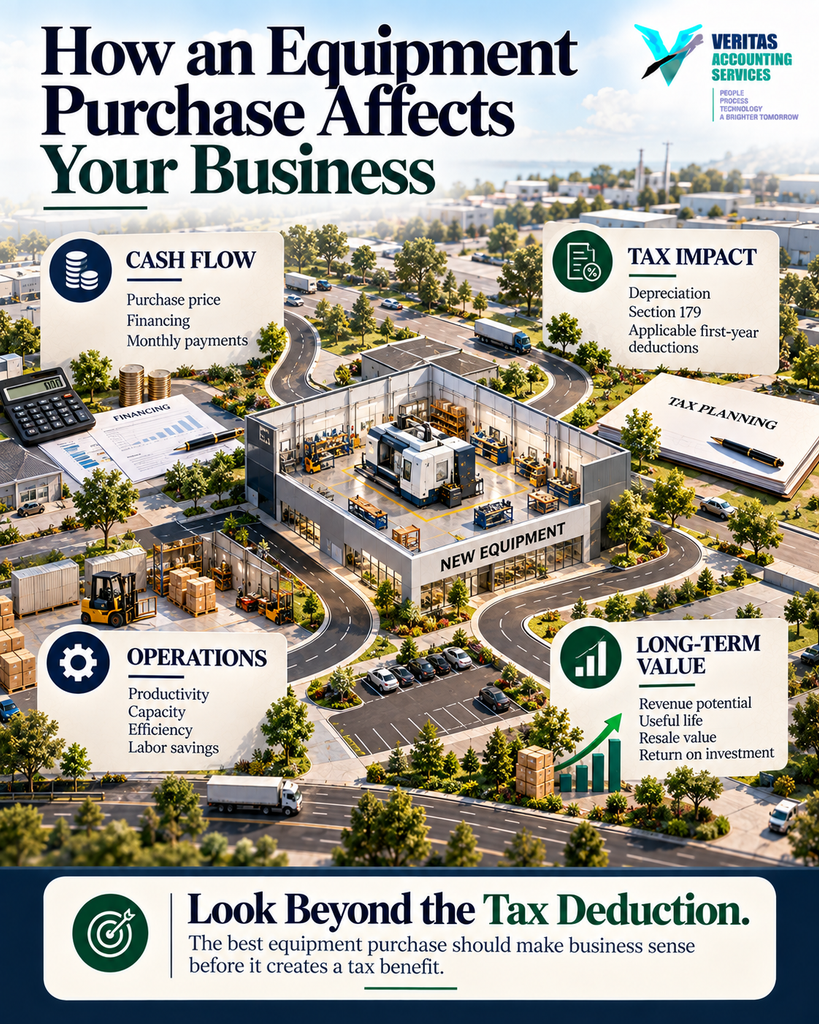
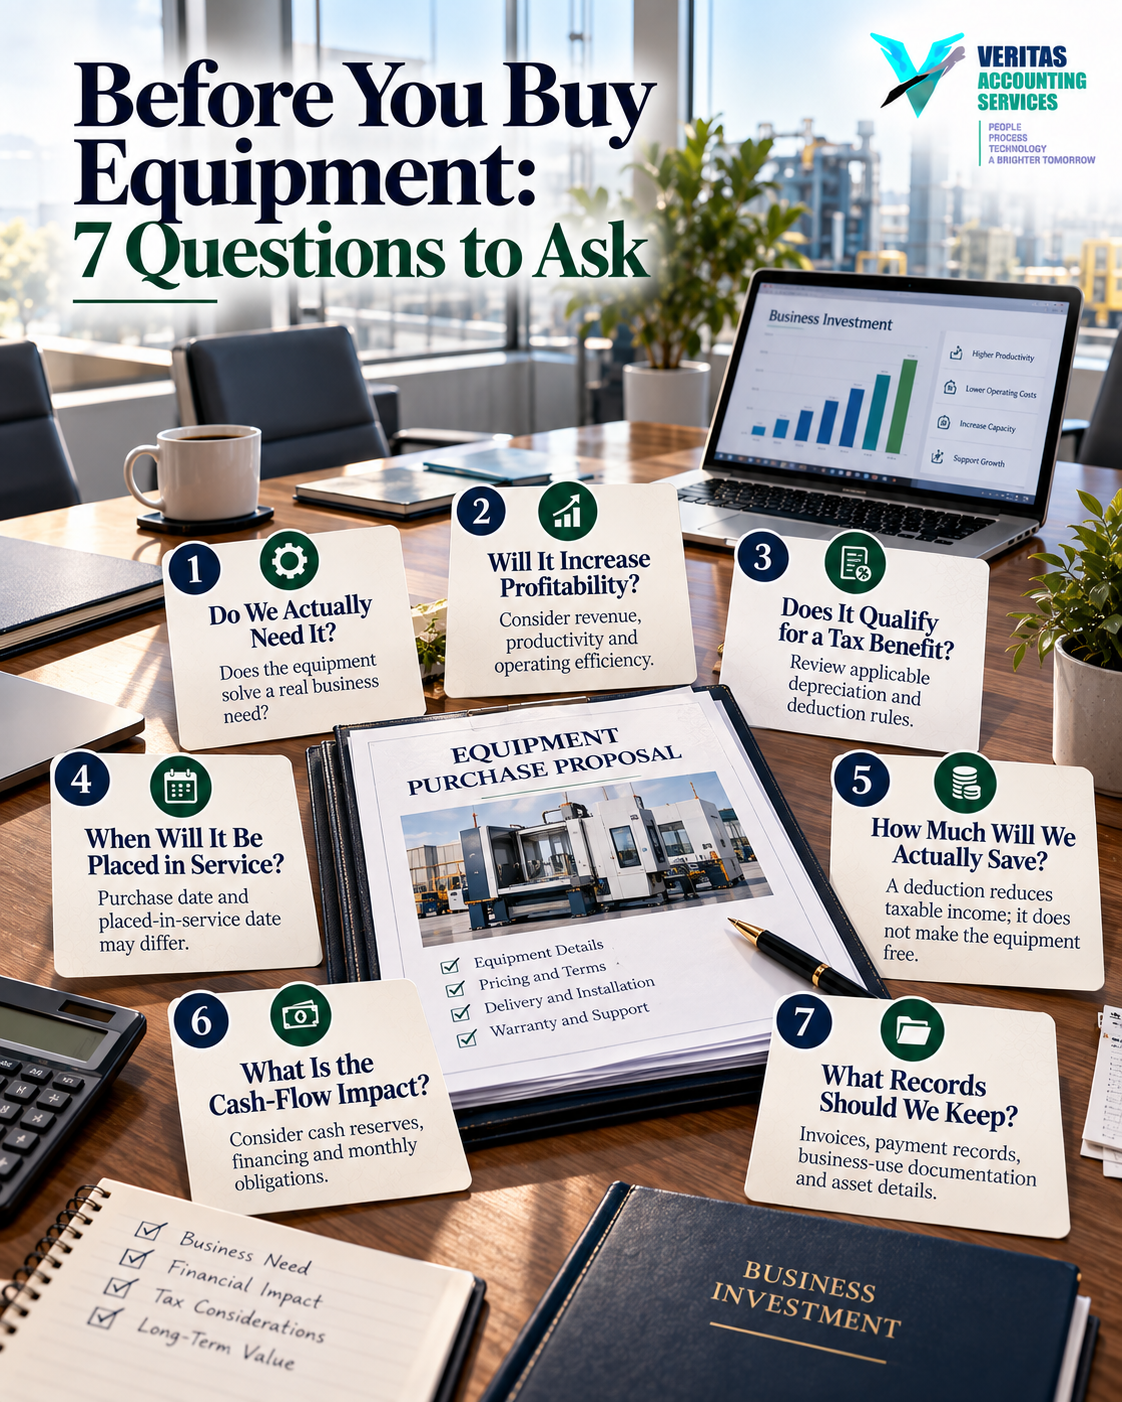
Questions to Ask Before Buying
Before making a significant equipment purchase, ask these questions:
Does the business actually need the equipment?
Will it increase revenue, productivity or capacity?
Is the equipment eligible for the intended tax treatment?
When will it be placed in service?
What percentage will be used for business?
Should Section 179 be considered?
Could additional first-year depreciation apply?
What is the impact on cash flow?
Would financing or leasing be more appropriate?
What documentation should be maintained?
How will the purchase affect state taxes?
What will the business’s tax position look like after the purchase?
These questions help turn an equipment purchase from a last-minute tax decision into a broader business decision.
Frequently Asked Questions
Is buying equipment just to get a tax deduction a good strategy?
Not necessarily. The equipment should have a genuine business purpose and provide economic value. The tax benefit should be considered alongside cash flow, financing, productivity and expected return on investment.
Can I deduct the full cost of equipment in the year I buy it?
Sometimes. Depending on the equipment and taxpayer, Section 179 or additional first-year depreciation may allow accelerated recovery of qualifying costs. The specific rules and limitations must be reviewed for the relevant tax year.
Does buying equipment before December 31 guarantee a tax deduction for that year?
No. The placed-in-service requirement can be important. Equipment generally needs to be ready and available for its intended business use.
What is the 2026 Section 179 limit?
For tax years beginning in 2026, the IRS states that the maximum Section 179 expense deduction is $2.56 million, with a phaseout beginning when qualifying property placed in service exceeds $4.09 million.
Is 100% bonus depreciation available in 2026?
The IRS states that 100% additional first-year depreciation generally applies to certain qualified property acquired after January 19, 2025. Eligibility and other requirements still need to be considered.
Should I buy equipment before year-end to reduce taxes?
That depends on the business’s needs and tax position. A business should evaluate the equipment’s financial return, cash-flow impact, tax treatment and expected useful life before making the purchase.
Final Thoughts
An equipment purchase can be an effective part of tax planning, but tax savings should not be the reason to buy something your business does not need.
For 2026, businesses have potentially significant opportunities through Section 179 and accelerated depreciation provisions, but eligibility, limits, business use, timing and documentation all matter.
The best approach is to start with the business decision.
Determine what equipment the business genuinely needs. Estimate the financial return. Consider cash flow and financing. Then evaluate the available tax treatment with your tax professional.
When these decisions are made together, an equipment tax deduction can become part of a broader strategy for managing taxes, cash flow and business growth.
If you are considering a major equipment purchase and want to understand the potential tax and financial impact before making the investment, Veritas Accounting Services provides U.S. bookkeeping, accounting and tax support for businesses and international clients. Contact our team to discuss your requirements.
GET IN TOUCH
Schedule a FREE Call
Connect on our Socials!
