📩 Get A Quote : hello@veritasaccountingservices.com
A bakery owner stands beside fresh bread in natural morning light, with the headline Plan for the year ahead and the faithful Veritas Accounting Services logo.

Tax Bracket Mistakes: A Simple Guide to Better Planning

The 2027 tax brackets are now available following the IRS announcement on November 5, 2026. For business owners, the useful response is to update the assumptions in a personal tax projection, rather than apply a new percentage to business revenue. Start with the correct year, filing status and taxable income, then review the result alongside other taxes and payments.

This guide focuses on federal ordinary individual income tax. It explains a single-filer example and five practical checks for an owner’s planning worksheet. It does not calculate a company’s complete tax liability or assume that every owner has the same filing status, income sources or deductions.

Understanding the 2027 tax brackets matters when planning cash. A clear estimate can support decisions about reserves and owner withdrawals. A spreadsheet using an outdated table, the wrong income figure or one flat rate can make an apparently precise answer unreliable.

Table of contents

What changed in the IRS announcement

The November 5 IRS announcement sets out annual inflation adjustments for tax year 2027. The IRS says these amounts generally affect returns filed in 2028. Publication in 2026 does not turn the figures into 2026 tax-year amounts.

For 2027 tax brackets, treat that date distinction as the first control in the file. A worksheet labeled next return can be misunderstood by a bookkeeper, an owner and a preparer. Put the actual income year in the heading and retain the source date beside the assumptions.

The release also lists basic standard deductions of $16,600 for single filers and married individuals filing separately, $33,200 for married filing jointly, and $24,925 for heads of household. Those are starting reference amounts; individual eligibility and additional amounts require their own review.

The IRS standard deduction guidance explains that the deduction reduces income subject to tax and is unavailable in some circumstances. It is not a credit that reduces the tax bill dollar for dollar. Do not automatically subtract it without checking the person’s situation.

Our year-end tax planning discussion describes a wider review of business results and planned transactions. Here, the narrower task is to refresh the bracket assumptions while keeping the current-year close and next-year forecast clearly separated.

Read the 2027 tax brackets correctly

The 2027 tax brackets apply different rates to successive layers of taxable income. Moving into a higher layer does not make that higher rate apply to every dollar below it. The IRS explanation of marginal rates describes this layered approach.

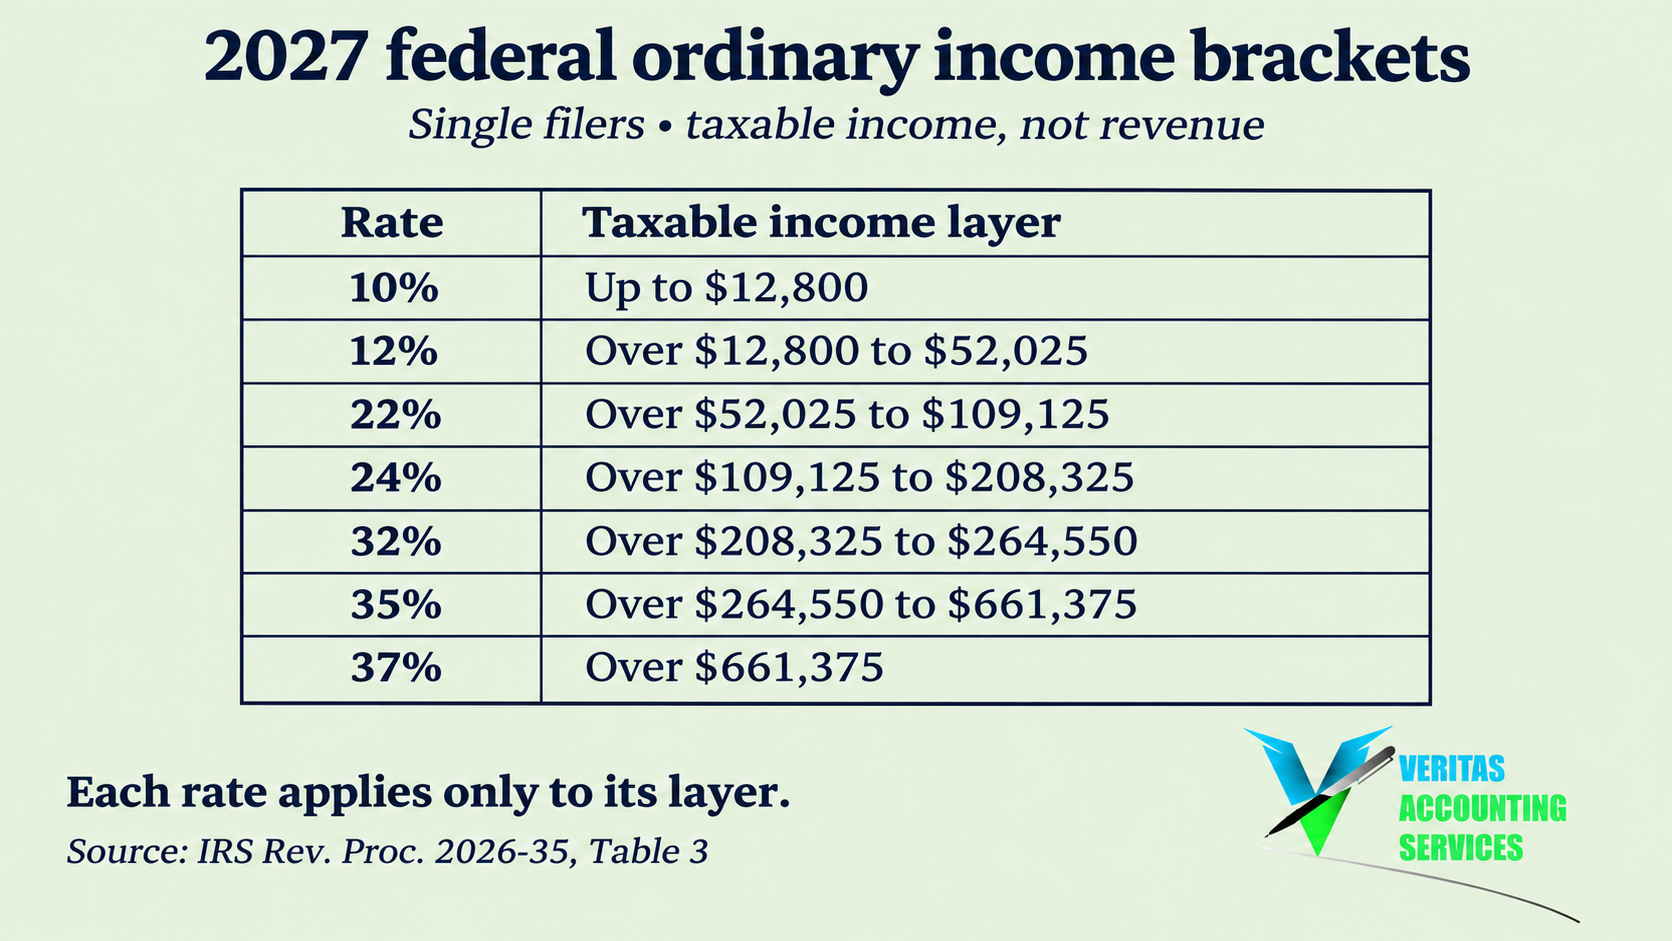
The following table of 2027 tax brackets is for single filers, using the unmarried-individual table in Revenue Procedure 2026-35. It covers ordinary income under that schedule. Do not substitute this table for a different filing status or for income subject to special rates.

Rate2027 taxable income layer for a single filer
10%Up to $12,800
12%Over $12,800 through $52,025
22%Over $52,025 through $109,125
24%Over $109,125 through $208,325
32%Over $208,325 through $264,550
35%Over $264,550 through $661,375
37%Over $661,375
2027 tax brackets reference table for single filers shows seven ordinary taxable income layers and states that each rate applies only to its layer.

When using 2027 tax brackets, distinguish a marginal rate from an average calculation. The marginal rate describes the rate on the next dollar within the relevant layer. Dividing a calculated tax amount by the income used in the example answers a different question.

Also distinguish taxable income from sales, bank deposits and bookkeeping profit. Before relying on a figure, ask where it came from and what adjustments it includes. A number can be correctly copied from the profit and loss statement yet still be the wrong input for an individual bracket calculation.

The 2027 tax brackets table is a reference, not an instruction to multiply an owner’s draws by a rate. Mark its scope on any exported worksheet. That short label helps prevent the same figures from being reused later for a corporation, a different filing status or a different year.

A worked example with separate income layers

Suppose an individual is a single filer with exactly $60,000 of taxable ordinary income for 2027. Assume the appropriate deductions and adjustments have already been reflected in that taxable-income figure. The example is hypothetical, not a Veritas client case or a complete return calculation.

Using the 2027 tax brackets, the first $12,800 produces $1,280 at 10%. The next $39,225, from $12,800 to $52,025, produces $4,707 at 12%. The remaining $7,975 produces $1,754.50 at 22%.

The sum is $7,741.50 of illustrative regular federal income tax before credits. The example excludes self-employment tax, alternative minimum tax, special-rate income and any other taxes or adjustments. It demonstrates the layers; it does not establish what a particular owner should pay.
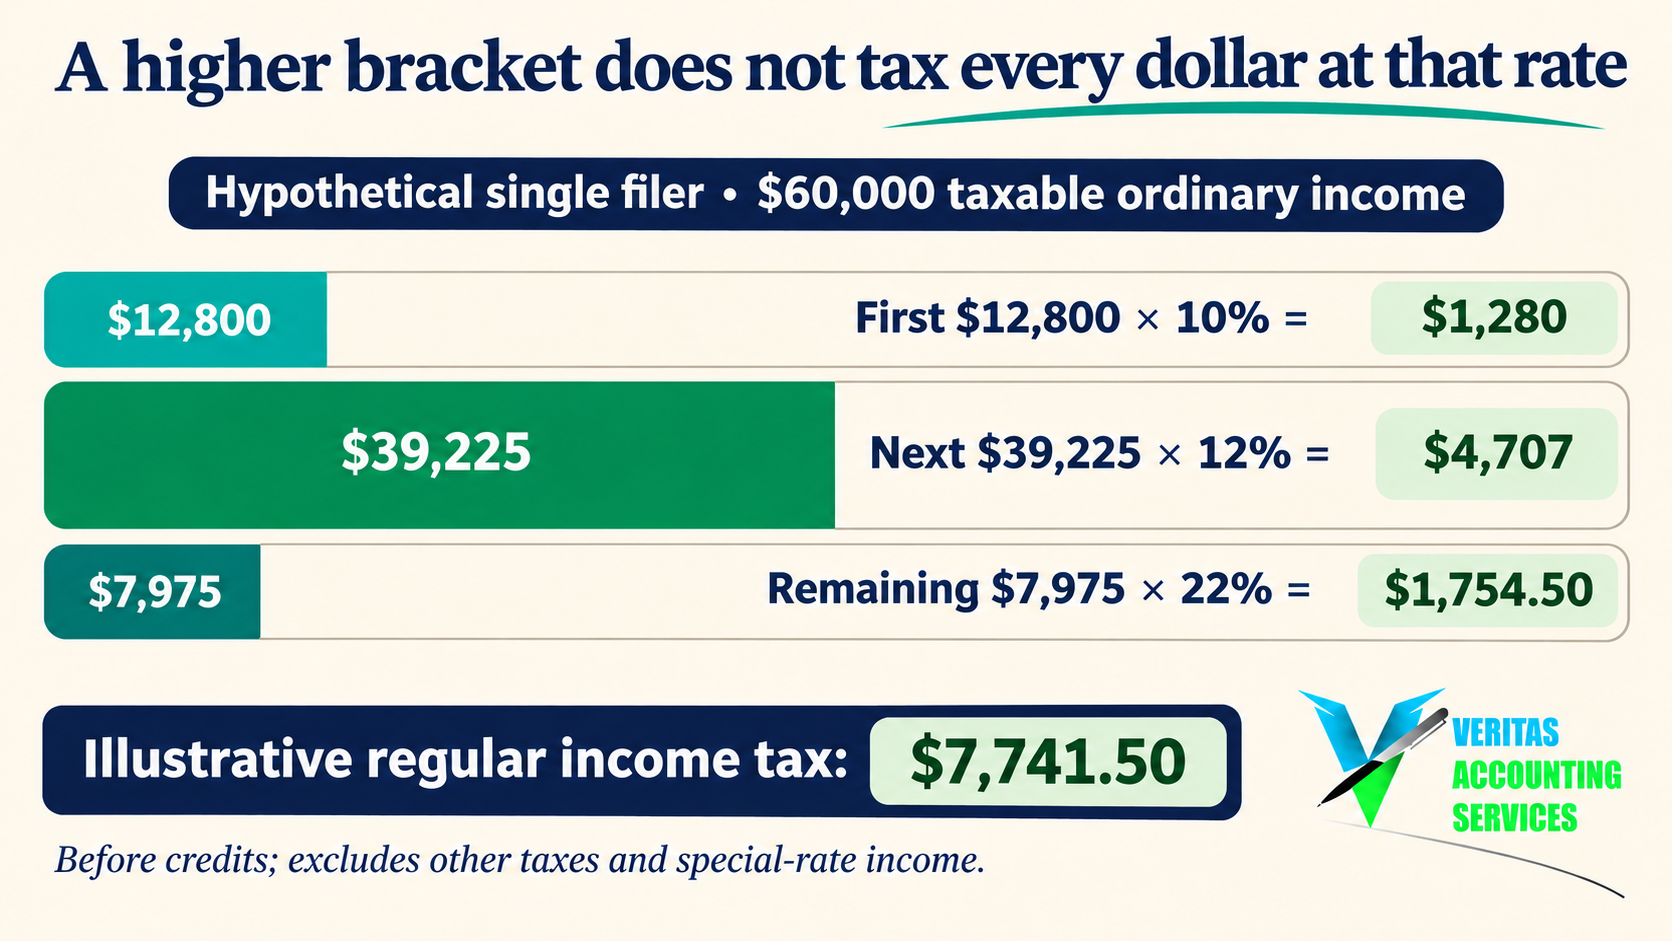
Hypothetical single-filer calculation uses $60,000 taxable ordinary income: $1,280 plus $4,707 plus $1,754.50 equals $7,741.50 regular income tax before credits and other taxes.

Compare that with multiplying all $60,000 by 22%, which gives $13,200. The difference is $5,458.50. That difference illustrates an incorrect calculation, not an available tax saving or a refund someone can claim.

For 2027 tax brackets, keep the calculation visible rather than hiding it inside a single percentage cell. A reviewer should be able to follow the layer widths, rates and total. Clear arithmetic makes a discussion about the remaining assumptions much easier.

When reviewing the 2027 tax brackets example, do not subtract the standard deduction again. The starting figure is already taxable income, after the assumed relevant deductions. If a worksheet starts with income before those deductions, it needs a different sequence and a documented reconciliation.

This example also shows why a bracket label alone cannot set a cash reserve. Before choosing a transfer amount, the owner and adviser still need to consider the rest of the projection, payments already made and the timing of available cash.

Five checks before updating your worksheet

1. Lock the income year and source

Build the 2027 tax brackets into a separately identified 2027 assumptions sheet. Keep the 2026 model intact so current-year questions can still be answered using its own assumptions. Changing every rate cell in a shared workbook can silently alter an earlier forecast.

Record the source document, table number, date checked and person who checked it. These are suggested internal review fields, not an IRS-prescribed worksheet. They give the next reviewer a short route back to the underlying authority.

If a spreadsheet contains both actual results and projections, make the boundary visible. A November actual-results column and a full-year forecast column answer different questions. Their labels should remain clear when the page is printed or attached to an email.

For the 2027 tax brackets, a useful change note states which assumption changed and which calculations depend on it. Avoid a vague updated for IRS changes note that leaves the reviewer searching through the entire file to understand the revision.

2. Match the individual and filing status

Confirm whose projection you are preparing before choosing a table. A business with two owners may need two separate individual analyses. One owner’s personal assumptions should not be copied across simply because both people receive information from the same accounting file.

The 2027 tax brackets shown above are specifically for a single filer. Record the applicable status and ask the preparer to resolve uncertainty. Do not use the single-filer thresholds as a convenient substitute while leaving the worksheet labeled final.

Keep personal information proportionate to the task. A working budget may need a named owner and an agreed filing-status assumption without circulating a complete prior-year return to everyone involved in bookkeeping. Give detailed tax documents only to the people who need them.

If family circumstances or ownership arrangements are changing, note the question rather than guessing its treatment. The purpose of the planning file is to make important assumptions visible so that a qualified reviewer can resolve them.

3. Reconcile the taxable-income input

Before applying 2027 tax brackets, build a clear bridge from the financial information available to the taxable-income figure being modeled. Label the bridge as a projection and identify which adjustments are confirmed, estimated or awaiting professional review.

Our bookkeeping cleanup guide explains why incomplete books create extra work later. For this worksheet, the immediate question is whether the financial starting point can be reconciled to a dated report and whether unresolved entries are visible.

Separate recurring operations from unusual transactions in the discussion. A sale, distribution, reimbursement or bank transfer may need explanation before its tax significance can be determined. The fact that an item appears as a cash movement does not settle the individual tax calculation.

For 2027 tax brackets, use a dedicated taxable-income input rather than pointing the formula directly at a revenue total. That design makes the review step explicit. It also reduces the risk that a later bookkeeping layout change feeds a different number into the model.

Keep the estimated deduction assumptions readable. Show what has already been included, so a reviewer can spot double counting. A separate notes column is often more useful than embedding a long explanation inside a formula that only its author understands.

4. Review taxes and payments outside the bracket result

The 2027 tax brackets do not calculate every part of an owner’s tax position. The IRS estimated-tax guidance explains that estimated payments can cover income tax and other taxes, including self-employment tax. A regular income-tax subtotal is therefore only one part of a payment review.

Keep separate lines for other items the adviser identifies as relevant. Also record withholding and estimated payments with their periods and supporting confirmations. Do not mix a projected annual liability with cash already paid and call the combined number tax expense.

Federal individual thresholds do not establish state tax treatment. Mark state questions for a separate review using the relevant official state authority. This article supplies no state calculation and should not be used as evidence that any state follows these amounts.

For 2027 tax brackets, the practical safeguard is a clear subtotal label. Regular federal income tax before credits and other items is much more informative than total taxes when the remaining work has not been completed.

Our estimated tax payments guide addresses payment-method and timing questions separately. Keep that review distinct from selecting an annual bracket table; the right table alone does not prove that payments are sufficient or timely.

5. Review the result before changing cash reserves

Use the 2027 tax brackets as part of a reviewed forecast, then agree what the owner will do with the result. A change to a workbook is not the same as an approved change to withdrawals, reserves or payment instructions.

Show the reviewer the prior forecast, revised forecast and explanation for the difference. Separate the effect of updated thresholds from changes in expected income or deductions. Otherwise, a lower estimate may be credited to the announcement when the real driver is a weaker sales assumption.

Set a practical review date and name the person responsible for refreshing the inputs. A projection prepared before a major contract is signed may need another look afterward. The review date is a management choice, not a filing deadline created by this article.

Keep a brief approval record explaining which version the owner used. It should be possible to reconnect a cash decision with the assumptions available at the time. That is more useful than retaining several files named latest without a clear sequence.
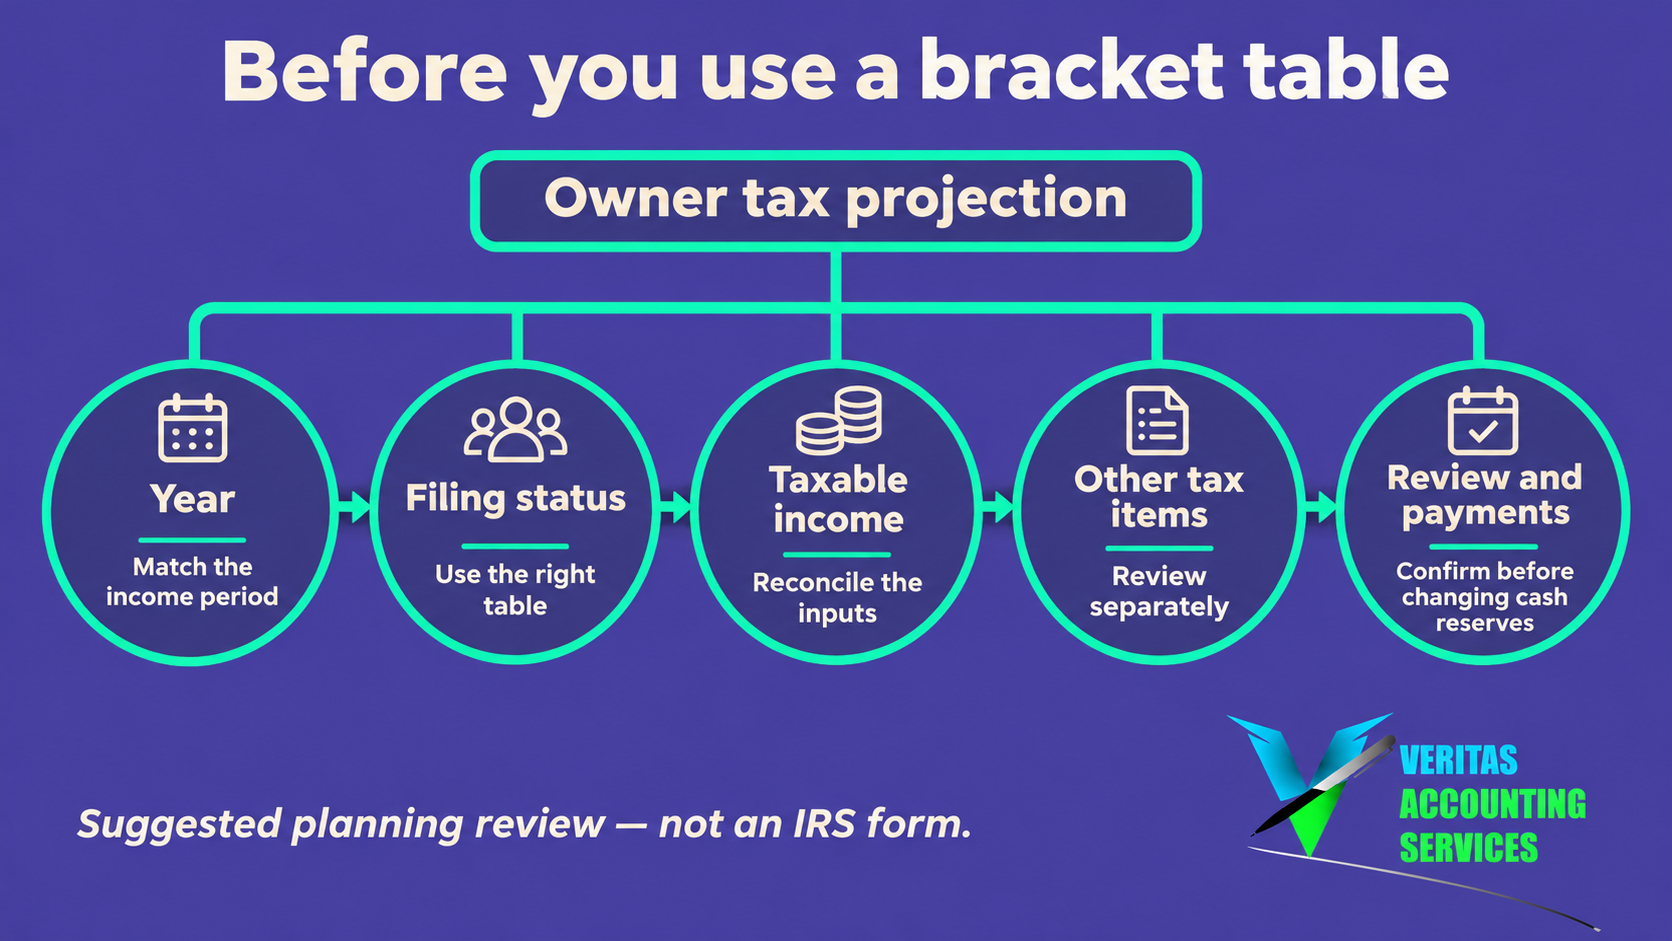
Five connected planning checks cover year, filing status, taxable income, other tax items, and review and payments, with a note that this is a suggested planning review rather than an IRS form.

Turn the estimate into a cash discussion

The 2027 tax brackets can help organize a forecast, but cash planning needs a second conversation. Ask when income is expected to be collected, which operating payments are committed and which amounts the owner is considering withdrawing. Keep those timing assumptions beside the reviewed tax estimate.

Consider an owner looking at a profitable quarter while a large customer invoice remains unpaid. The projection might indicate a future tax reserve need, but the bank balance may not yet support the proposed transfer. Identify that gap explicitly instead of treating accounting profit as cash available today.

For 2027 tax brackets, avoid a universal reserve percentage presented as advice to every reader. Different household income, deductions, payments and other tax items can change the answer. Agree a method with the adviser and explain when the assumptions should be refreshed.

A useful meeting ends with a small number of decisions: which facts remain open, which version is approved, what action is planned and who will check again. Our compliance calendar guide offers a related way to organize owners, dates and evidence without confusing a reminder with completion.

Give your adviser a useful handoff

Send the reviewed worksheet with the supporting report date, individual assumptions and unresolved questions. Explain that the 2027 tax brackets have been refreshed, then identify what has not yet been decided. A narrow question usually receives a clearer answer than a request to confirm the entire file without context.

For example, ask whether the taxable-income bridge includes the expected deduction correctly, or whether an unusual transaction needs separate treatment. Keep operational assumptions, such as expected collections, distinguishable from tax conclusions that require professional judgment.

If the adviser changes an assumption, record the reason and update the dependent calculations together. Reconcile the new total before distributing a revised version. This prevents the narrative in an email from disagreeing with the figures used in the next cash meeting. When sharing the model, export the assumption page with the calculation, so the recipient receives the context as well as the final estimate.

Frequently asked questions

Do the 2027 tax brackets apply to my 2026 income?

No. These are tax-year 2027 figures, announced in November 2026. The IRS says they generally concern returns filed in 2028. Keep a separate, correctly labeled calculation for 2026 income.

Does reaching a higher bracket raise the rate on all income?

No. Rates apply by layer. The higher rate affects the income within that higher layer under the applicable schedule, rather than replacing the rates on every lower layer.

Can I multiply business sales by my personal bracket?

That is not a reliable individual tax projection. Reconcile the appropriate taxable-income input first. Business revenue, bookkeeping profit and the owner’s taxable income should not be treated as interchangeable labels.

Do the 2027 tax brackets tell me my complete tax bill?

No. The example shows regular federal ordinary income tax before credits and other items. Other taxes, special-rate income, payments and individual circumstances need separate review before a payment decision.

Should I change my tax payments immediately?

Review the complete projection and applicable payment rules with your adviser first. A newly available table is a reason to refresh assumptions, not evidence that a specific person’s required payment has fallen.

What should I keep with my 2027 tax brackets worksheet?

Retain the official source, year, filing-status assumption, taxable-income reconciliation, review notes and approved version. These are suggested planning controls. Protect the underlying personal documents and limit access to people involved in the review.

Conclusion

Use the 2027 tax brackets to improve the quality of a planning conversation: identify the year, choose the right individual table, reconcile taxable income, separate other tax items and review the result before changing cash decisions. The most useful forecast shows its assumptions as clearly as its total.

Start by opening the current planning file and checking those five points. If an assumption is unresolved, name it and assign the next action. That gives the owner and adviser a practical basis for moving from a new IRS announcement to a more dependable budget.

This article provides general US federal tax information reviewed November 6, 2026. Examples are illustrative and do not calculate an individual’s complete liability. Confirm current IRS guidance and circumstances with your tax adviser before acting.

GET IN TOUCH

Schedule a FREE Call

Contact us

Connect on our Socials!
A translucent teal document passes through an emerald filing-folder arch, illustrating clearer contractor-payment reporting.

Your Simple Guide to Contractor Tax Mistakes and New Rules

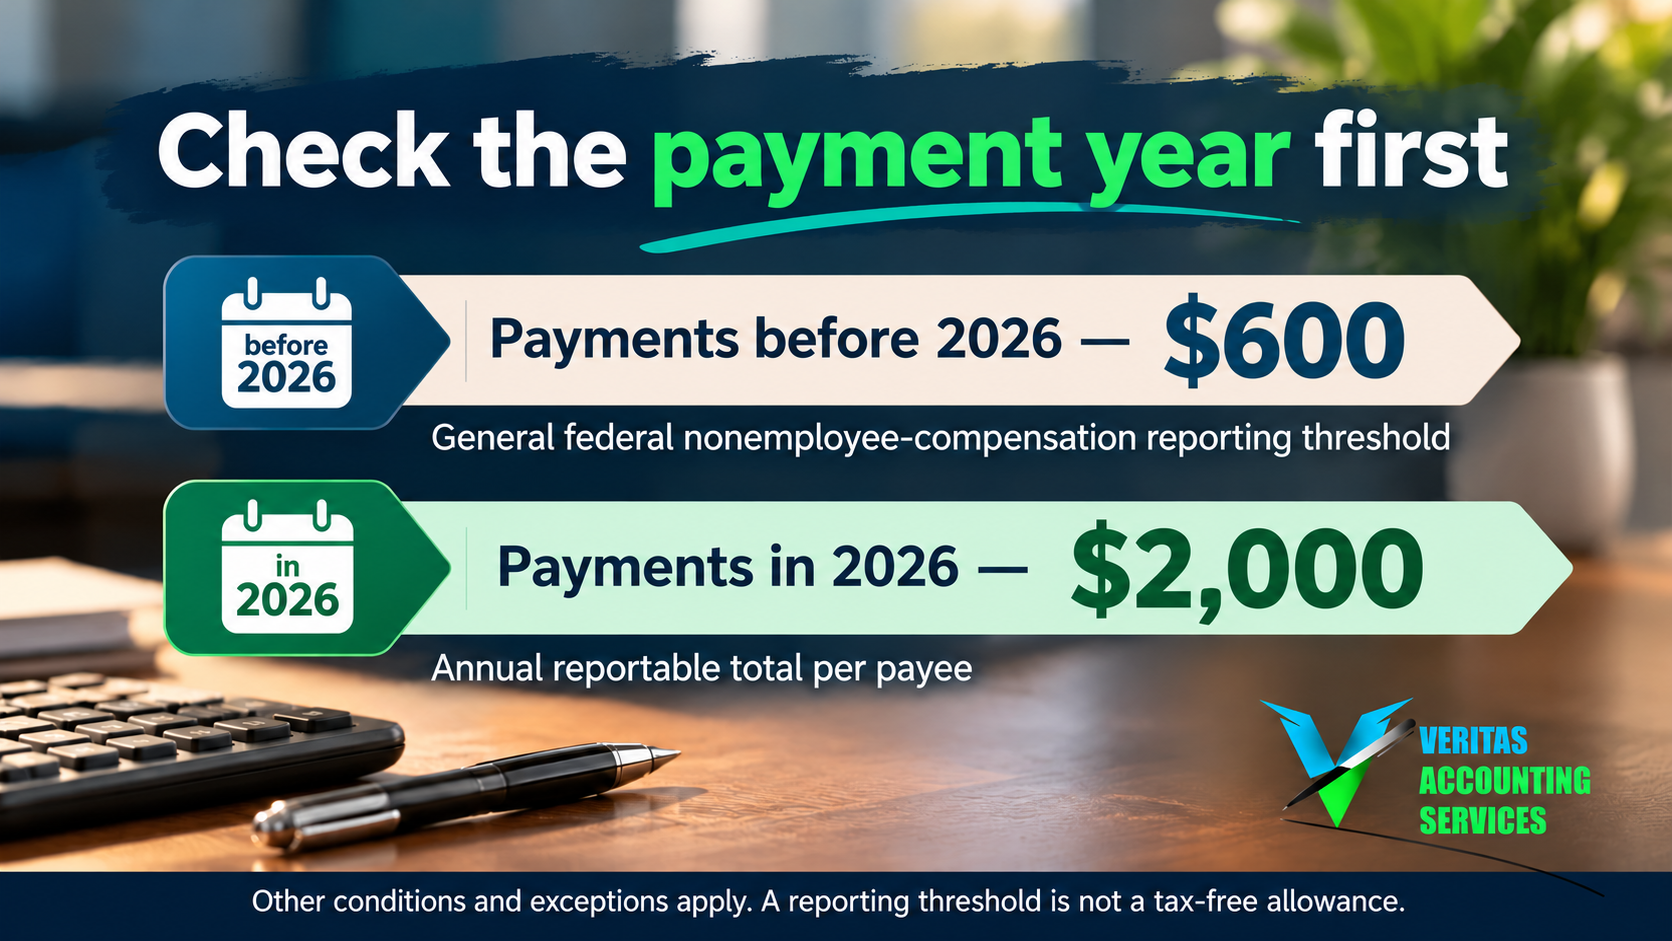
Contractor tax forms need a fresh review for payments made in 2026. The general federal Form 1099-NEC reporting threshold is now $2,000, compared with $600 for payments made before 2026. That change does not make smaller payments tax-free, remove the need for accurate books or settle every reporting question.

The IRS information-return guidance confirms the payment-year distinction and the separate reporting rule when backup withholding has occurred. Use the correct year and payment facts before deciding whether a form is required. An old checklist can lead to the wrong result in either direction.

For a US small-business owner, the useful task is to connect the vendor record, the service provided, the payment route and the annual reportable total. This guide explains five practical checks for ordinary domestic service payments. Foreign payees, unusual transactions and state reporting require their own review.

Table of contents

What changed for 2026

The IRS states that the reporting threshold for Form 1099-NEC is $2,000 for payments made in 2026. For payments made before 2026, the threshold was $600. For later years, check the applicable inflation-adjusted amount rather than assuming that either figure remains correct indefinitely.

The change concerns information reporting. It is not a new deduction for the payer or a tax exemption for the person receiving the money. Whether an expense is deductible and whether a recipient must report income are separate questions from the requirement to issue an information return.

When reviewing contractor tax forms, identify the year of the payments first. A form prepared during the following filing season generally reports the preceding calendar year’s transactions. Do not use the year when someone opens the software as a substitute for the payment year being reported.

This article reviews a rule relevant to the 2026 payment year, rather than announcing a new October-only concession. The IRS newsroom’s latest general planning reminders are a reason to check your process now; they do not change the effective date of this threshold.

Comparison of contractor tax forms showing the general federal nonemployee-compensation reporting threshold of $600 before 2026 and $2,000 for payments in 2026, with conditions and exceptions noted.

Other information returns have their own payment categories and thresholds. Do not apply the Form 1099-NEC amount to every type of Form 1099 simply because the form names look similar. A payment for rent, interest or legal settlement proceeds can raise a different reporting question.

What contractor tax forms actually do

Form 1099-NEC reports qualifying nonemployee compensation. The IRS contractor-payment page describes four general conditions: payment to a nonemployee, services for a trade or business, an eligible type of recipient and reportable payments reaching the applicable annual threshold.

That is why a vendor’s total balance alone cannot make the decision. You need to know what was paid for, who received it and how it was paid. A personal household purchase does not become a trade-or-business service payment merely because the business owner made it.

Contractor tax forms also serve a different purpose from the vendor’s invoice. The invoice describes the commercial transaction; the information return reports a qualifying payment to the IRS and the recipient. Keep both records when relevant, rather than treating one as a replacement for the other.

For contractor tax forms, the payer and recipient have separate responsibilities. A contractor should not conclude that business income disappears because no form arrives. Likewise, a business should not conclude that an otherwise deductible expense is automatically disallowed solely because it falls below a reporting threshold. The actual tax and substantiation rules still matter.

There is also a difference between creating a draft form, filing it with the IRS and furnishing a statement to the recipient. A completed screen in the bookkeeping system is not proof that both delivery obligations have been satisfied. Build those separate checks into the workflow.

Five checks before deciding what to file

1. Confirm the worker’s status

Before preparing contractor tax forms, start with the relationship, not the preferred form. The IRS independent-contractor explanation says classification depends on the facts, including the right to control the work. Calling someone a freelancer in an agreement does not settle the federal employment-tax question.

A Form W-9 does not convert an employee into an independent contractor. That distinction matters for contractor tax forms. Neither does paying through accounts payable or having the worker submit invoices. If the arrangement raises a classification concern, ask for an appropriate review before choosing contractor tax forms.

For employees, payroll and Form W-2 reporting belong in the review. For genuine nonemployees, proceed to the service-payment and payee checks. Our payroll pitfalls guide provides related operational context, while the IRS remains the authority for the federal classification analysis.

Keep the reasoning with the engagement records. A short note identifying what was reviewed, who resolved an uncertainty and when the facts changed can be more useful than a generic checkbox saying “contractor.” Review a relationship again if the actual working arrangement changes materially.

2. Verify the payee’s tax information

Collect the correct name, taxpayer identification number and relevant tax classification through an appropriate process. The IRS Form W-9 page links the form and instructions used to request this information from a US person. The completed form is normally given to the requester, not sent to the IRS as a routine vendor-onboarding submission.

For contractor tax forms, the trading name on an invoice may not be the correct name to pair with the tax identification number. The W-9 instructions distinguish the owner’s name and the business name for a sole proprietor or disregarded entity. Do not guess from a logo or website address.

The letters “LLC” do not, by themselves, tell you the federal tax classification. Read the completed information and resolve inconsistencies before using it. Similarly, do not assume that every corporate payee is exempt from every type of information reporting; payments for legal services are a familiar area needing specific attention.

Foreign-payee documentation and withholding can follow different rules. Do not require a foreign service provider to sign a US-person certification merely to fit the domestic process. Flag the case for the appropriate analysis instead of forcing it into the ordinary W-9 checklist.

Protect the records used for contractor tax forms. They may contain personal tax identifiers even when the vendor operates under a business name. Give staff access according to their job, use the agreed secure transfer method and avoid placing full identification numbers in broadly shared spreadsheets.

3. Separate the payment routes

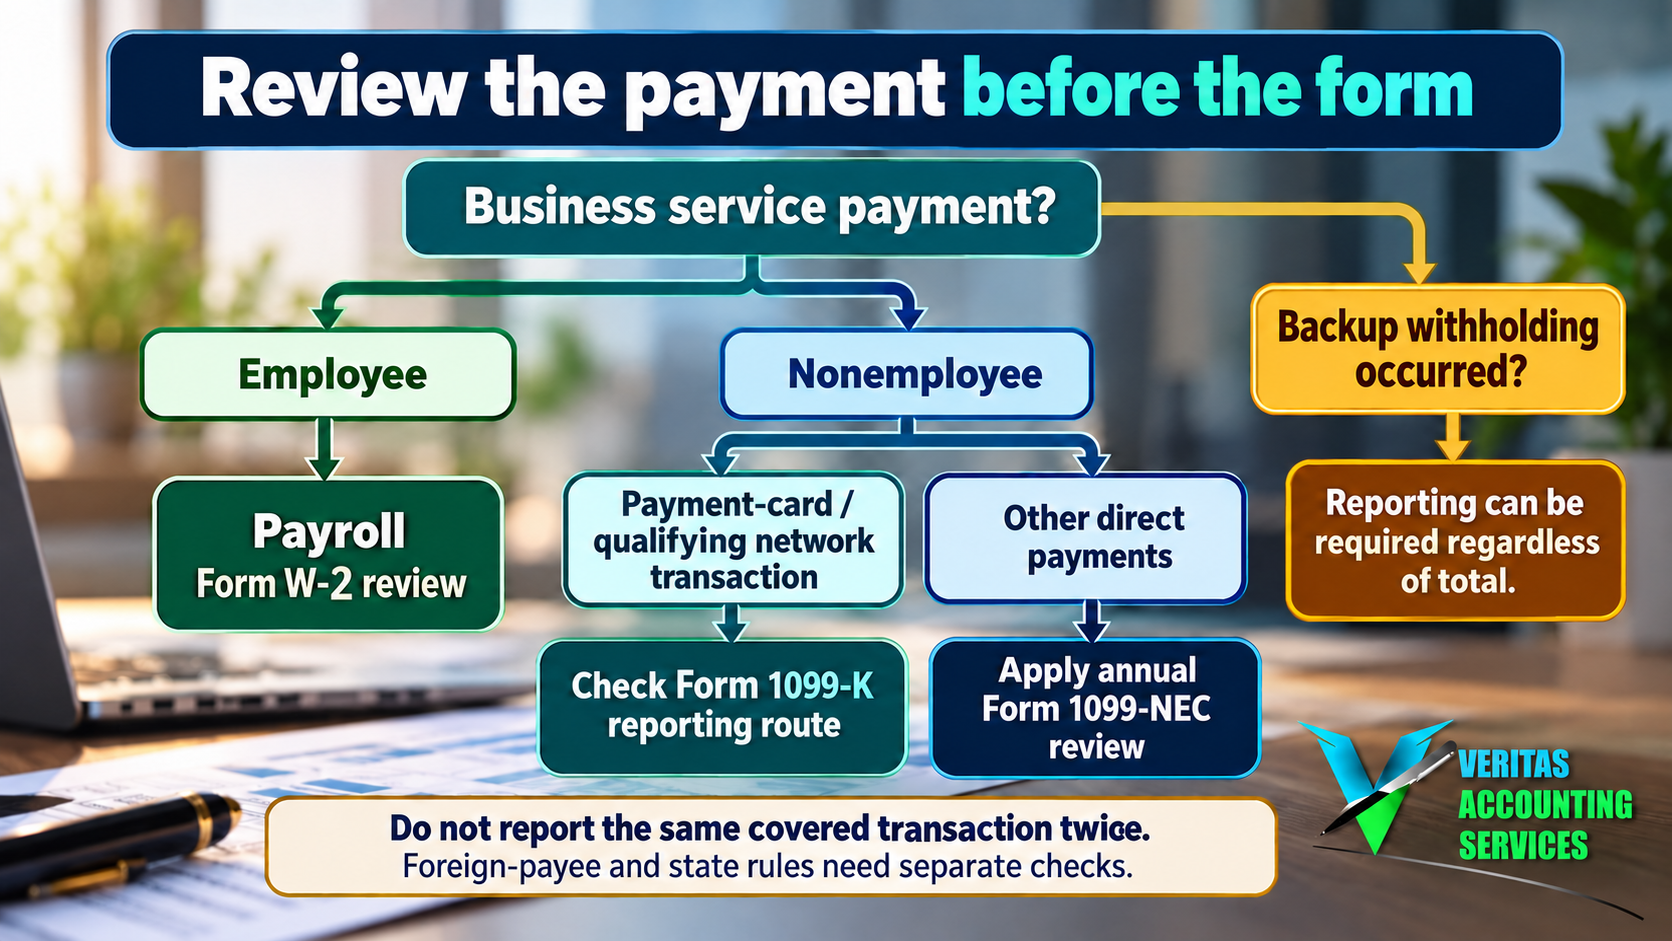
The way a vendor was paid can affect the reporting route. The IRS third-party-filer FAQs explain that a transaction reportable under both the ordinary business-payment provisions and the payment-settlement provisions should be reported only on Form 1099-K, not duplicated on Form 1099-NEC or Form 1099-MISC.

This distinction matters when preparing contractor tax forms from a vendor ledger. Credit-card transactions and qualifying third-party-network transactions need to be identified separately from direct payments. Do not add every payment route together and automatically issue a second form for transactions belonging to the settlement-reporting system.

An app’s name alone is not enough to classify the transaction. Check how the particular payment was processed and retain the relevant evidence. Not every electronic transfer is a qualifying network transaction, and an ordinary direct bank payment does not become one simply because it was initiated online.

For contractor tax forms, ask the preparer to resolve mixed-route cases. One vendor may receive checks, direct transfers and card payments during the same year. A useful report shows each route clearly and explains which amounts were included in the proposed nonemployee-compensation total.

Decision tree for reviewing a business service payment, separating employee payroll, nonemployee payment routes, Form 1099-K treatment and the backup-withholding exception.

4. Calculate the annual reportable total

Apply the threshold to the relevant annual total for each payee, not to each invoice individually. Several smaller service payments can reach the 2026 amount even when no single invoice is close to $2,000. Search for duplicate vendor records before deciding that two accounts represent two unrelated payees.

For contractor tax forms, reconcile the payment detail to the underlying books and payment evidence. Distinguish a draft bill from an actual payment, and flag refunds, corrections or unusual entries for the preparer. Do not silently net unrelated items together to produce a preferred reporting result.

The ordinary service-payment review can include parts and materials associated with the services, as the IRS’s reporting conditions explain. Do not assume that every amount labeled “materials” can simply be removed from a service contractor’s payment total. The actual transaction and applicable instructions determine treatment.

Track unresolved contractor tax forms separately. A vendor total near the threshold deserves a complete review, rather than a rounded estimate. Use exact supported figures and record the reason for any exclusion from the proposed filing total.

5. Check withholding, exceptions and state requirements

The threshold is not the only filing trigger. The IRS says Form 1099-NEC must also be filed for a person from whom federal income tax was withheld under the backup-withholding rules, regardless of the payment amount. This exception should remain visible when a spreadsheet filters out smaller vendor totals.

The IRS backup-withholding guidance describes situations involving missing or incorrect tax identification information and the current 24% rate. Applying the rules requires attention to the actual facts and notices. Do not treat a general statement about the rate as a complete instruction for handling a particular vendor.

Keep contractor tax forms connected to the withholding records, deposits and any related reporting obligations that apply. A missing name or identification number is not solved by typing a convenient substitute into the return. Escalate the problem and follow the applicable correction or withholding procedure.

Review state information-return obligations separately using the relevant state’s official guidance. A federal change does not prove that every state adopted the same threshold, filing channel or exception. Record who will make that check instead of assuming the federal submission settles it.

A worked annual-total example

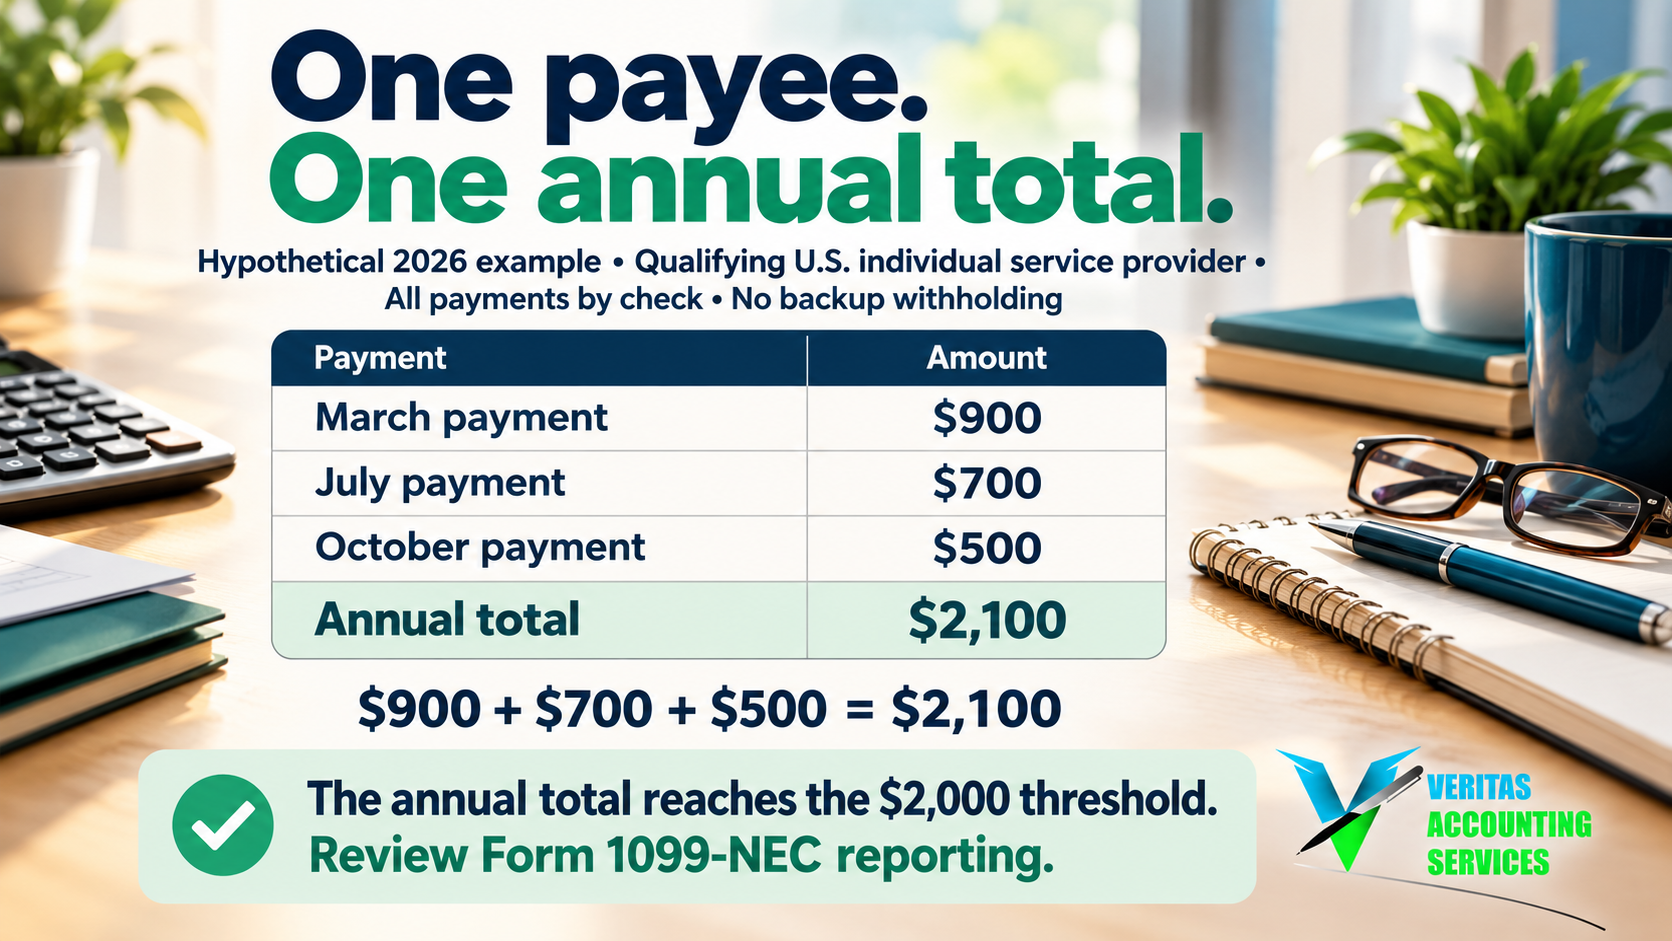
Suppose your business pays one US individual service provider by check during 2026. Assume the payments are qualifying business service payments, the payee information is correct, no exemption applies and no backup withholding occurred. These are illustrative assumptions, not details from a real client.

The business pays $900 in March, $700 in July and $500 in October. The annual total at that point is $2,100: $900 plus $700 plus $500. The amount reaches the general $2,000 reporting threshold even though each individual payment is below it.

A review of contractor tax forms should therefore consider Form 1099-NEC reporting for the full reportable amount, subject to the stated assumptions and any later activity. The threshold is not a deduction from the amount reported. You do not report only the $100 exceeding $2,000.

Hypothetical vendor ledger with three 2026 check payments of $900, $700 and $500, totaling $2,100 and reaching the $2,000 general reporting threshold.

Before finalizing contractor tax forms, change one fact: suppose part of the vendor’s activity was processed through a payment route covered by the settlement-reporting rules. You would need to separate that activity and review the remaining direct-payment total. The original example’s simple conclusion cannot be carried over without recalculating the relevant amount.

Change another fact: suppose backup withholding occurred. The separate reporting rule may apply regardless of the total. Examples are useful because they show the method, but they work only when the assumptions match the facts being reviewed.

Build a useful vendor review file

Start with a vendor list that has one clear record for each payee. Link invoices and payment details without scattering the same supplier across abbreviations, personal names and duplicate accounts. Ask the responsible person to resolve duplicates before exporting a filing list.

A practical file for contractor tax forms should show the following:

  • The payee name and the location of the securely stored tax documentation.
  • The service category and any classification issue needing review.
  • Payments by date, amount, payment year and payment route.
  • The proposed reportable total and the reason for each excluded amount.
  • Any backup withholding, exception, unresolved item or state-review assignment.

Do not include full tax identification numbers in a general management report. The preparer may need them in the secure filing process, but the owner can review progress using an internal vendor reference. This keeps the operational status useful without unnecessarily spreading sensitive data.

Review contractor tax forms alongside your expense records. Our business expense classification guide explains why consistent categories help the books. An expense label supports the review, but it does not replace the specific information-return rules.

Assign an owner to unresolved contractor tax forms. “Waiting for W-9” should identify who will follow up and the next action. A missing document discovered early is easier to investigate than one found while a final filing is being submitted.

Plan the filing process

Decide who prepares, reviews, submits and verifies contractor tax forms. Give the reviewer a clear version of the proposed data and a list of assumptions. Changes made after approval should return for review rather than quietly altering the final submission.

Contractor tax forms may need electronic filing even if the business has only a few contractors. The IRS explains that the ten-return e-filing threshold generally aggregates almost all covered information-return types, including Forms W-2. Counting only the Forms 1099-NEC can miss the relevant total.

Check the applicable calendar-year deadlines and any authorized extension or postponement against official guidance. Filing with the IRS and furnishing recipient statements are separate steps. Do not use a deadline for another form, or assume a paper process and an electronic process always have identical requirements.

For contractor tax forms, keep the submission confirmation and check the system’s acceptance or rejection result. A rejected file requires follow-up. Save evidence that recipient statements were furnished through an appropriate method, and document how corrections will be handled if an error is later found.

The IRS also describes its Information Returns Intake System, or IRIS, as a no-cost way to file Forms 1099 electronically. Check existing access and current instructions early. Choosing a free channel does not remove the need for complete data, review or confirmation.

Our business compliance calendar can help organize responsibilities and reminders. The calendar is an operating tool; the current official rules determine the actual due dates and filing requirements.

Common mistakes to avoid

The first mistake is carrying an old $600 filter into the 2026 payment review without checking the changed rule. The reverse mistake is using the 2026 threshold to reassess an earlier payment year. Contractor tax forms need a clearly labeled year before any software setting is applied.

The second mistake is deciding from the invoice amount alone. Aggregate the relevant payments to the payee, resolve duplicate vendor records and verify the payment route. A tidy-looking summary can still be wrong if its underlying categories are incomplete.

The third mistake is treating the absence of a form as proof that income is not taxable. Information reporting and income taxation have different purposes. A contractor’s own books remain important even when no information return is required from a particular customer.

The fourth mistake is assuming that software validates the legal conclusion. Software can populate contractor tax forms from the data supplied; it cannot determine an unresolved worker relationship or explain an unidentified payment route. Review the decisions before the upload, not only the spelling afterward.

Finally, do not delete records merely because the vendor falls below the general threshold. The expense, payment, classification and withholding facts can still matter. Our bookkeeping and tax records guide explains the value of a reliable supporting file.

Frequently asked questions

Is the 2026 threshold $600 or $2,000?

For the general federal Form 1099-NEC payment threshold discussed here, the IRS identifies $2,000 for payments made in 2026. The $600 amount applies to payments made before 2026. Other conditions, exceptions and payment categories still need review.

Do contractor tax forms use each invoice or the annual total?

Use the relevant annual reportable total for the payee. Multiple smaller payments can reach the threshold. Check that the total includes the correct payments and excludes transactions belonging to a different reporting route for a supported reason.

Is only the amount above the threshold reported?

No. In the hypothetical $2,100 example, reaching the threshold triggers a review of reporting the full reportable amount. The $2,000 threshold is not an allowance deducted from the reported payment total.

Can a smaller payment still require a form?

Yes. The IRS identifies reporting regardless of amount when federal income tax was withheld under the backup-withholding rules. Other facts can also require separate analysis. Do not rely on a threshold-only filter for contractor tax forms.

Does every electronic payment belong on Form 1099-K?

No. When preparing contractor tax forms, confirm the actual transaction and whether the payment-settlement reporting provisions apply. A transfer being electronic or appearing in an app is not, by itself, a complete answer. Avoid duplicating transactions covered by the Form 1099-K reporting route.

What should I do if a vendor’s information is incomplete?

Request the appropriate documentation through your secure process and flag the issue for review. Do not invent an identification number or presume an exemption. Resolve any applicable withholding and filing requirements before treating the file as ready.

Conclusion

The 2026 reporting threshold is an important change, but it is only one part of preparing contractor tax forms. Check the worker relationship, payee details, payment route, annual reportable total and any withholding or state requirements before deciding what to file.

The useful next step is to reconcile the vendor list now and assign the unresolved items. Clear source records and a reviewed filing process help turn a year-end scramble into a manageable compliance task.

This article provides general federal tax information reviewed October 28, 2026. It is not individualized advice. Confirm the payment year, current applicable instructions, special rules and state requirements before acting.

GET IN TOUCH

Schedule a FREE Call

Contact us

Connect on our Socials!

A sculptural teal income wave passes four navy calendars toward an emerald reserve vessel, illustrating uneven income and tax planning.

Your Simple Guide to Estimated Tax Mistakes With Uneven Income

Estimated tax payments deserve a closer look when your business earns most of its profit in a few busy months. Dividing an annual estimate into equal installments is one approach, but an annualized income calculation may better reflect when income arose. It does not automatically lower your final tax bill or erase a missed payment.

The IRS’s October 23, 2026 year-round planning reminder encourages small-business owners and self-employed taxpayers to review estimated tax payments before filing season. That reminder is timely guidance to review your position, rather than a new exemption or a new annualization rule.

This guide focuses on individual federal income tax planning for owners with uneven income. Corporate estimates, special farming and fishing rules, nonresident situations and state requirements need their own review. The practical goal is to bring your adviser a clear income timeline, an accurate payment history and enough information to compare methods.

Table of contents

Why income timing matters

A business can finish the year with healthy profit even though its first few months were quiet. A wedding photographer, summer repair business or consultant receiving a large project payment may have a very different income pattern from an owner receiving steady monthly fees.

Federal income tax generally works on a pay-as-you-go basis. That means the timing of tax paid during the year matters alongside the final annual total. A large payment near year-end may reduce an outstanding balance, but it does not necessarily remove a penalty for an earlier installment.

The IRS explanation of underpayment penalties says people receiving income unevenly may be able to vary installments using the annualized method. The word “may” matters: the result depends on the calculation and the records behind it.

Before changing estimated tax payments, separate three questions. What is your expected final tax? What amount needs to have been paid by each relevant installment date? How much cash can the business and household set aside to meet those obligations? The answers are connected, but they are not interchangeable.

Understand estimated tax payments

For many individual owners, these payments cover income that is not adequately covered by withholding. The calculation can include self-employment tax as well as income tax. A sole proprietor’s business results are only part of the picture if the household also has wages, investment income or other taxable items.

The IRS estimated tax overview describes who may need to pay and how to estimate an amount. Do not decide that no payment is needed simply because your business has no employees or you have not received an information return.

For most individuals, the general underpayment protection compares 90% of current-year tax with 100% of prior-year tax, using the smaller applicable amount. The prior return must cover a full twelve months. Higher-income taxpayers generally substitute 110% for the prior-year percentage when prior-year adjusted gross income exceeds $150,000, or $75,000 for married filing separately.

Other exceptions and special rules apply. For example, the IRS describes a general exception where tax owed after withholding and refundable credits is less than $1,000. These are screening rules, not a substitute for completing the relevant worksheet. A prior-year comparison also does not guarantee that the remaining tax bill will be small.

If the required protection amount is lower than your expected final liability, plan for the difference after estimated tax payments. Keeping a cash reserve for that balance helps prevent a mistaken assumption that “penalty protection” means “nothing more to pay.” Our discussion of tax savings and cash flow explains why the two need separate attention.

Regular and annualized methods

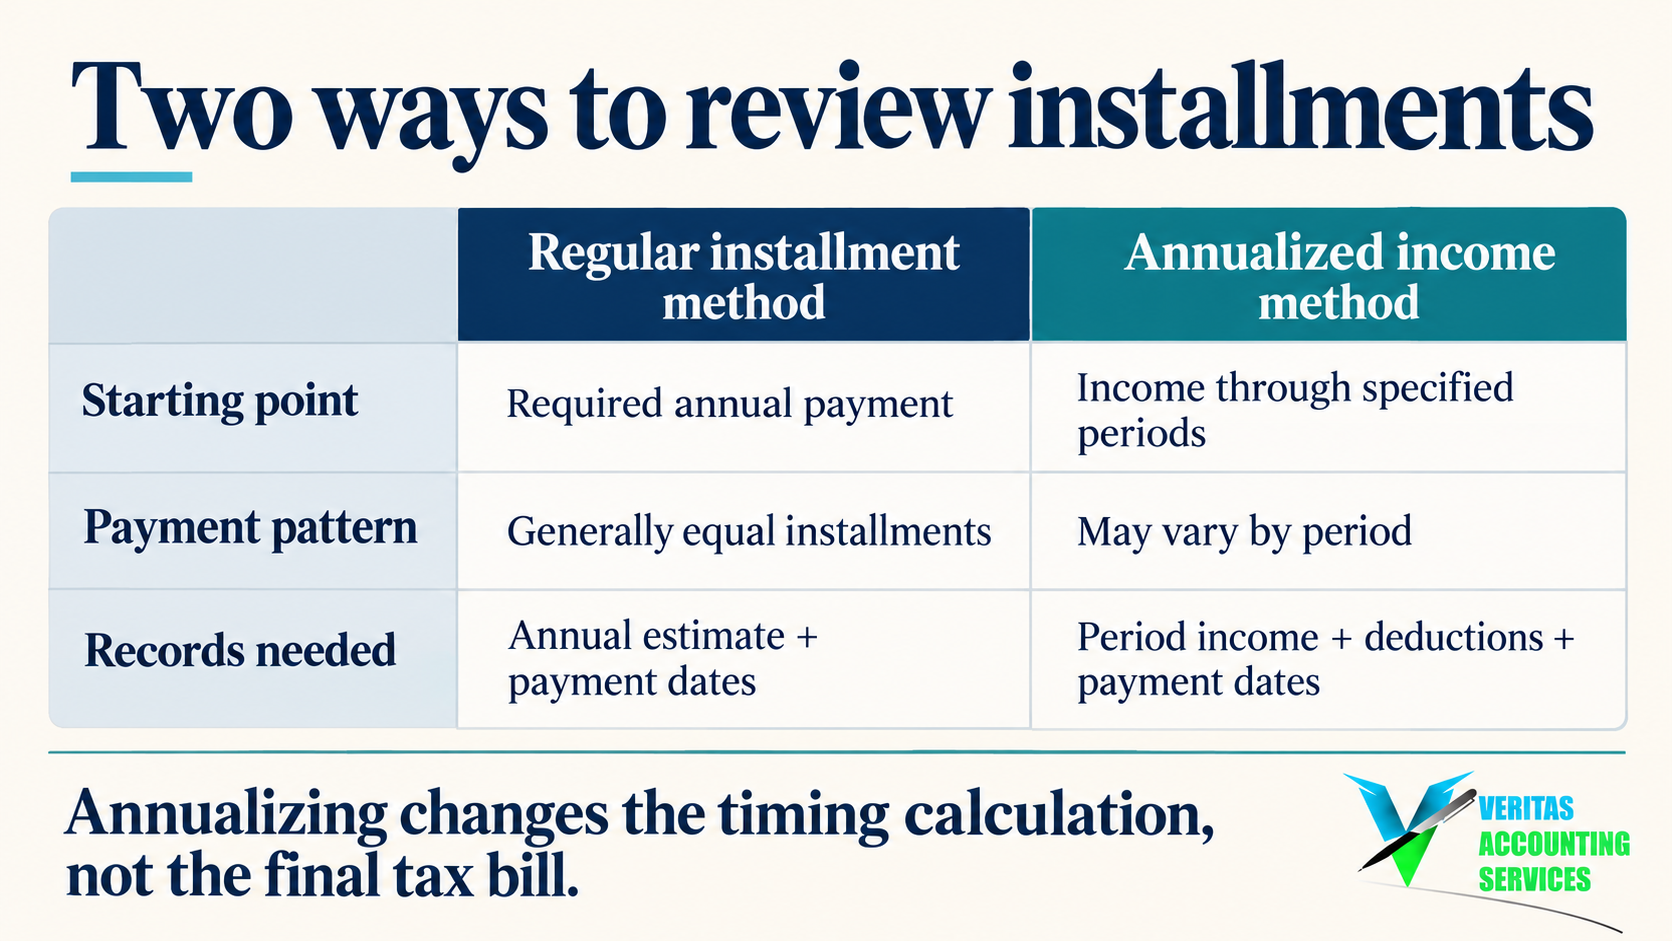
Under the regular installment method, the required annual payment is generally divided into equal installments. This can be straightforward when income is reasonably stable or a reliable prior-year amount provides the relevant benchmark. Equal payments are not inherently wrong for a seasonal business; compare the actual results before choosing a more complicated approach.

The annualized income installment method looks at income and relevant deductions through specified periods. It converts those period results into an annualized calculation and works through the applicable tax worksheet. An owner with little early income may have a lower required early installment than under a simple equal-payment approach.

The 2026 edition of Publication 505 includes the annualized estimated tax worksheet for current-year planning. It accounts for much more than multiplying business revenue by a flat percentage. Credits, deductions, self-employment tax and other items can affect the answer.

Comparison of regular estimated tax payments with the annualized income method, showing their starting points, payment patterns and record requirements.

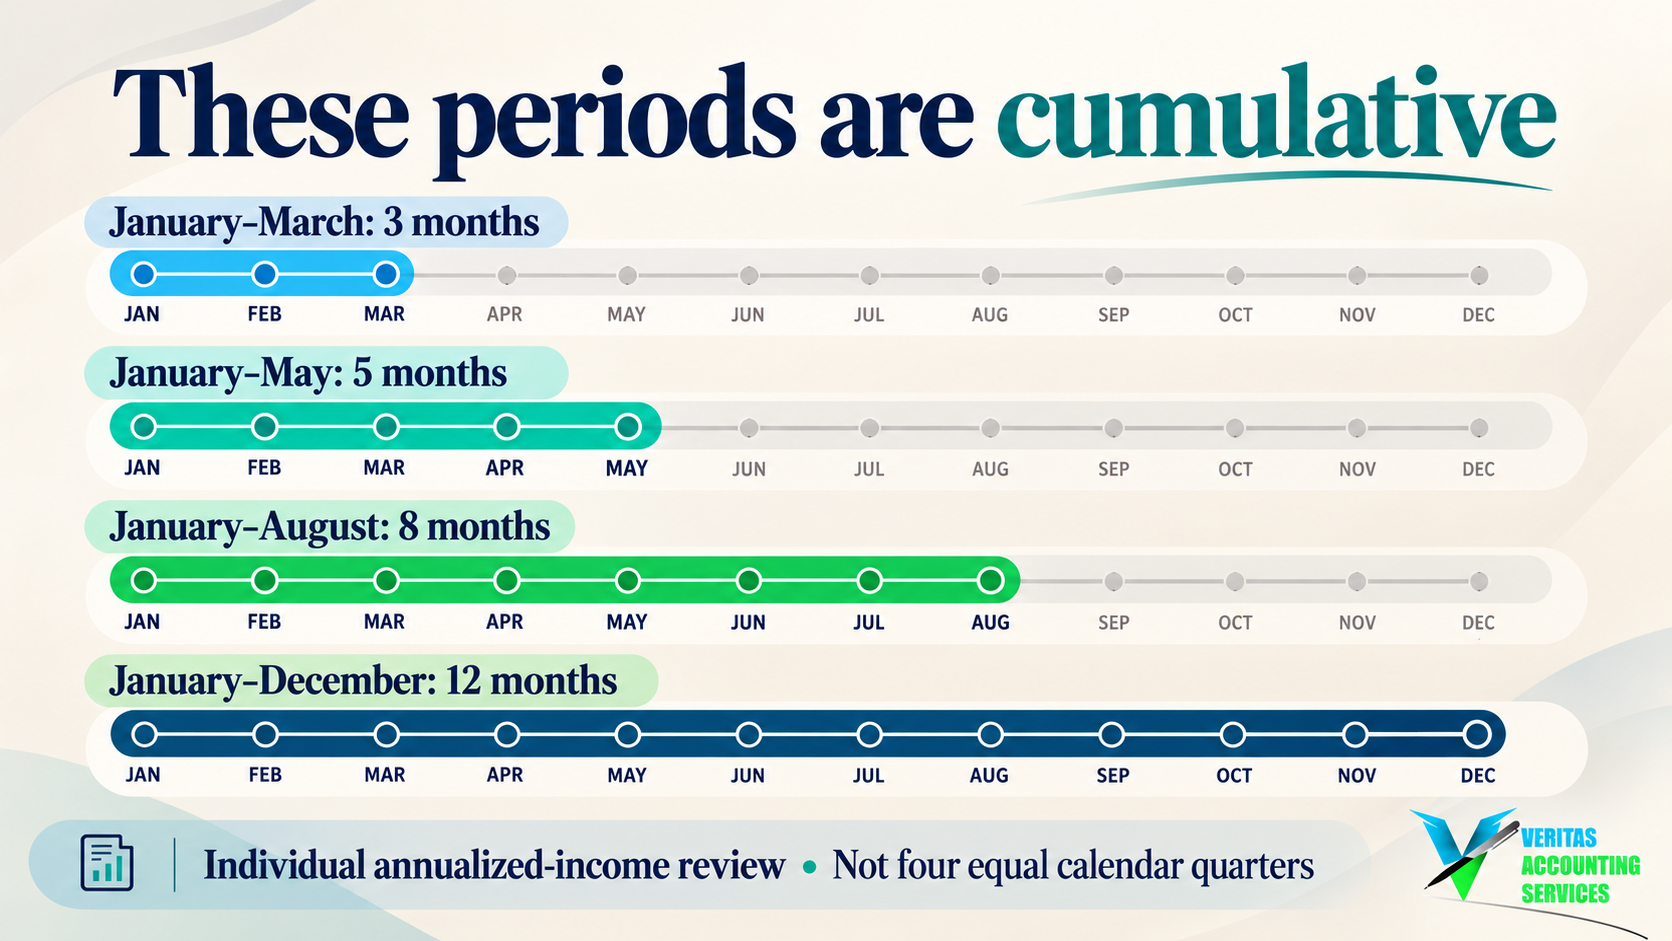
For individual calendar-year annualization, the cumulative periods end in March, May, August and December. These are not four equal calendar quarters. A report for April through June alone cannot replace the cumulative January-through-May information needed for the second annualized period.

When evaluating estimated tax payments, keep the period covered and the payment due date in separate columns. This avoids using a familiar quarter-end date for the wrong purpose. Check the current year’s official schedule, along with any applicable postponement, before instructing a payment.

Cumulative annualized-income periods running from January through March, May, August and December, rather than four equal calendar quarters.

Annualizing estimated tax payments does not let you select only the most favorable month. It is a structured method with cumulative calculations and interaction between installments. Prior-period differences can affect later required amounts, so the whole sequence needs to be reviewed together.

Five practical checks

1. Identify whose tax you are reviewing

Start with the taxpayer and return involved. A single-owner business’s bank account, a partnership’s books and an individual owner’s return are different records. An owner’s federal individual estimated tax payments should not be confused with payroll deposits or a company’s separate corporate income tax obligation.

If you own a partnership or S corporation, include your share of relevant pass-through items in the review. A cash distribution does not by itself establish the taxable income for the period. Ask the preparer which interim information is needed rather than substituting money withdrawn from the business.

For a household filing jointly, coordinate estimated tax payments with both spouses’ other income and withholding. Reviewing one business in isolation can miss a large part of the actual annual liability. Keep private household details in the secure adviser file, rather than in routine team reports.

2. Put income into the correct periods

Reconcile your books before extracting the cumulative reports. Confirm the tax accounting method and any adjustments your adviser needs. Bank deposits can include loans, transfers and owner contributions, so a bank balance or deposit total alone is not a taxable-profit calculation.

For estimated tax payments, the purpose is to identify the income and deductions properly attributable to each required period. Do not move an item into a later month merely to produce a smaller installment. Preserve the underlying transaction dates and let the applicable tax rules determine treatment.

Flag unusual items separately. A large asset sale, investment gain, cancellation of debt or change in the business can require analysis beyond the ordinary operating report. A short explanation and supporting document are more useful than burying the item in a miscellaneous account.

3. Reconcile payments and withholding

List federal estimated tax payments with their actual dates, amounts, tax year and confirmations. Check whether a prior-year overpayment was applied forward. A payment recorded in the bookkeeping file should also be matched to the available payment evidence, rather than assumed to have reached the intended taxpayer’s account.

Withholding has its own timing rules. It is generally treated as paid evenly through the year for the underpayment calculation, unless actual withholding dates are used under the applicable rules. Do not automatically treat an estimated payment and additional wage withholding made on the same day as identical for penalty purposes.

If withholding may be adjusted, review the household’s facts and payroll arrangements before acting. This is not permission to run an unsupported payroll entry or relabel an owner withdrawal as wages. The adviser should compare lawful options and their practical deadlines.

4. Compare the calculations before changing cash plans

Ask for a comparison of regular installments, any applicable prior-year protection and annualized results. The calculation should show required amounts, amounts paid and remaining exposure by period. The lowest-looking percentage on a summary sheet may not be the method that applies to your facts.

Once estimated tax payments have been calculated, translate them into a cash forecast. Include operating costs, debt payments, owner needs and the remaining expected tax balance. A separate reserve can make the obligation visible without suggesting that moving money between accounts itself satisfies a tax payment.

Revisit estimated tax payments and the forecast after a major change in income. A strong autumn can alter the full-year picture, while a project delay can change available cash. Our business compliance calendar can help organize responsibility and reminders around the agreed review process.

5. Plan the filing support and state review

Current-year planning and the eventual return filing are linked. Keep the worksheet used to determine estimated tax payments, the supporting period reports and the payment confirmations together. Explain any later change in the figures so the preparer can reconcile the planning file with the final return.

Publication 505 states that using the annualized income installment method for estimated tax payments requires filing Form 2210 with the 2026 return. Its Schedule AI procedure applies across all installment dates when used for the penalty calculation; do not present just the most favorable column in isolation.

The currently available Form 2210 instructions explain the annualized method and the situations requiring the form. The version reviewed for this article is labeled 2025; it supports the procedural background, not an assertion that the final 2026 filing instructions have already been released. Use the correct final tax-year forms when preparing the return.

State estimated tax payments require a separate check against the relevant state’s official guidance. Do not copy a federal result, percentage, timing assumption or exception into a state worksheet without verifying it. Multistate owners may need more than one separate review.

A seasonal business example

Suppose a calendar-year sole proprietor has an illustrative $10,000 of business profit from January through March, another $15,000 in April and May, another $35,000 from June through August, and $60,000 during September through December. The full-year business profit is $120,000.

The cumulative business figures are therefore $10,000, $25,000, $60,000 and $120,000. The second figure includes the first period; it is not just the $15,000 earned during April and May. Those cumulative amounts are a useful starting file for the adviser.

This example deliberately does not turn the four profit figures into estimated tax payments. The owner’s filing status, other income, deductions, credits, self-employment tax, prior-year tax and withholding have not been supplied. Applying an invented flat rate would make the example look precise while leaving out facts needed for a valid answer.

What can the owner learn without that missing information? The business has an uneven income pattern, a cumulative reporting file is necessary, and a comparison of methods is worth requesting. The example establishes a review question, rather than promising a particular saving or penalty reduction.

If the adviser finds lower early estimated tax payments under annualization, later installments still need attention. The money retained earlier is not automatically permanent extra spending money. Build the later payment and final balance into the forecast before committing to equipment or additional owner withdrawals.

Build a useful review file

Give the adviser a clean package instead of a collection of screenshots. Begin with the prior-year return and the current-year cumulative reports covering the required periods. Add a short list of changes in household income, filing circumstances and business activity that may affect the result.

For estimated tax payments, the most useful supporting records usually include the following:

  • Reconciled income and expense reports, with their exact coverage dates.
  • A clear description of the accounting method and unresolved adjustments.
  • Pass-through estimates or other relevant owner income information.
  • Withholding details and federal payment confirmations.
  • Unusual transactions, expected remaining income and important assumptions.

Keep this file secure. It may contain tax identifiers, account information and personal household details. Give the operating team only the information needed to manage cash and deadlines; the complete return package belongs in the agreed secure process.

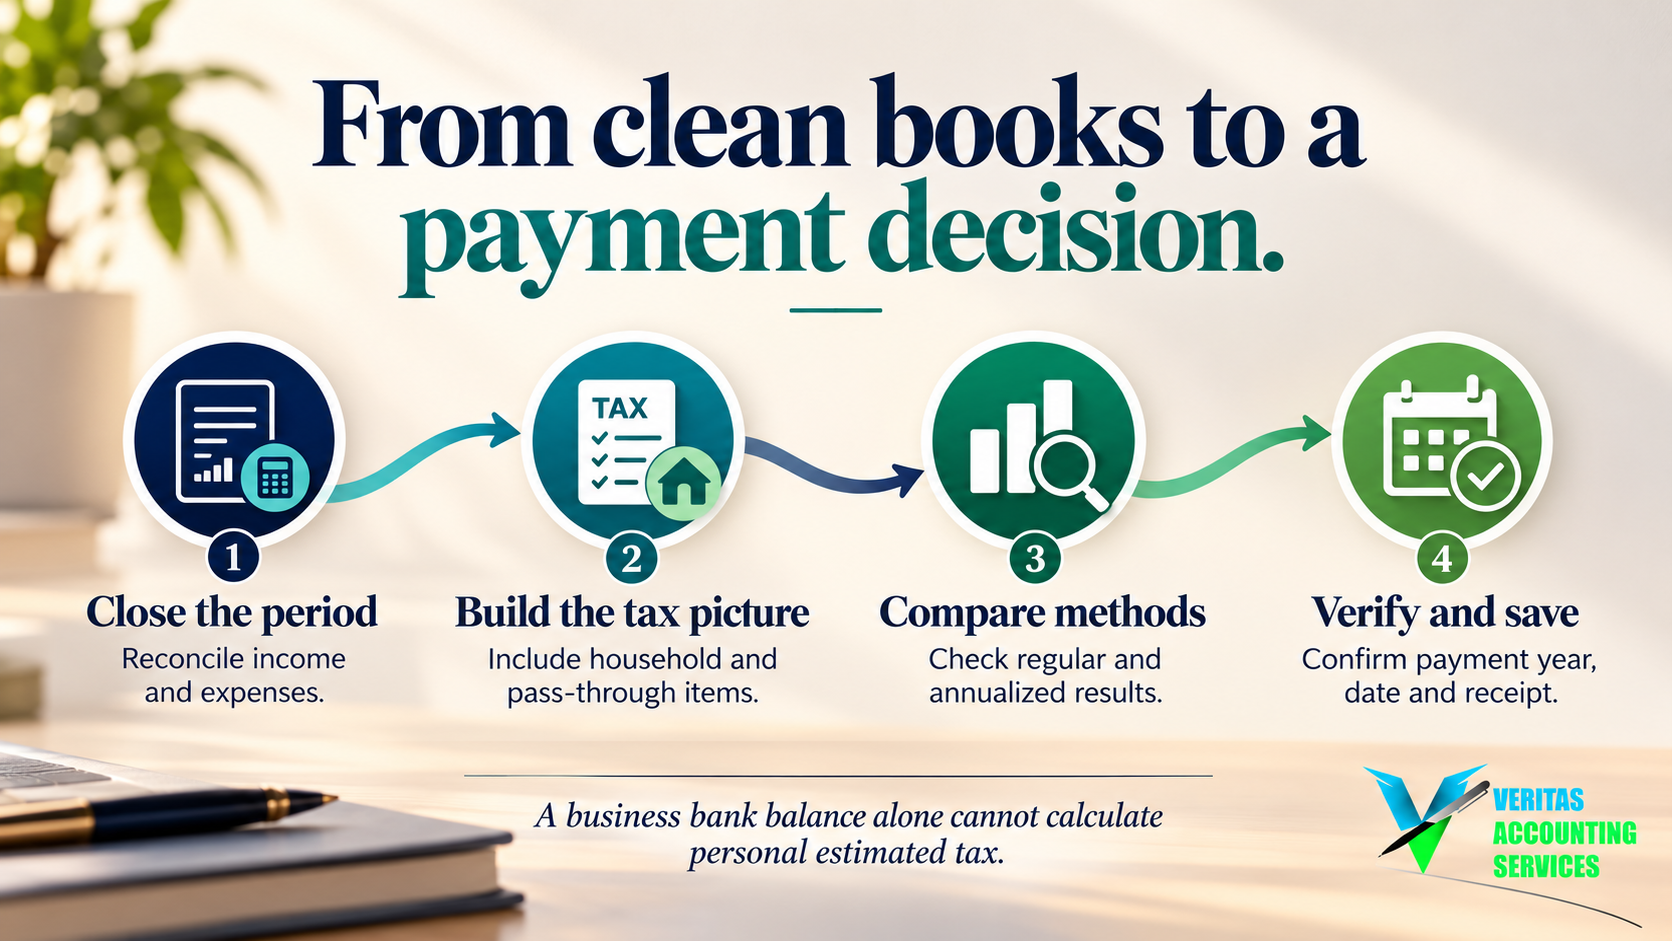
Workflow from reconciled period books through a complete tax picture and method comparison to a verified payment and saved receipt.

A simple review log for estimated tax payments can record the date, reports used, assumptions, person responsible and next review trigger. Mark forecasts as forecasts and keep the final calculation distinct from an earlier draft. That helps everyone understand why a payment instruction changed.

Good records support the comparison, but software cannot resolve missing facts by itself. Our guide to bookkeeping and tax records explains the connection between reconciled information and a more reliable tax handoff. The objective is fewer unanswered questions, not a larger stack of documents.

Avoid common mistakes

The first mistake is treating a late catch-up payment as a complete repair. The IRS calculates underpayment separately for required installments. Paying more now may be sensible, but review earlier periods rather than assuming they have disappeared from the calculation.

The second is confusing revenue, profit and taxable income. Revenue does not subtract business expenses; bookkeeping profit may still need tax adjustments; personal taxable income includes other items. Estimated tax payments need the appropriate tax picture, not whichever number is easiest to find.

The third is assuming annualization always wins. A regular method may be simpler or already provide the relevant protection. Compare the result and the recordkeeping effort before adding complexity that does not improve the decision.

The fourth is confusing the reserve with the payment. A transfer to a savings account is an internal cash-management action. The actual payment requires the correct taxpayer, tax year, payment designation and completion evidence.

Finally, do not ignore an IRS notice because the spreadsheet looks right. Compare the notice with filed information and verified estimated tax payments. Our guide to responding to an IRS notice can help frame that separate task, but the notice’s actual instructions and response deadline remain important.

Frequently asked questions

Can estimated tax payments vary during the year?

Yes. When income is uneven, the annualized income installment method may produce different required amounts for different periods. The result must come from the applicable calculation. It is not a general permission to pay only in profitable months or postpone every obligation until the year ends.

Does annualizing reduce my final income tax?

It addresses estimated tax payments and the installment calculation, including potential underpayment exposure. It does not create a deduction or credit and does not by itself reduce the final annual income tax. Review the full-year liability separately from the timing of payments.

Are the annualized periods the same as calendar quarters?

No. For the individual calendar-year worksheet discussed here, they are cumulative periods ending March, May, August and December. Use the specific worksheet and year that apply to the taxpayer. Do not substitute ordinary quarterly profit reports without checking their coverage.

Should I use last year’s return to calculate everything?

The prior-year amount can be an important benchmark, subject to the applicable conditions and higher-income rule. Current-year changes still matter for forecasting the ultimate balance. An installment protection calculation and a realistic final-tax forecast serve different purposes.

What if my business is an LLC?

The LLC label alone does not identify its federal tax treatment. Confirm how the entity is taxed and whose obligation is being calculated. Estimated tax payments for an individual owner should not be substituted for a separate corporate tax or payroll obligation.

Should I wait for filing season to review estimated tax payments?

Review the position while there is still time to make informed payment and cash decisions. Preserve the period records now and use the final applicable forms at filing. A later return preparation appointment does not make earlier payment timing irrelevant.

Conclusion

Uneven business income calls for a better timeline, rather than a guess based on the year-end bank balance. Reconcile the required cumulative periods, assemble the wider tax picture and ask for a comparison of methods before changing estimated tax payments.

The useful next step is practical: gather period reports and payment confirmations, identify unresolved items and set a review date with your adviser. Keep the final liability, installment timing and available cash visible as separate parts of one plan.

This article provides general federal tax information reviewed October 27, 2026. It is not individualized advice. Confirm the applicable tax year, entity, current forms, special rules and state requirements before acting.

GET IN TOUCH

Schedule a FREE Call

Contact us

Connect on our Socials!

Teal ribbon untangling into a clear path and check mark, introducing correction of retirement plan administration mistakes.

Your Simple Guide to Retirement Plan Mistakes and New Rules

Retirement plan corrections can help a business address an administration mistake while protecting the plan’s tax-favored treatment. The first step is to identify the error, preserve the records and choose an appropriate correction route with your plan adviser.

There is a timely reason to review your process. On October 22, 2026, Treasury and the IRS announced updated employer-plan correction guidance and a separate new IRA correction program. These programs have different start dates and purposes. An owner should not treat the announcement as permission to fix every problem with a simple payroll adjustment.

This guide explains the announcement and offers five practical checks for US small-business employers. It focuses on organizing a sound response rather than calculating an individual employee’s corrective contribution.

Table of contents

What changed in October

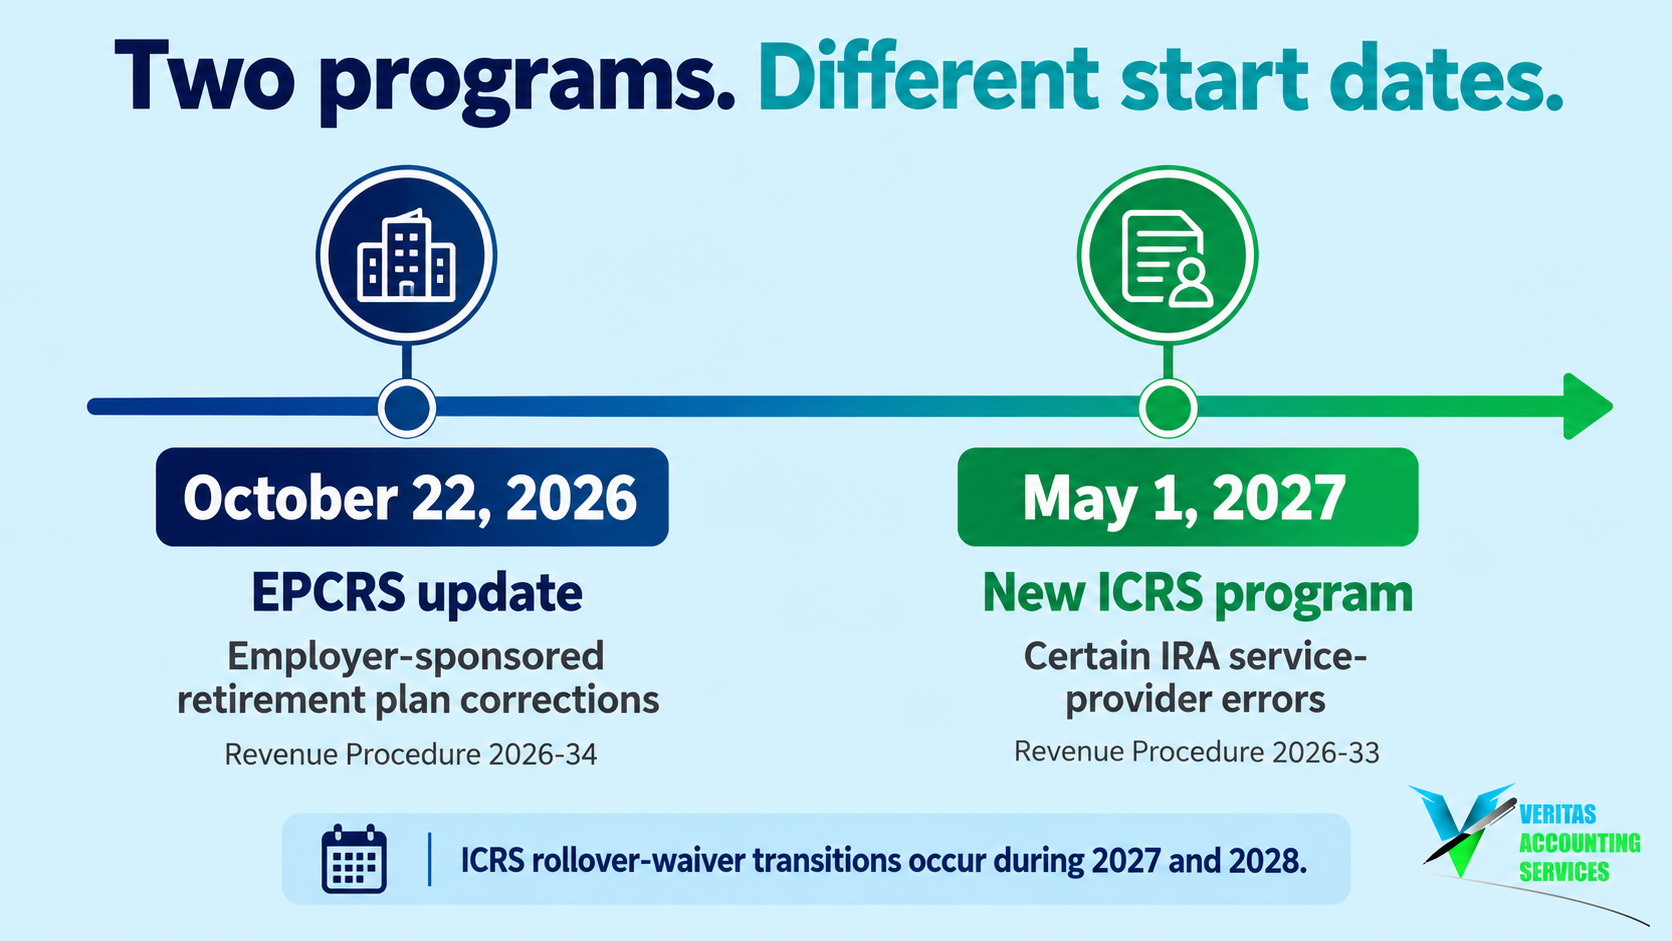
The IRS announcement dated October 22, 2026 identifies two separate procedures. Revenue Procedure 2026-34 updates the Employee Plans Compliance Resolution System, or EPCRS, generally effective October 22, 2026. It replaces Revenue Procedure 2021-30 and consolidates subsequent changes.

For employers, retirement plan corrections under EPCRS concern eligible employer-sponsored arrangements, including qualified plans, 403(b) plans, SEPs and SIMPLE IRA plans. Availability still depends on the particular failure and program requirements.

Revenue Procedure 2026-33 establishes the IRA Compliance Resolution System, or ICRS, effective May 1, 2027. It addresses certain eligible inadvertent failures caused by service-provider errors. Rollover-waiver requests will transition into that system during 2027 and 2028; existing qualifying automatic-waiver and self-certification routes remain available.

These are issued procedures, not merely proposed rules. However, the publication date does not make the future IRA program immediately available. The guidance on retirement plan corrections does not create a new blanket deduction or change every plan’s contribution limit.

Timeline for retirement plan corrections showing the October 22, 2026 EPCRS update and the May 1, 2027 start of ICRS.

How retirement plan corrections work

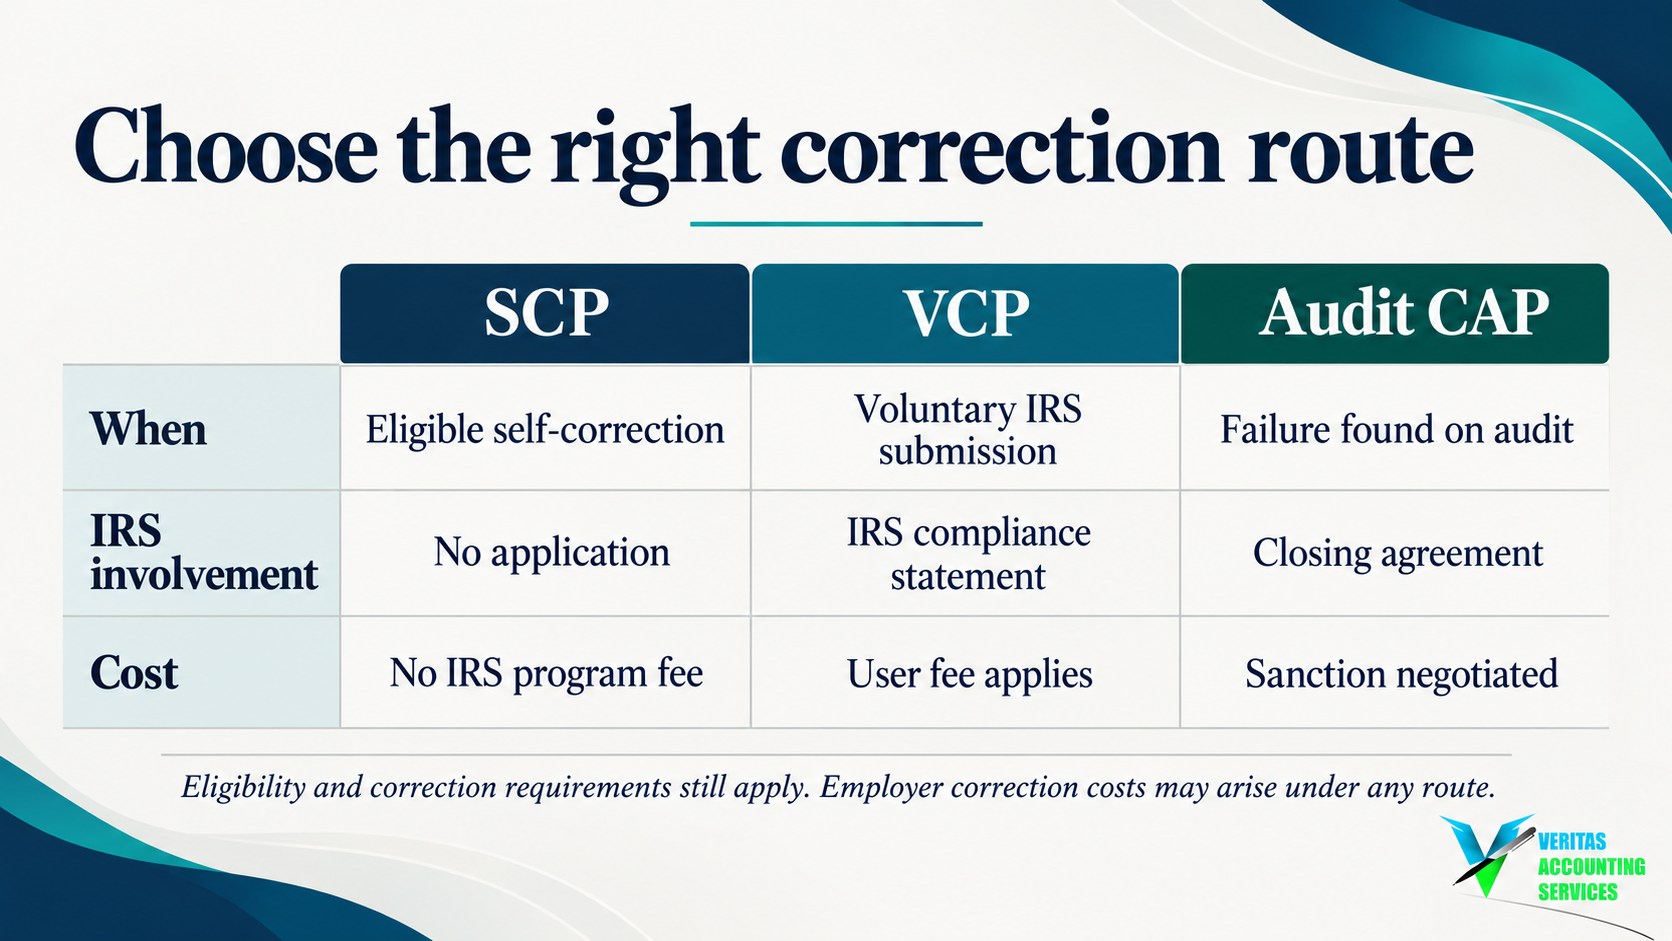
Think of EPCRS as a framework for addressing eligible failures, with different levels of IRS involvement. The main routes are summarized below, based on Revenue Procedure 2026-34.

RouteBasic approachIRS program cost
Self-Correction Program, or SCPCorrect an eligible failure without an IRS applicationNo IRS program fee or sanction
Voluntary Correction Program, or VCPSeek IRS approval through a voluntary submission before examinationUser fee applies
Audit Closing Agreement Program, or Audit CAPResolve a failure identified during examination through a closing agreementSanction applies

The distinction matters when budgeting for retirement plan corrections. No IRS program fee does not mean no employer expense: contributions, earnings adjustments or professional work may still be necessary.

Self-correction has conditions. Established compliance practices matter; simply possessing a plan document does not establish that those practices existed. Eligible inadvertent failures must be corrected within a reasonable period, with special rules and exclusions. Examination can also affect availability.

Avoid assuming that every mistake qualifies or that an IRS correction resolves obligations under other laws. Ask your adviser to identify the route and the specific authority supporting it before funds move.

Comparison of SCP, VCP and Audit CAP covering when each route applies, IRS involvement and program costs.

Five checks before making a correction

Use these checks to prepare for retirement plan corrections. They are a practical review sequence, not a substitute for the correction rules governing your particular plan.

Check the plan and the affected period

Confirm whether the arrangement is a 401(k), SEP, SIMPLE IRA or another plan. Gather the signed document, adoption agreement and relevant amendments. Identify the plan year and the payroll periods under review.

Write a short problem statement: what should have happened, what actually happened and when someone discovered the difference. Separate confirmed facts from questions. A clear description lets the administrator assess the problem without reconstructing it from scattered emails.

Check who may be affected

Compare the employee roster with plan participation records. Look at hire dates, service information, elections and changes in employment status. Do not assume that someone working reduced hours is automatically excluded.

The IRS guide on excluded eligible employees emphasizes checking plan eligibility provisions and accurate employee information. The remedy for a missed opportunity to defer can involve an employer corrective contribution; it should not be guessed from a single payroll figure.

For retirement plan corrections, one employee’s complaint can be a starting point for checking whether the same configuration affected others. Review the relevant population instead of closing the issue after the first account is repaired.

Check payroll against the actual plan terms

A payroll system’s default settings may not match the plan’s definition of compensation. Before calculating retirement plan corrections, compare relevant pay codes, employee elections, calculated amounts and plan records. Investigate bonuses or irregular payments separately where needed.

Our discussion of avoiding payroll pitfalls explains why a repeatable payroll process matters. Here, the immediate goal is a documented reconciliation that a plan specialist can use to determine the correct response.

Check the route and timing with the adviser

Ask the administrator which method applies to the retirement plan corrections, whether IRS approval is needed and which deadlines or notices govern it. Record the discovery date accurately. Do not treat a general program summary as a universal deadline.

If an examination notice has arrived, share it promptly. Retirement plan corrections require a response based on the actual status of the plan and employer. A vague intention to deal with a problem later is a poor operational plan.

Check funding, responsibilities and completion evidence

Prepare a correction budget showing amounts confirmed by the adviser, amounts awaiting calculation and professional fees. Assign responsibility for calculations, funding, employee communications and evidence of completion.

Add the agreed actions to your business compliance calendar. Give each task an owner and a review date. Mark it complete when supporting evidence is saved, rather than when someone sends an instruction to another provider.

A payroll example

Suppose a small business discovers that a pay code was omitted from the compensation data sent for plan administration. The owner sees a difference between payroll and the administrator’s worksheet and wants to transfer the apparent shortfall immediately.

Start by defining the difference. Assume, purely for illustration, that one employee’s review shows the following:

Reconciliation itemIllustrative amount
Pay included in the worksheet$48,000
Additional pay requiring review under the plan terms$4,000
Total pay to investigate$52,000

The arithmetic is $48,000 plus $4,000, or $52,000. It does not establish that all $52,000 is plan compensation, nor does it calculate a corrective contribution. Those answers depend on the document and the facts.

For retirement plan corrections, give the adviser the underlying payroll register, pay-code description, election records and original worksheet. Ask whether the issue affected deferrals, employer contributions, testing or reporting, and whether other employees require review.

Well-documented retirement plan corrections produce a useful decision trail. This approach also avoids turning an unexplained difference into a second error through an unsupported transfer or a retrospective payroll deduction.

Why deposit timing needs separate attention

Money withheld from employees deserves a separate check. The Department of Labor’s retirement-plan FAQ explains that employee contributions must be deposited as soon as they can reasonably be separated from the employer’s assets. A seven-business-day safe harbor applies to qualifying small plans with fewer than 100 participants.

Do not use the general outside limit discussed in that FAQ as a routine waiting period. If deposits appear late, ask about the applicable Labor Department obligations as well as the IRS tax issues. EPCRS does not automatically resolve ERISA fiduciary violations.

Operationally, compare the payday, withholding amount, transfer initiation and actual plan receipt. A bank debit alone may not answer when the plan received or allocated the money.

When planning retirement plan corrections, maintain a separate cash forecast for required employer funding. Do not treat employee withholdings as working capital. Tracking the issue openly makes the business’s available cash easier to understand.

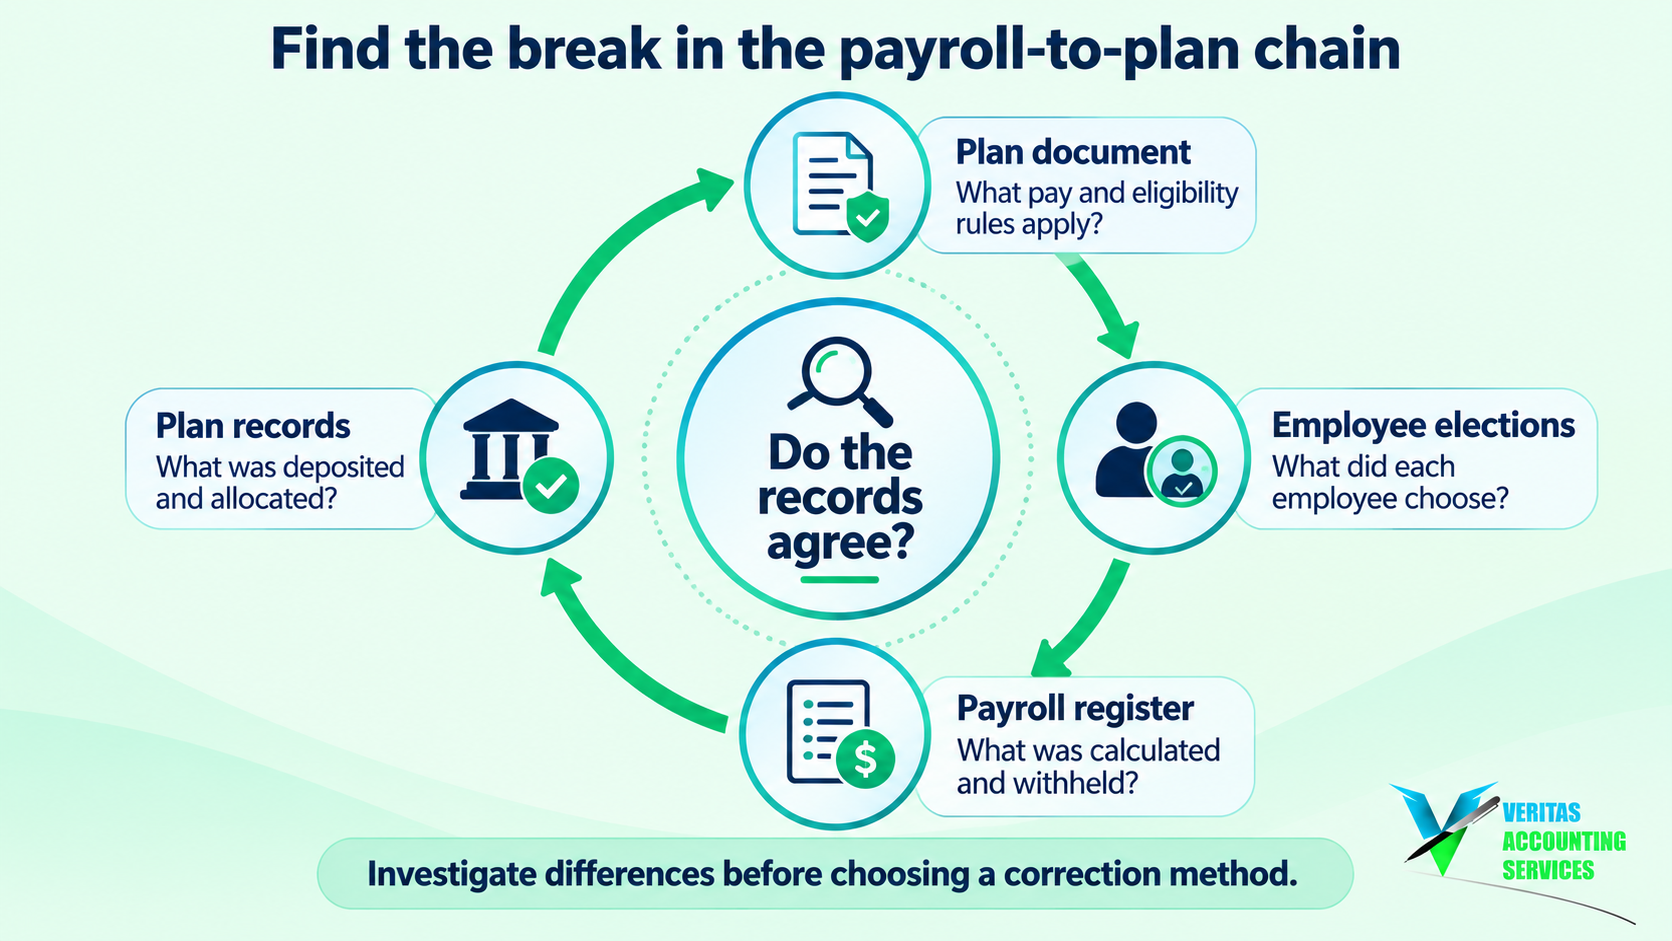
Circular reconciliation diagram linking plan documents, employee elections, payroll registers and plan records around the question Do the records agree?

Build a useful correction file

Keep a controlled folder for retirement plan corrections with a short index. Include the original discrepancy, relevant documents, adviser instructions, calculation versions, approvals, payment confirmations and any required communications.

Save both the original report and the corrected report. Overwriting the first spreadsheet can make it harder to explain what changed. Label working estimates clearly so a draft amount is not mistaken for an approved funding instruction.

This is a practical extension of good bookkeeping and tax records. Source records support the decision; the final reconciliation explains how the team reached it. Give payroll, accounting and the plan administrator a consistent version to work from.

After completing the work, identify the process change that will prevent recurrence. For example, require a plan-compensation review when a new pay code is introduced, or a roster review when employees change status. Our article on systems for a growing workforce discusses why informal handoffs become harder as a business expands.

The best outcome from retirement plan corrections includes both a resolved issue and a clearer routine for the next payroll cycle.

Frequently asked questions

Can every employer use self-correction?

No. Eligibility depends on the plan, failure, established practices and applicable exclusions. Ask the adviser to document why SCP is available rather than assuming that a small dollar amount makes the problem eligible.

Are retirement plan corrections always free?

No. SCP has no IRS program fee or sanction, but an employer may still need to fund corrective amounts and professional work. VCP has a user fee, and Audit CAP involves a sanction. Budget only after the method and calculations are established.

Does the new IRA program start immediately?

No. Revenue Procedure 2026-33 is effective May 1, 2027. The employer EPCRS update has a different effective date. An owner’s personal IRA issue should be evaluated separately from the employer plan’s administration problem.

Should we wait until year-end to investigate?

A practical response is to investigate when the discrepancy is found. Preserve the records, tell the administrator and confirm the relevant timing requirements. Early fact gathering is especially useful when several payroll periods or employees may be involved.

Conclusion

The October update makes this a useful moment to review how your business handles retirement plan corrections. Begin with the plan document and a reliable reconciliation, then confirm eligibility, timing, funding and completion with the appropriate adviser.

Your next action can be small: compare one recent payroll cycle with its plan records and identify who investigates any difference. A clear owner, complete records and a documented resolution are more useful than an unexplained adjustment.

This article provides general federal information checked October 23, 2026. Plan-specific advice and separate legal, reporting or state obligations may require additional review.

GET IN TOUCH

Schedule a FREE Call

Contact us

Connect on our Socials!