📩 Get A Quote : hello@veritasaccountingservices.com
amended tax return

How to Correct a Mistake on an Already Filed Tax Return

Discovering an error on a tax return after it has already been filed can be stressful. A business owner or individual may immediately worry about penalties, interest, an IRS notice, or the possibility of having to prepare the entire return again.

The good news is that many tax filing mistakes can be corrected. The appropriate process depends on the nature of the error, the type of tax return, whether the original return has already been processed, and whether the correction changes the amount of tax owed or the refund due.

A mistake on a filed return should not automatically be ignored. At the same time, not every error requires an amended tax return. Some mathematical or processing errors may be corrected during return processing. In other situations, the tax authority may request additional information without requiring a complete amendment.

The correct response is to assess the issue carefully, gather the relevant records, determine the proper correction procedure, and act within the applicable deadline.

For businesses, the process may involve more than correcting a single figure. An accounting error may affect revenue, expenses, depreciation, payroll, inventory, partner or shareholder information, state filings, and future financial statements. That is why a tax filing error should be reviewed from both an accounting and tax perspective.

What Is an Amended Tax Return?

An amended tax return is a corrected tax filing submitted after the original return has already been filed. It is generally used to change information that was reported incorrectly or omitted from the original filing.

Depending on the taxpayer and the type of return, an amendment may be needed to correct:

  • Filing status.
  • Business or personal income.
  • Deductible expenses.
  • Tax credits.
  • Dependent information.
  • Tax liability.
  • Withholding information.
  • Depreciation details.
  • Fixed-asset information.
  • Business deductions.
  • Partner or shareholder information.
  • Supporting schedules.
  • Other information affecting the tax calculation.

For individual federal income tax returns, Form 1040-X is generally used to correct a previously filed individual income tax return. The form requires the taxpayer to show the original amounts, the changes being made, and the corrected amounts.

Businesses may need different forms or procedures depending on their entity type. A corporation, S corporation, partnership, or other business entity may need to amend its federal return, related schedules, state filings, or information returns.

An amended tax return is not simply a second copy of the original return. It should clearly explain what changed, why the change is necessary, and how the corrected figures were calculated.

Common Mistakes That May Require a Correction

Tax return errors can occur for many reasons. Sometimes information was unavailable when the return was prepared. In other cases, the taxpayer or preparer may have misunderstood a transaction, omitted a document, or entered an incorrect figure.

Incorrect Income

A taxpayer may discover that income from a bank account, investment, rental property, payment platform, or business activity was omitted or reported incorrectly.

For a business, income may be missed because records from a payment processor, e-commerce platform, or separate bank account were not included in the accounting records.

Missed Deductions

A taxpayer may discover that an eligible business expense, charitable contribution, retirement contribution, or other deduction was not included in the original return.

However, the expense must be reviewed carefully. A payment appearing on a bank statement does not automatically qualify as a tax deduction. The taxpayer should be able to establish the nature, purpose, and eligibility of the expense through appropriate documentation.

Incorrect Tax Credits

A credit may have been omitted, calculated incorrectly, or claimed without satisfying all applicable requirements. Corrections involving credits should be reviewed carefully because some credits have specific eligibility rules, limitations, and documentation requirements.

Incorrect Filing Status or Personal Information

An incorrect filing status, dependent claim, or taxpayer classification may affect the tax calculation. Certain changes may require additional documentation or coordination with another taxpayer.

Business Accounting Errors

For business taxpayers, errors may arise from:

  • Incorrect revenue totals.
  • Duplicate expenses.
  • Unrecorded liabilities.
  • Incorrect depreciation.
  • Misclassified loan payments.
  • Improper treatment of owner distributions.
  • Incorrect inventory balances.
  • Missing payroll expenses.
  • Incorrect partner or shareholder allocations.
  • Incomplete state tax information.

Not every bookkeeping adjustment automatically requires an amended tax return. The tax preparer should first determine whether the error affected the filed return and whether the correction changes taxable income, tax liability, credits, or other reported information.

The first step is to identify exactly what went wrong.

Avoid making a quick correction based only on a general suspicion. Instead, review the original tax return, supporting schedules, accounting records, and source documents.
amended tax return

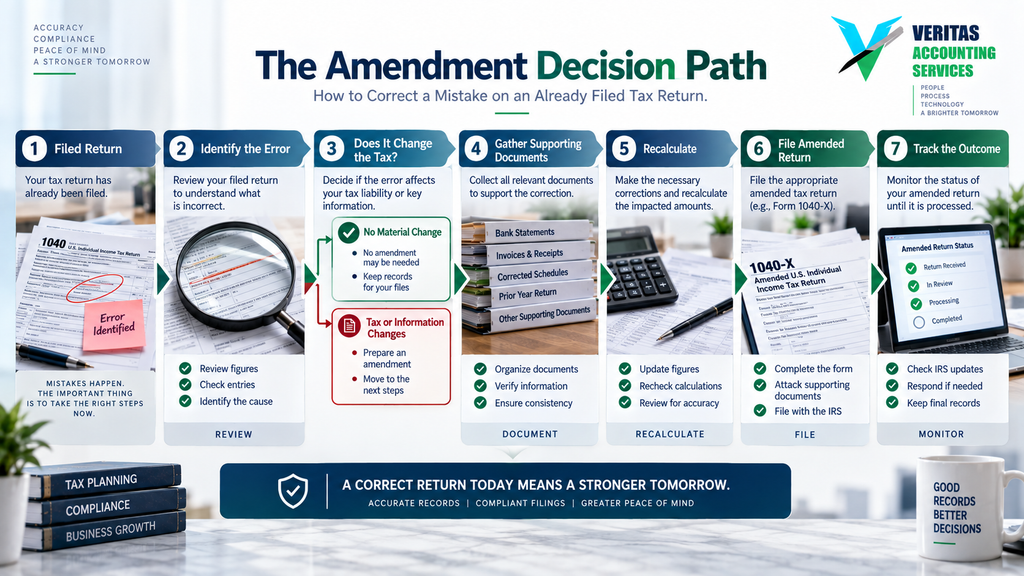
Step 1: Identify and Understand the Error

For example, if a business owner believes that an expense was omitted, the review should determine:

  1. Whether the expense was actually incurred.
  2. Whether it was recorded in the accounting system.
  3. Whether it was included elsewhere on the return.
  4. Whether it is deductible under the applicable tax rules.
  5. Whether it belongs to the tax year being amended.
  6. Whether it was already included in a book-to-tax adjustment.
  7. Whether supporting documentation is available.

If income appears to be missing, compare the filed return with bank statements, sales reports, payment-platform statements, invoices, and third-party reporting forms.

The purpose of this step is to distinguish a genuine tax return error from an accounting presentation issue, a timing difference, or an item that was already correctly reported elsewhere.

A business should also determine whether the error is isolated or part of a wider bookkeeping problem. For example, an omitted expense may indicate that an entire credit card account was never reconciled.

Step 2: Determine Whether an Amendment Is Necessary

Not every mistake requires an amended tax return.

Some mathematical or processing errors may be identified and corrected during return processing. An amendment may also be unnecessary when the tax authority simply requests a missing form, schedule, or supporting document.

Before preparing an amended tax return, ask the following questions:

  • Does the error change taxable income?
  • Does it change the amount of tax owed?
  • Does it affect a deduction or credit?
  • Does it change filing status or dependent information?
  • Does it affect information reported on a business schedule?
  • Has the tax authority already adjusted the return?
  • Has a notice been issued?
  • Is the original return within the applicable amendment period?
  • Does the correction affect a state or local filing?
  • Is another correction procedure more appropriate?

For example, a minor typographical error that does not affect the tax calculation may not require an amendment. However, omitted business income, an incorrect filing status, or an unsupported credit may require a formal correction.

If a tax authority has already issued a notice, review the notice carefully and follow its instructions. Filing an amendment without considering the notice may create confusion or duplicate work.

Step 3: Gather Supporting Documents

Once it is determined that a correction may be necessary, collect all documents related to the affected item.

Supporting records may include:

  • The originally filed tax return.
  • Previously filed schedules and forms.
  • Tax notices.
  • Bank statements.
  • Credit card statements.
  • Invoices and receipts.
  • Payroll reports.
  • Loan statements.
  • Depreciation schedules.
  • Inventory records.
  • Payment-platform reports.
  • Brokerage statements.
  • Rental property records.
  • Partnership or shareholder schedules.
  • State tax filings.
  • Proof of tax payments.
  • Relevant contracts or agreements.

Do not simply change one figure without reviewing the related sections of the return. A single correction may affect several forms or schedules.

For example, an adjustment to business income may also affect:

  • Self-employment tax.
  • Qualified business income calculations.
  • Estimated tax payments.
  • State taxable income.
  • Partner or shareholder information.
  • Related credits.
  • Loss carryforwards.
  • Tax basis or capital account information.

The supporting documents should show the original position, the corrected position, and the reason for the change. Good documentation makes the amendment easier to prepare and helps demonstrate that the correction is accurate.

Step 4: Recalculate the Correct Tax Position

After gathering the records, recalculate the return using the corrected information.

This step requires care because one change may affect several parts of the tax calculation.

For example, suppose a business discovers that it omitted $12,000 of legitimate deductible expenses. The correction may reduce taxable income, but the final tax impact could depend on:

  • The taxpayer’s entity type.
  • The applicable tax rules.
  • Other deductions.
  • Tax credits.
  • State tax requirements.
  • Self-employment tax.
  • Loss limitations.
  • Carryforward amounts.
  • Other income reported on the return.

If the business omitted $12,000 of revenue, the additional tax may be affected by other expenses, ownership structure, estimated tax payments, and other tax attributes.

For business taxpayers, the correction should generally begin with the accounting records. The books may need to be updated, reconciled, or adjusted before the amended tax return is prepared.

However, an accounting correction and a tax correction are separate steps. A bookkeeping entry does not automatically determine the correct tax treatment.

The recalculation should identify:

  • Original taxable income.
  • Corrected taxable income.
  • Original tax liability.
  • Corrected tax liability.
  • Original payments and credits.
  • Corrected refund or balance due.
  • Related forms and schedules that must be updated.

Step 5: Select the Correct Amendment Form

The appropriate form depends on the type of return being corrected.

Individual Federal Returns

For most individual federal income tax corrections, Form 1040-X is generally used to amend a previously filed individual return.

The taxpayer must report the original amounts, the changes, the corrected amounts, and an explanation of the correction. Relevant forms and schedules should be attached or submitted as required.

Corporate Returns

Corporations may need a specific amended-return form or an applicable electronic filing procedure, depending on the type of corporate return and the tax year involved.

A corrected corporate return generally needs the appropriate amended-return designation, revised forms, changed schedules, supporting information, and an explanation of the changes.

Partnership and S Corporation Returns

Partnerships and S corporations require additional consideration because changes may affect partners, shareholders, allocations, capital accounts, ownership percentages, and information reported to owners.

An amendment to a business return may require updated schedules, corrected owner information, and additional reporting to partners or shareholders. The applicable procedure depends on the tax year, entity type, filing status, and relevant tax rules.

State and Local Returns

A federal correction may affect state or local tax filings. State procedures are separate and may involve different forms, deadlines, payment rules, and documentation requirements.

A taxpayer should not assume that correcting the federal return automatically corrects the state return.

Step 6: Explain the Changes Clearly

A well-prepared amended tax return should explain what was wrong, what has been corrected, and why the corrected information is accurate.

A clear explanation should include:

  • The tax year being amended.
  • The original item reported.
  • The corrected item.
  • The reason for the correction.
  • The supporting documents included.
  • Any related forms or schedules being updated.
  • The effect on tax liability or refund.

For example, an explanation might state that a business expense was omitted from the original return because a credit card statement was received after filing. The explanation should identify the expense, describe its business purpose, state the corrected amount, and refer to the supporting documentation.

Avoid vague statements such as “mistake corrected” or “updated figures.” The tax authority should be able to understand the issue without reconstructing the entire history of the return.

The explanation should be factual and concise. It should not include unnecessary speculation, emotional language, or unsupported conclusions.

Step 7: File the Amended Return and Pay Any Additional Tax

Once the corrected return has been prepared and reviewed, file it using the appropriate method.

Eligible individual amended returns may generally be filed electronically through approved tax software. Some tax years, return types, and circumstances may require paper filing.

If the correction results in additional tax, the taxpayer should pay the amount due as soon as possible. Filing an amended tax return does not generally eliminate interest or penalties that may apply to an unpaid tax balance.

The taxpayer should also review whether the correction affects estimated tax payments, payroll tax obligations, state filings, or future tax returns.

After filing, retain:

  • A complete copy of the amended return.
  • Electronic filing confirmation, if applicable.
  • Proof of mailing, if filed on paper.
  • Payment confirmation.
  • Supporting documents.
  • Tax authority acknowledgments.
  • Related correspondence.

An amended return may take longer to process than an original return. Processing times can vary depending on the type of return, the filing method, the complexity of the correction, and whether additional review is required.

Federal and State Amended Returns

One of the most common mistakes is assuming that a federal amendment automatically updates every other tax filing.

A federal correction may affect:

  • State income tax returns.
  • Local income tax returns.
  • Franchise tax filings.
  • Sales tax reports.
  • Payroll tax filings.
  • Partnership or shareholder reporting.
  • Estimated tax calculations.

For example, if a business reports additional federal income, the state may require a corresponding amendment. If the correction relates to sales tax or payroll tax, a separate filing process may be necessary.

State tax agencies have their own rules regarding amended returns, deadlines, payment requirements, and documentation. The taxpayer should review the relevant state requirements or consult a qualified tax professional.

When preparing an amendment, create a checklist of all potentially affected filings. This helps prevent a federal correction from creating an inconsistent state or local tax position.

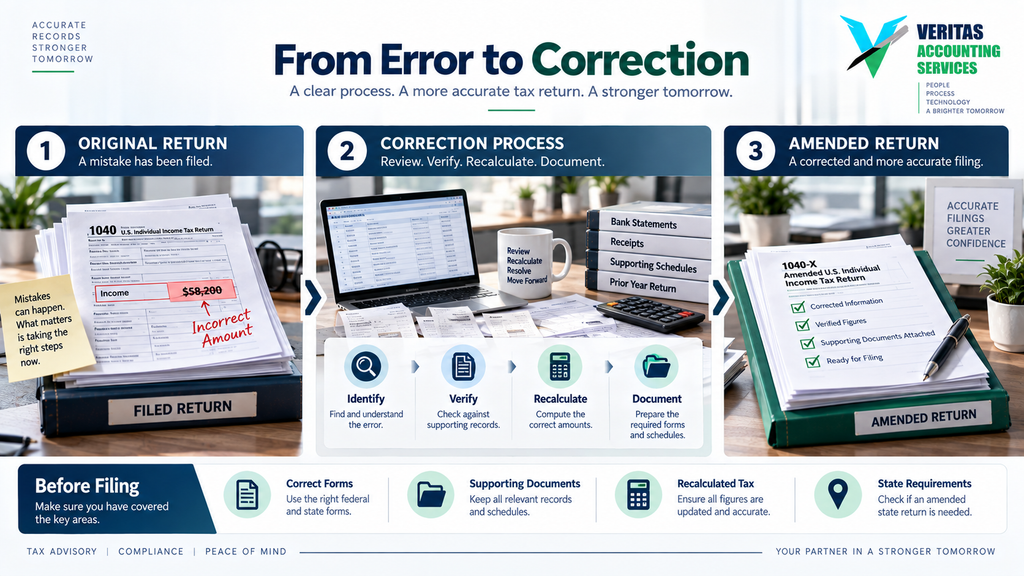
What If the Error Results in a Refund?

An amended tax return may result in a refund when the taxpayer paid more tax than was ultimately due or becomes eligible for an additional deduction or credit.

Examples include:

  • An omitted deductible expense.
  • An overlooked tax credit.
  • Incorrectly reported income.
  • An overstatement of taxable income.
  • An incorrect withholding amount.
  • A correction to filing status.
  • A business adjustment that reduces taxable income.

A refund claim must generally be filed within the applicable statutory period. The relevant deadline can depend on when the original return was filed, when the tax was paid, the type of claim, and special rules that may apply.

Taxpayers should not delay a refund claim unnecessarily. Before filing, confirm that the correction is fully supported and that all related schedules have been updated.

A refund is not guaranteed merely because an amendment is filed. The tax authority may review the correction and request additional information.
amended tax return

What If the Error Results in Additional Tax?

If the correction increases taxable income or reduces deductions or credits, the amended tax return may show additional tax due.

Examples include:

  • Omitted business income.
  • Incorrectly claimed deductions.
  • Excessive tax credits.
  • Incorrect depreciation.
  • Unreported investment income.
  • Incorrect filing status.
  • Previously omitted rental income.
  • Reclassification of a personal expense as nondeductible.

When additional tax is due, the taxpayer should consider making payment promptly. Interest and applicable penalties may continue to apply according to the relevant rules.

The taxpayer should also review whether the error affects estimated tax payments, payroll tax obligations, state filings, or future tax returns.

If the amount is substantial, professional advice may be appropriate before filing. A tax professional can help determine the correct treatment, evaluate potential penalty exposure, and coordinate federal and state corrections.

Common Mistakes to Avoid When Filing an Amendment

Filing an Amendment for Every Minor Error

Not every typographical or mathematical mistake requires an amendment. First determine whether the error affects the tax return and whether the tax authority has already corrected it.

Amending Before the Original Return Is Filed

An amended return is generally used after the original return has been filed. In certain circumstances before the original filing deadline, a superseding return may be more appropriate.

Ignoring Tax Notices

If a tax authority has issued a notice, review it carefully. The notice may contain specific instructions for responding or submitting documents.

Correcting Only One Related Form

A change to income, deductions, depreciation, or ownership information may affect multiple schedules. All related forms should be reviewed.

Failing to Update the Accounting Records

For a business, the books should generally reflect the corrected transaction or adjustment. Otherwise, future financial statements and tax returns may continue to contain the same problem.

Claiming an Unsupported Deduction

A taxpayer should not use an amendment as an opportunity to claim an expense without adequate documentation or eligibility.

Forgetting the State Return

A federal correction may require a state or local amendment. This should be evaluated before the correction process is completed.

Failing to Pay Additional Tax

Filing the amended return does not necessarily satisfy the payment obligation. If additional tax is due, payment arrangements or other options may need to be considered.

Submitting Inconsistent Information

The amended return should be consistent with financial statements, payroll reports, information returns, accounting records, and other filings. Inconsistencies can lead to additional questions or delays.

When Professional Tax Assistance Is Advisable

Some corrections are straightforward, but professional assistance is often appropriate when the error is complex or involves a material amount.

Consider consulting a tax professional when:

  • The error affects business income.
  • Multiple tax years are involved.
  • The amendment changes a partnership or S corporation return.
  • The correction affects partner or shareholder allocations.
  • Payroll or employment taxes are involved.
  • Sales tax or multi-state obligations are affected.
  • A tax notice has been issued.
  • The correction may involve penalties.
  • The original return was prepared using incomplete books.
  • The taxpayer is uncertain whether an item is deductible.
  • The correction involves foreign income or international reporting.
  • The refund claim is substantial.
  • The business has already been selected for examination.

A qualified professional can help review the original return, reconcile accounting records, calculate the corrected tax position, prepare the necessary forms, explain the changes, and identify related filing obligations.

For business owners, the process should include both tax review and accounting review. Correcting the tax return without addressing the underlying bookkeeping issue may lead to repeated errors in future periods.

Frequently Asked Questions

Does every tax return mistake require an amended tax return?

No. Some mathematical or processing errors may be corrected during tax return processing. An amendment may also be unnecessary when the tax authority simply requests a missing form or supporting document. The need for an amendment depends on the type and effect of the error.

What form is used to amend an individual federal tax return?

Form 1040-X is generally used to correct a previously filed individual federal income tax return. The taxpayer must report the original amounts, the changes, the corrected amounts, and an explanation of the correction.

Can an amended tax return be filed electronically?

Eligible individual amended returns may generally be filed electronically through approved tax software. Some tax years, return types, and circumstances may require paper filing.

How long do I have to file an amended tax return?

The deadline depends on the type of correction, the taxpayer, the tax year, and whether the amendment results in a refund or additional tax. Refund claims may be subject to specific statutory time limits, so the applicable rules should be reviewed before filing.

What happens if the amendment shows additional tax?

The taxpayer should file the correction and pay the additional tax as soon as possible. Interest and applicable penalties may apply to unpaid tax. Filing an amended return does not automatically remove those amounts.

Will an amended tax return trigger an audit?

Filing an amendment does not automatically mean that the taxpayer will be audited. However, the amended return may be reviewed, and the tax authority may request supporting documents or additional information.

Do I need to amend my state tax return?

Possibly. If the federal correction affects state taxable income, deductions, credits, or other state reporting items, a state amendment may be required. State procedures are separate from the federal process.

Can I amend a business tax return?

Yes, but the process depends on the business structure and the type of return. Corporations, partnerships, S corporations, and other entities may have different forms, schedules, and filing procedures.

Should I correct the bookkeeping before amending the tax return?

For a business, the accounting records should generally be reviewed and corrected before the amended tax return is finalized. This helps ensure that the financial statements and tax filings are consistent.

How long does it take to process an amended return?

Processing times can vary. Amended returns may require additional review, especially when they involve multiple schedules, substantial changes, or supporting documents. Taxpayers should retain filing confirmations and monitor any correspondence after submission.

Conclusion

Discovering an error on an already filed tax return can be uncomfortable, but it does not mean that the situation cannot be corrected. The appropriate response is to review the original filing, identify the precise error, determine whether an amendment is required, gather supporting records, recalculate the correct tax position, and file the appropriate correction.

An amended tax return should be prepared carefully because one change may affect several forms, schedules, tax calculations, and state filing obligations. Business owners should also review their accounting records to ensure that the underlying issue does not continue into future periods.

The most important principles are simple: do not ignore a material error, do not assume that every minor mistake requires an amendment, do not claim unsupported deductions, and do not overlook payment or state filing obligations.

With timely action, accurate documentation, and professional guidance where necessary, taxpayers can correct filing mistakes and improve the reliability of their future tax and financial reporting.

How Veritas Accounting Services Can Help

At Veritas Accounting Services, we help businesses review financial records, identify accounting discrepancies, reconcile accounts, prepare tax-ready information, and support corrections arising from bookkeeping or reporting errors.

Our team can assist with bookkeeping cleanup, financial statement review, transaction classification, bank reconciliations, fixed-asset records, loan accounts, payroll records, and year-end tax preparation support. We also help business owners organize the documentation needed for discussions with their tax advisers.

If you have discovered an error in your financial records or are preparing to correct a previously filed business tax return, visit Veritas Accounting Services or explore our virtual bookkeeping services.

GET IN TOUCH

Schedule a FREE Call
What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Your Simple Guide to Unpaid Invoice Mistakes and Better Records

An unpaid customer invoice is not automatically a tax deduction. Review the tax accounting method…

Connect on our Socials!

Poor Bookkeeping

How Poor Bookkeeping Can Lead to Serious Tax Problems

Many business owners think bookkeeping is simply the process of recording income and expenses. In reality, bookkeeping forms the foundation of a company’s financial reporting, tax preparation, cash flow management, and business decision-making.

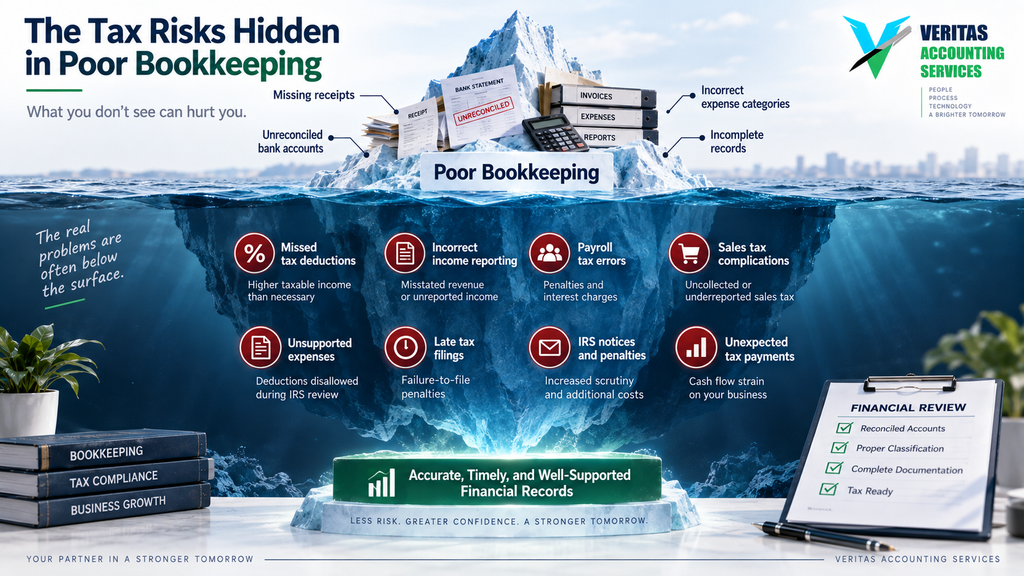
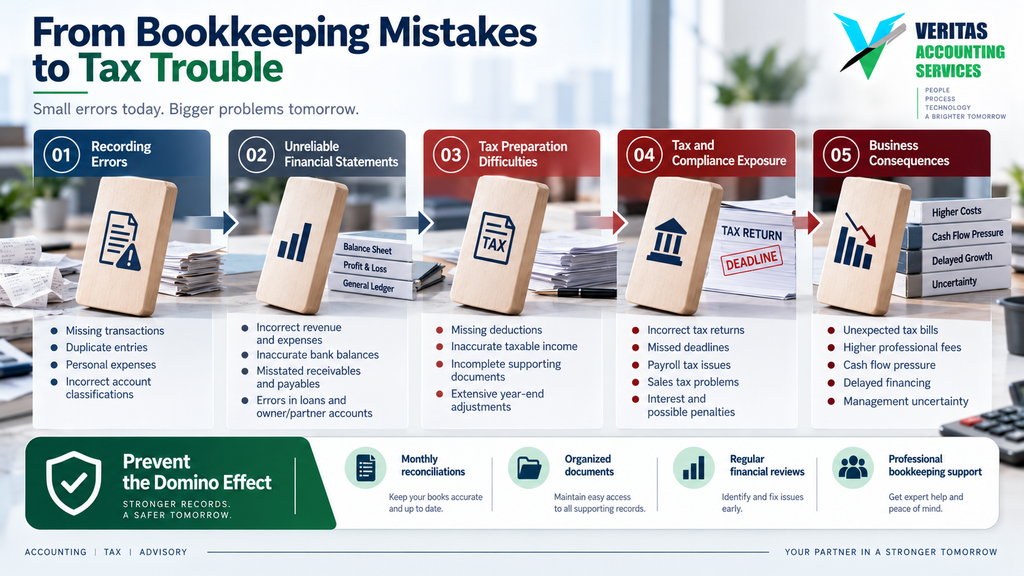
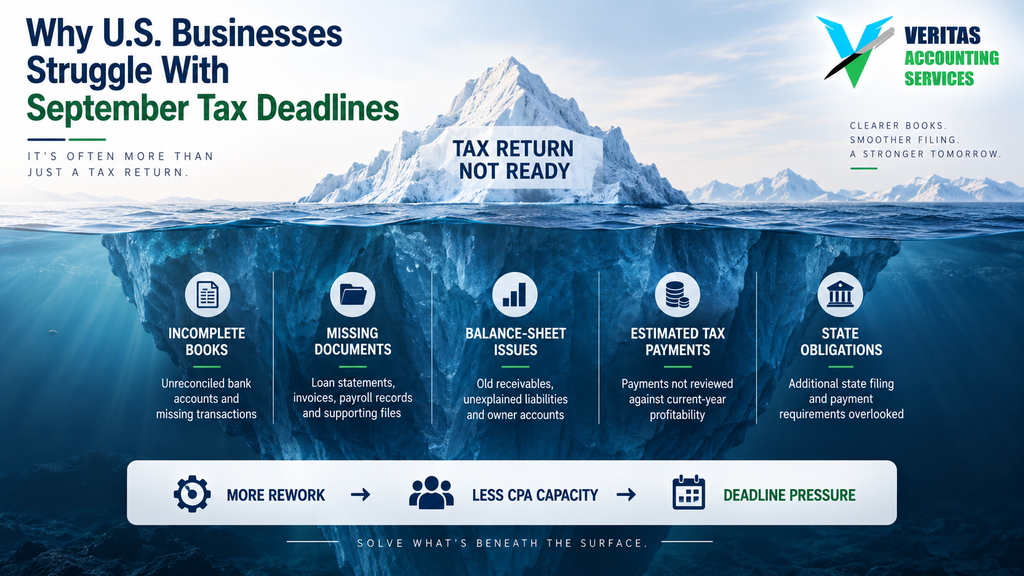
When records are incomplete, transactions are misclassified, bank accounts are not reconciled, or supporting documents are missing, the problem can extend far beyond an inaccurate profit and loss statement. Poor bookkeeping can result in missed deductions, understated or overstated income, incorrect tax filings, delayed compliance, and avoidable penalties.

The Internal Revenue Service expects businesses to maintain records that clearly show income and expenses and support the amounts reported on tax returns. Proper records also help businesses prepare financial statements, identify deductible expenses, and respond to questions during an examination.

For this reason, bookkeeping should not be treated as an administrative task that can be postponed until tax season. Reliable bookkeeping is an important part of tax risk management.

What Is Poor Bookkeeping?

Poor bookkeeping occurs when a business does not maintain complete, accurate, timely, and properly supported financial records. It may arise from a lack of accounting knowledge, insufficient review procedures, rapid business growth, poor software setup, or simply leaving financial work until the end of the year.

Common examples include:

  • Recording transactions in the wrong account.
  • Failing to reconcile bank and credit card accounts.
  • Mixing personal and business expenses.
  • Omitting cash, online, or payment-platform income.
  • Recording loan proceeds as revenue.
  • Treating asset purchases as ordinary expenses.
  • Failing to record unpaid bills or customer receivables.
  • Losing invoices, receipts, and other supporting documents.
  • Ignoring old unreconciled transactions.
  • Failing to record owner contributions and distributions correctly.
  • Using incorrect opening balances.
  • Making year-end adjustments without proper documentation.

A business may appear to be operating normally while these issues accumulate in the accounting records. The tax consequences often become visible only when the annual return is prepared or when a tax authority requests supporting documentation.

How Poor Bookkeeping Creates Tax Problems

Tax returns are prepared using financial information. If the underlying books are incorrect, the tax return may also be incorrect.

The relationship is straightforward:

Incomplete transactions → inaccurate financial statements → incorrect taxable information → tax exposure

Poor bookkeeping does not always mean that a business has intentionally violated tax rules. Errors can occur because records are incomplete or because the accounting treatment was not properly reviewed. However, the outcome may still include additional tax, interest, penalties, or the loss of deductions.

The IRS identifies several types of tax penalties, including failure-to-file penalties, failure-to-pay penalties, information-return penalties, and accuracy-related penalties. Accuracy-related penalties may apply when income is not properly reported or when deductions or credits are claimed without sufficient eligibility or support.

The following are some of the most common ways bookkeeping problems can develop into tax problems.

1. Missed Business Income

One of the most serious bookkeeping risks is failing to record all business income.

Businesses may receive money through multiple channels, including:

  • Business bank accounts.
  • Credit card processors.
  • Payment platforms.
  • E-commerce marketplaces.
  • Cash collections.
  • Checks.
  • Wire transfers.
  • Digital payment applications.
  • Third-party delivery or booking platforms.

When a business relies only on bank-feed transactions or reviews one bank account, some income may be missed. A payment may be deposited into another account, recorded in a different accounting file, or incorrectly treated as a transfer.

For example, an online seller may receive sales proceeds through a marketplace and record only the net deposit received in the bank account. If the marketplace withheld commissions, payment-processing fees, refunds, or reserves, recording only the net deposit may result in incomplete sales reporting and inaccurate expense recognition.

The correct accounting treatment depends on the transaction details, but the underlying principle is consistent: the books should capture the appropriate gross income, related fees, refunds, and other adjustments.

Missing income can create several problems. It may understate revenue, distort gross profit, affect sales-tax reporting, and result in an inaccurate income tax return. Businesses should regularly compare accounting records with bank statements, payment-platform reports, sales systems, and third-party information returns.

2. Lost or Disallowed Tax Deductions

Poor bookkeeping can also increase taxes by causing legitimate business expenses to be overlooked.

A business may incur deductible expenses throughout the year, but those expenses can be missed when:

  • Receipts are not collected.
  • Credit card transactions are not reviewed.
  • Bills are not entered.
  • Expenses are posted to suspense accounts.
  • Reimbursements are not recorded.
  • Business mileage is not tracked.
  • Subscription and software expenses are overlooked.
  • Expenses are recorded in the wrong accounting period.

The IRS explains that good records help businesses identify deductible expenses and support the items reported on their tax returns. However, a bank or credit card statement alone may not always establish that an expense is deductible. Additional documentation may be needed to show the business purpose, nature of the expense, and connection to the business.

For example, a business owner may pay for professional consulting services using a personal credit card. If the transaction is never reported to the bookkeeper, the business may lose the opportunity to claim an otherwise allowable expense.

Missing deductions can increase taxable income even when the business actually incurred the costs. This is one reason why accurate bookkeeping is not only about preventing errors; it is also about ensuring that the business receives the tax treatment it is entitled to receive.

3. Incorrect Expense Classification

Not every payment made by a business is an immediate tax-deductible expense. Incorrect classification can change the timing and amount of deductions.

Common classification mistakes include recording:

  • Loan proceeds as income.
  • Loan principal repayments as expenses.
  • Owner distributions as business expenses.
  • Equipment purchases as office supplies.
  • Personal expenses as business expenses.
  • Capital improvements as ordinary repairs.
  • Security deposits as expenses.
  • Refundable deposits as revenue reductions.
  • Prepaid expenses as fully incurred expenses.
  • Inventory purchases directly as operating expenses.

The correct treatment depends on the facts, the entity type, the accounting method, the applicable tax rules, and the nature of the transaction.

For instance, a business that purchases equipment may need to record the asset on its balance sheet and claim depreciation or another applicable tax treatment rather than deducting the entire payment as an ordinary expense. Similarly, loan principal repayments generally reduce a liability rather than representing an operating expense, while interest may require separate treatment.

When these items are incorrectly classified, the profit and loss statement becomes unreliable. The tax preparer may then need to spend additional time reconstructing the transactions and making adjustments before the return can be completed.

4. Payroll and Employment Tax Errors

Payroll bookkeeping requires particular attention because payroll transactions affect employees, employers, tax authorities, and sometimes benefit providers.

Errors may occur when a business:

  • Records gross payroll instead of the correct payroll expense and liability structure.
  • Fails to record payroll tax liabilities.
  • Does not reconcile payroll reports with the general ledger.
  • Omits employer payroll taxes.
  • Records employee deductions as business expenses.
  • Fails to distinguish employee wages from contractor payments.
  • Misses payroll-related adjustments.
  • Does not maintain payroll tax payment records.

Payroll errors can result in incorrect wage reporting, inaccurate employment tax filings, unpaid liabilities, and penalties. The IRS advises businesses to retain employment tax records for at least four years, subject to the applicable requirements.

A monthly reconciliation between payroll reports, payroll liabilities, bank payments, and the accounting ledger can help identify errors before they become larger compliance problems.

Businesses should also review worker classification carefully. Treating an employee as an independent contractor may create tax and reporting consequences if the classification is incorrect.

5. Problems With Sales Tax and Other Indirect Taxes

Income tax is not the only tax area affected by bookkeeping quality. Poor bookkeeping can also create problems with sales tax, use tax, franchise tax, excise tax, and other state or local obligations.

For example, a business may fail to properly track:

  • Taxable and nontaxable sales.
  • Sales by state or jurisdiction.
  • Exempt customer transactions.
  • Sales-tax collected.
  • Marketplace facilitator activity.
  • Taxable shipping or delivery charges.
  • Purchases subject to use tax.
  • Tax refunds and credits.
  • Tax payments and outstanding liabilities.

If sales are recorded without sufficient detail, the business may not be able to determine where tax was collected or whether additional registration and filing obligations exist.

Bookkeeping software may show total sales, but tax compliance often requires more detailed information. Businesses operating across multiple states should maintain records that allow sales to be analyzed by location, product or service type, customer status, and applicable tax treatment.

A tax preparer or indirect-tax professional may need to review the business model and jurisdictional requirements separately. Bookkeeping alone cannot determine every tax obligation, but accurate transaction-level records make the review possible.

6. Incorrect Financial Statements and Tax Returns

Tax professionals depend on reliable financial statements to prepare business tax returns. If the trial balance, income statement, or balance sheet contains errors, the tax return may require significant adjustments.

Examples include:

  • Incorrect retained earnings or equity balances.
  • Missing depreciation entries.
  • Unreconciled cash accounts.
  • Negative accounts receivable balances.
  • Incorrect inventory balances.
  • Unrecorded accounts payable.
  • Unexplained suspense accounts.
  • Incorrect loan balances.
  • Missing accrued expenses.
  • Inconsistent opening balances.

For partnerships and multi-member LLCs, additional risks may involve partner contributions, distributions, capital accounts, ownership percentages, liability allocations, and profit or loss allocations.

For corporations, errors may affect shareholder distributions, retained earnings, fixed assets, loans from or to shareholders, and book-to-tax adjustments.

The tax return may not simply reproduce the accounting records. Tax rules can require adjustments, elections, reconciliations, and separate schedules. Nevertheless, the books must provide a reliable starting point.

When poor bookkeeping results in a large number of unexplained adjustments, the risk of omissions and inconsistent reporting increases.

7. Cash Flow and Estimated Tax Problems

Bookkeeping errors can affect tax payments even when the final tax return has not yet been prepared.

Business owners often use monthly or quarterly financial reports to estimate taxable income and plan tax payments. If revenue is understated or expenses are overstated, the business may underestimate its tax liability and fail to set aside sufficient funds.

On the other hand, if income is overstated or expenses are omitted from the books, the owner may reserve more cash than necessary or make inaccurate business decisions.

Businesses and individuals may have estimated tax obligations depending on their structure, income, and applicable rules. The IRS describes federal income tax as a pay-as-you-go system and explains that taxpayers may need to make estimated payments when withholding is insufficient.

Poor bookkeeping can therefore create two related problems:

  1. The tax calculation may be inaccurate.
  2. The business may not have enough cash available when tax payments are due.

Accurate monthly reporting helps business owners monitor profitability, forecast cash requirements, and coordinate with their tax adviser before payment deadlines.

8. Missing Records During an IRS Examination

A tax return is not fully protected simply because it has been filed. Businesses should retain records that support income, deductions, credits, assets, liabilities, and other reported items.

During an examination, the IRS may ask the business to explain specific transactions. If invoices, receipts, contracts, bank reconciliations, mileage records, loan documents, or other supporting materials are missing, the business may struggle to substantiate its position.

The IRS states that taxpayers have the responsibility to support entries, deductions, and statements made on their tax returns. Records should be retained for as long as they are needed to establish the income or deductions reported.

A lack of documentation does not automatically mean that every item will be disallowed, but it can make the business’s position more difficult to defend. It may also increase professional fees because the accountant must reconstruct records or investigate transactions that should have been documented during the year.

9. Late Filings and Missed Tax Deadlines

Poor bookkeeping can delay tax preparation. When financial records are incomplete, the tax preparer may not be able to finalize the return on time.

Common causes of delay include:

  • Missing bank statements.
  • Unreconciled accounts.
  • Unrecorded payroll transactions.
  • Incomplete inventory information.
  • Missing fixed-asset details.
  • Unresolved shareholder or partner transactions.
  • Unavailable loan statements.
  • Incomplete sales reports.
  • Unclear tax notices.
  • Unorganized supporting documents.

A filing extension may provide additional time to submit a return, but it generally does not extend the time to pay taxes that are due. The IRS specifically distinguishes between an extension of time to file and an extension of time to pay.

When bookkeeping is delayed until the filing deadline approaches, the business may have fewer options to identify missing information, correct errors, obtain documents, and coordinate with its tax adviser.

10. Increased Professional Fees and Business Disruption

The financial cost of poor bookkeeping is not limited to additional tax.

When records are disorganized, accountants and tax professionals may need to spend additional time on:

  • Transaction reconstruction.
  • Bank and credit card reconciliation.
  • Duplicate removal.
  • Reclassification of expenses.
  • Payroll liability investigation.
  • Review of payment-platform reports.
  • Fixed-asset reconstruction.
  • Loan balance verification.
  • Partner or shareholder account analysis.
  • Preparation of missing schedules.
  • Responses to tax notices.

This additional work may increase accounting fees and delay the preparation of financial statements and tax returns.

Poor bookkeeping can also affect lenders, investors, business buyers, and management. A business may find it difficult to demonstrate profitability, calculate reliable margins, obtain financing, or evaluate a potential acquisition when its financial information is incomplete.

How to Prevent Tax Problems Caused by Poor Bookkeeping

Businesses can reduce tax risk by treating bookkeeping as an ongoing control process rather than a year-end task.

Reconcile Accounts Monthly

Bank, credit card, payment-platform, loan, and payroll accounts should be reconciled regularly. Reconciliations help identify missing transactions, duplicate entries, bank charges, incorrect transfers, and unusual balances.

Maintain Separate Business and Personal Accounts

Separate accounts make it easier to identify business transactions and reduce confusion over owner-related payments. Personal expenses should not be recorded as business deductions merely because they were paid from a business account.

Keep Supporting Documents

Invoices, receipts, contracts, bills, payroll reports, loan statements, and payment confirmations should be stored in an organized digital or paper system. Documents should be linked to the relevant accounting transactions whenever possible.

Review the Chart of Accounts

The chart of accounts should reflect the nature and complexity of the business. Accounts should be reviewed periodically to ensure that expenses, assets, liabilities, equity, and income are being classified consistently.

Review Financial Statements

Business owners should review the profit and loss statement and balance sheet every month. Unusual changes in revenue, margins, expenses, receivables, payables, and liabilities should be investigated promptly.

Track Assets and Loans Separately

Maintain a fixed-asset register with purchase dates, costs, improvements, disposals, and depreciation information. Loan accounts should be reconciled to lender statements, with principal and interest recorded appropriately.

Prepare for Tax Season Throughout the Year

Businesses should maintain a tax-ready file containing prior-year returns, current-year financial statements, payroll reports, fixed-asset details, loan statements, ownership information, and other documents required by the tax preparer.

Coordinate With the Tax Adviser

Bookkeepers and tax professionals should communicate about unusual transactions, new business activities, ownership changes, asset purchases, loans, distributions, international transactions, and significant changes in profitability.

When a Bookkeeping Cleanup Is Necessary

A bookkeeping cleanup may be necessary when the business has accumulated unresolved accounting issues or when financial statements cannot be relied upon.

Warning signs include:

  • Bank accounts have not been reconciled for several months.
  • The balance sheet contains unexplained balances.
  • Accounts receivable or payable are inaccurate.
  • Loan balances do not match lender statements.
  • Owner or shareholder accounts are unclear.
  • The business cannot explain large deposits or withdrawals.
  • Tax returns contain repeated book-to-tax adjustments.
  • Supporting documents are missing.
  • Financial reports change significantly after year-end adjustments.
  • The tax preparer repeatedly requests the same information.

A proper cleanup should begin with an assessment of the accounting file, bank and credit card reconciliations, transaction classification, balance sheet review, supporting documentation, and prior tax returns.

The objective should not be merely to make the accounting software balance. The objective is to create financial records that are complete, explainable, and suitable for tax preparation and management decisions.

Frequently Asked Questions

Can poor bookkeeping increase business taxes?

Yes. Poor bookkeeping may cause legitimate deductions to be missed, income to be incorrectly reported, or expenses to be classified improperly. These errors can increase taxable income or result in additional tax adjustments.

Can bookkeeping errors result in IRS penalties?

They can. If bookkeeping errors lead to inaccurate tax returns, missing income, unsupported deductions, or late filings, the business may face additional tax, interest, or applicable penalties. The outcome depends on the facts, the type of error, and the applicable tax rules.

Is a bank statement enough to support a tax deduction?

Not always. A bank or credit card statement may prove that a payment occurred, but additional records may be needed to establish the business purpose, nature of the expense, and eligibility for a deduction.

How often should business books be reconciled?

Monthly reconciliation is a practical minimum for many businesses. Businesses with high transaction volumes, multiple payment platforms, or complex operations may benefit from more frequent reviews.

Can a tax preparer correct poor bookkeeping?

A tax preparer may be able to make tax adjustments or help identify accounting issues, but extensive bookkeeping cleanup may require a separate process. Businesses should not assume that the tax preparer will reconstruct every transaction without complete documentation.

What should a business do if its books are several months behind?

The business should first identify the period affected, gather bank statements and supporting documents, reconcile accounts, review the balance sheet, and prioritize unresolved items. It may be appropriate to engage a bookkeeping professional before preparing the tax return.

Does an extension solve bookkeeping problems?

No. An extension may provide additional time to file a tax return, but it does not correct inaccurate books and generally does not extend the time to pay taxes due.

Can poor bookkeeping affect business financing?

Yes. Lenders and investors often require reliable financial statements, cash flow information, and supporting schedules. Inaccurate or incomplete books can delay financing decisions or reduce confidence in the business’s financial position.

Conclusion

Poor bookkeeping can create serious tax problems because tax returns depend on the quality of the underlying financial records. Missing income, lost deductions, incorrect classifications, payroll errors, incomplete documentation, and unreconciled accounts can all increase tax risk.

The best way to reduce these risks is to maintain accurate books throughout the year. Monthly reconciliations, organized supporting documents, proper account classification, regular financial statement reviews, and communication with tax professionals can help businesses identify issues before they become expensive problems.

Bookkeeping should be viewed as an important financial control, not simply a recordkeeping obligation. Reliable records support accurate tax filings, better cash flow planning, stronger financial decisions, and greater confidence when responding to questions from tax authorities, lenders, or other stakeholders.

If your business records are incomplete, outdated, or difficult to understand, a structured bookkeeping review and cleanup can help establish a more reliable foundation for tax compliance and long-term growth.

How Veritas Accounting Services Can Help

At Veritas Accounting Services, we help businesses maintain organized, accurate, and tax-ready financial records through professional bookkeeping, accounting cleanup, reconciliations, financial reporting, and outsourced accounting support.

Our team can assist with transaction classification, bank and credit card reconciliations, accounts receivable and payable, payroll accounting, fixed-asset records, loan reconciliations, management reports, and year-end preparation support.

To reduce the risks associated with poor bookkeeping and improve the reliability of your financial information, visit Veritas Accounting Services  or explore our virtual bookkeeping services.

GET IN TOUCH

Schedule a FREE Call
What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Your Simple Guide to Unpaid Invoice Mistakes and Better Records

An unpaid customer invoice is not automatically a tax deduction. Review the tax accounting method…

Connect on our Socials!

Partnership firm tax return 1065

Beyond the Form 1065 Filing: The Financial Checks Every Partnership Should Complete

Preparing a partnership tax return involves much more than entering figures into tax software. Before a partnership can complete its Form 1065 filing, its financial records must be reviewed carefully to ensure that income, expenses, assets, liabilities, capital accounts, and partner transactions are properly reported.

Form 1065 is an information return used by partnerships to report income, gains, losses, deductions, credits, and other relevant information. The partnership generally does not pay federal income tax on its income at the entity level. Instead, income and other tax items are generally passed through to the partners. Each partner then uses the information reported on Schedule K-1 when preparing their own tax return. IRS 

This pass-through structure makes accuracy especially important. An error in the partnership’s books can affect not only the partnership return but also the tax reporting of every partner.

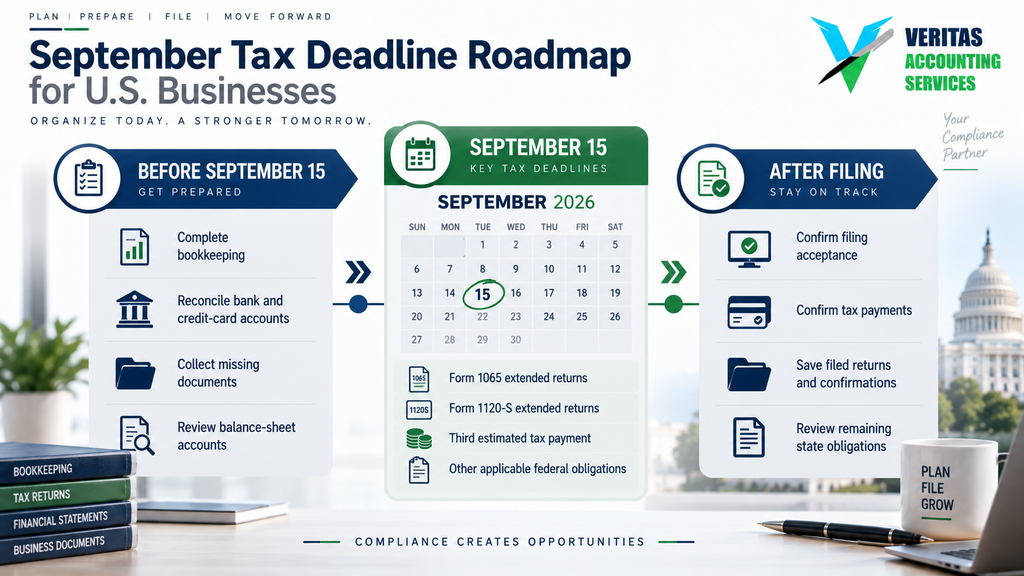
For calendar-year partnerships that properly requested an extension, September 15 is generally an important deadline for completing the extended return. However, meeting the deadline should not be the only objective. The partnership should also ensure that its financial records are complete, consistent, and supported by appropriate documentation.

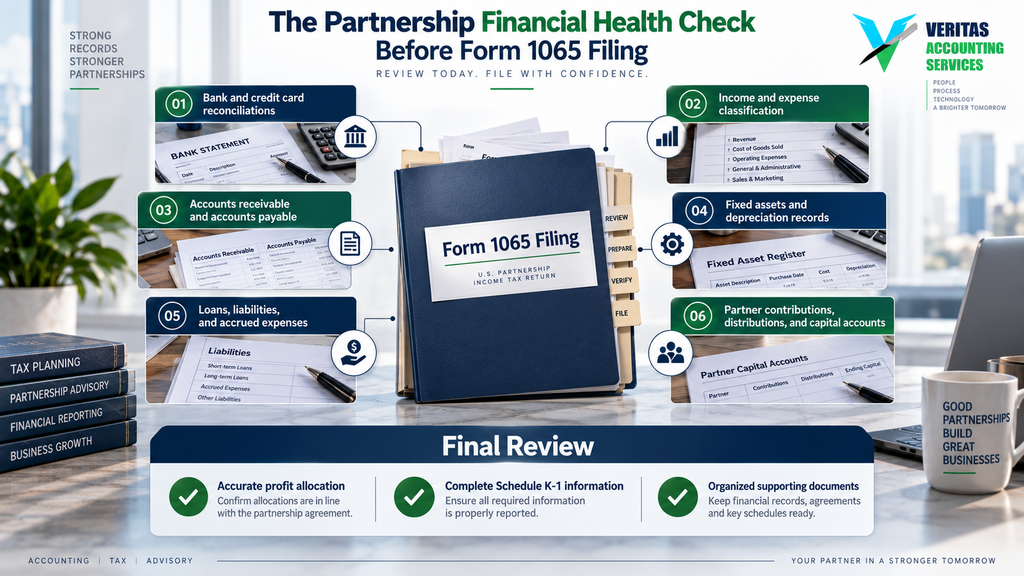
A strong Form 1065 filing process begins with a detailed financial review. This article explains the key checks every partnership should complete before the return is finalized.

Table of Contents

  1. Confirm the Partnership’s Tax and Filing Details
  2. Reconcile All Bank and Credit-Card Accounts
  3. Review Income and Expense Classification
  4. Examine Accounts Receivable and Accounts Payable
  5. Review Fixed Assets and Depreciation
  6. Verify Loans and Other Liabilities
  7. Reconcile Partner Contributions and Distributions
  8. Review Partner Capital Accounts
  9. Confirm Profit and Loss Allocations
  10. Review Schedule K-1 Information
  11. Identify International and State Tax Issues
  12. Maintain Supporting Documentation
  13. Final Form 1065 Filing Review
  14. Frequently Asked Questions
  15. Conclusion

1. Confirm the Partnership’s Tax and Filing Details

Before reviewing the numbers, confirm that the partnership’s basic tax information is correct.

The preparer should verify the legal name, Employer Identification Number, business address, accounting period, tax year, and entity classification.

The partnership should also confirm whether it uses a calendar year or a fiscal year. The filing deadline depends on the partnership’s tax year. Under IRS guidance, Form 1065 is generally due on the 15th day of the third month following the end of the partnership’s tax year. Form 7004 is generally used to request an automatic six-month extension of time to file eligible business returns. IRS 

For a Form 1065 filing, the preparer should also confirm whether the partnership has experienced any significant changes during the year, such as:

  • Admission of a new partner
  • Withdrawal or retirement of a partner
  • Transfer of a partnership interest
  • Change in ownership percentages
  • Change in business activity
  • Merger, restructuring, or dissolution activity
  • Change in accounting method

These details can affect the preparation of the return and the information reported to the partners.

2. Reconcile All Bank and Credit-Card Accounts

Bank reconciliation is one of the most important steps in the Form 1065 filing process.

The partnership should reconcile every business bank account, credit-card account, loan account, and payment platform through the end of the tax year.

Unreconciled accounts may contain duplicate transactions, missing deposits, incorrect withdrawals, bank charges, or transactions recorded in the wrong period.

The review should identify:

  • Outstanding checks
  • Deposits in transit
  • Duplicate transactions
  • Unidentified bank withdrawals
  • Unrecorded bank fees
  • Transfers between accounts
  • Personal transactions
  • Incorrectly dated transactions

A bank balance that agrees with the accounting system does not automatically mean that the books are accurate. The underlying transactions must also be reviewed.

For example, a transfer between two partnership bank accounts should not be recorded as income or an expense. Similarly, a partner’s personal payment of a business expense may need to be recorded as a contribution or payable rather than as an ordinary bank transaction.

A complete reconciliation process gives the tax preparer a more reliable starting point.

3. Review Income and Expense Classification

A partnership’s income and expenses should be reviewed for accuracy, consistency, and proper classification.

The profit and loss statement should be compared with the prior year and with internal management reports. Significant fluctuations should be investigated before the Form 1065 filing is completed.

For example, a sudden increase in repairs and maintenance may actually include equipment purchases that should be reviewed as fixed assets. A large legal expense may require additional documentation. A payment to a partner may have been recorded as an operating expense even though it represents a distribution or another type of transaction.

The partnership should review whether:

  • Revenue has been recorded in the correct period
  • Customer refunds and credits are properly reflected
  • Personal expenses have been excluded or correctly classified
  • Capital expenditures have been separated from operating expenses
  • Meals and travel expenses have appropriate documentation
  • Payroll and contractor expenses agree with supporting records
  • Interest, rent, insurance, and professional fees are correctly classified

A clean income statement is essential, but the tax preparer should not rely on the income statement alone. Some of the most important partnership tax issues arise from balance-sheet accounts and partner transactions.

4. Examine Accounts Receivable and Accounts Payable

Accounts receivable and accounts payable should be reviewed before the Form 1065 filing is finalized.

The accounts receivable aging report can identify old customer balances, disputed invoices, credit balances, and amounts that may require further investigation.

The partnership should determine whether receivables are valid and whether any balances have been collected after year-end. If the partnership uses the accrual method, the timing of revenue recognition and related adjustments may require particular attention.

Accounts payable should also be reviewed for duplicate bills, unpaid expenses, incorrect vendors, and transactions recorded in the wrong accounting period.

The preparer should investigate:

  • Old outstanding customer balances
  • Unusual credit balances
  • Duplicate vendor bills
  • Unrecorded liabilities
  • Large year-end invoices
  • Payments made after year-end
  • Expenses relating to the wrong tax year

These checks help ensure that the financial statements reflect the partnership’s actual position and that relevant tax adjustments are not overlooked.

5. Review Fixed Assets and Depreciation

Fixed assets require special attention because they can affect both the balance sheet and the tax return.

The partnership should compare its fixed-asset register with the general ledger and supporting invoices. Any major purchases, disposals, transfers, or improvements should be reviewed.

The review should cover:

  • Equipment purchases
  • Vehicles
  • Furniture and fixtures
  • Computers and technology
  • Leasehold improvements
  • Buildings and other property
  • Asset disposals
  • Insurance proceeds
  • Trade-ins
  • Depreciation schedules

The book value of an asset may differ from its tax basis. Therefore, the tax preparer should have access to the relevant purchase documents, prior depreciation schedules, disposal information, and any applicable elections.

A missing asset invoice or incorrectly recorded disposal can affect depreciation, gain or loss calculations, and partner reporting.

Before the Form 1065 filing, the partnership should ensure that the fixed-asset records agree with the accounting records and that all significant changes have been communicated to the tax preparer.

6. Verify Loans and Other Liabilities

Loans and liabilities should be reviewed carefully because they can affect both the partnership’s financial position and the information provided to partners.

The partnership should obtain year-end loan statements and reconcile the principal balance, accrued interest, and payments recorded in the accounting system.

The review should distinguish between:

  • Principal repayments
  • Interest expense
  • New borrowings
  • Refinancing transactions
  • Loan fees
  • Related-party loans
  • Partner loans
  • Debt forgiveness
  • Current and long-term portions

A common bookkeeping problem occurs when the entire loan payment is recorded as an expense. Generally, the principal portion reduces the liability, while the interest portion may be recorded separately, subject to applicable tax rules.

Partner loans also require careful documentation. A transaction involving a partner may represent a loan, capital contribution, distribution, or another type of activity. The correct classification depends on the facts and supporting agreement.

These balances should be resolved before the Form 1065 filing is submitted.

7. Reconcile Partner Contributions and Distributions

Partner contributions and distributions are among the most important accounts to review in a partnership.

The accounting records should identify the amount contributed by each partner during the year and the amount distributed to each partner.

The partnership should also distinguish between cash contributions, property contributions, distributions, reimbursements, guaranteed payments, and loans.

The preparer should review:

  • Cash contributions
  • Property contributions
  • Partner draws
  • Cash distributions
  • Property distributions
  • Reimbursements
  • Guaranteed payments
  • Partner-paid expenses
  • Partner loans
  • Transfers of partnership interests

A payment made to a partner is not automatically a deductible business expense. It may instead be a distribution, guaranteed payment, loan repayment, or another transaction.

Incorrect classification can affect the partnership’s taxable income, capital accounts, partner basis information, and Schedule K-1 reporting.

The partnership agreement should be reviewed whenever the allocation or treatment of a transaction is unclear.

8. Review Partner Capital Accounts

Partner capital accounts require a detailed review before the Form 1065 filing.

The partnership should confirm beginning capital balances, current-year contributions, allocations of income or loss, distributions, and ending capital balances.

The preparer should also verify that the accounting records are consistent with the partnership agreement and the method used to report capital accounts.

The IRS instructions explain that Schedule K-1 includes information about a partner’s capital account. However, the capital account reported by the partnership should not automatically be treated as the partner’s adjusted tax basis. Partners have their own responsibility to track the basis of their partnership interests. IRS 

This distinction is important.

A partner’s outside basis may be affected by contributions, distributions, income, losses, and the partner’s share of partnership liabilities. The information shown on Schedule K-1 may support the partner’s analysis, but it does not replace the partner’s complete basis calculation.

Before the Form 1065 filing is completed, the partnership should identify unusual capital account changes and communicate any unresolved issues to the tax preparer.

9. Confirm Profit and Loss Allocations

Partnership income, deductions, gains, losses, and credits must be allocated according to the partnership agreement and applicable tax rules.

The allocation process should be reviewed whenever the partnership has:

  • Different ownership percentages
  • Special allocations
  • New or departing partners
  • Mid-year ownership changes
  • Preferred returns
  • Guaranteed payments
  • Nonstandard distribution arrangements
  • Changes to the partnership agreement

The partnership should not assume that every item is divided according to the same percentage.

For example, ordinary business income may be allocated according to one arrangement while a specific item may require a different allocation under the partnership agreement and applicable tax rules.

The Form 1065 filing should reflect the correct total amounts on Schedule K and the correct partner-specific amounts on each Schedule K-1.

Any special allocation should be supported by the partnership agreement, relevant calculations, and appropriate documentation.

10. Review Schedule K-1 Information

Schedule K-1 is one of the most important components of a partnership tax return.

The partnership uses Schedule K-1 to report each partner’s share of income, deductions, credits, and other relevant tax information. The partnership generally must provide a Schedule K-1 to each partner by the due date of the partnership return, including applicable extensions. IRS 

Before finalizing the Form 1065 filing, the preparer should verify each partner’s:

  • Legal name
  • Address
  • Taxpayer identification number
  • Ownership percentage
  • Profit-sharing percentage
  • Loss-sharing percentage
  • Capital account information
  • Share of liabilities
  • Allocated income and deductions
  • Distributions
  • Specially allocated items

The partnership should also consider whether Schedule K-2 and Schedule K-3 reporting applies. These schedules may be relevant when a partnership has international tax information or certain other activities requiring additional reporting.

Errors in Schedule K-1 information can create problems for partners when they prepare their individual returns. Therefore, the partnership should provide partners with accurate and timely information and establish a process for resolving questions.

11. Identify International and State Tax Issues

A partnership may have tax obligations beyond the federal Form 1065 filing.

State filing requirements can apply based on the partnership’s activities, income, ownership, property, employees, or presence in a particular state. A federal filing extension does not automatically provide the same extension for every state obligation.

The partnership should review whether it has responsibilities involving:

  • State income tax filings
  • Franchise taxes
  • Gross receipts taxes
  • Sales and use tax
  • Payroll tax
  • Nonresident partner withholding
  • Composite tax returns
  • Local tax filings
  • Foreign partners
  • Foreign financial accounts
  • International transactions

Partnerships with foreign partners may have additional withholding and reporting responsibilities. The correct treatment depends on the partnership’s facts and the nature of the partner’s income.

The Form 1065 filing process should therefore include a review of the partnership’s domestic and international activities rather than focusing only on the federal income statement.

12. Maintain Supporting Documentation

Financial figures reported on a partnership tax return should be supported by appropriate records.

The partnership should retain bank statements, invoices, receipts, loan documents, payroll records, fixed-asset records, partnership agreements, ownership records, and other documents supporting the reported amounts.

The IRS instructions state that partnerships generally must keep records for as long as they may be needed for the administration of the Internal Revenue Code. Records supporting an item of income, deduction, or credit are generally kept for a specified period, while records supporting property basis may need to be retained for longer. IRS 

A well-organized document system helps the partnership respond to questions from the tax preparer, partners, lenders, auditors, or tax authorities.

It also reduces the risk of repeated document requests and makes future tax preparation more efficient.

Businesses can use secure digital storage, organized folders, standardized file names, and monthly document collection procedures to keep records accessible throughout the year.

13. Final Form 1065 Filing Review

Before the return is submitted, the partnership should complete a final review that connects the financial statements to the tax forms.

A practical final checklist should include the following steps:

  1. Confirm the partnership’s legal name, EIN, address, and tax year.
  2. Confirm the original filing deadline and extension status.
  3. Reconcile all bank, credit-card, loan, and payment-platform accounts.
  4. Review revenue and expenses for unusual transactions or incorrect classifications.
  5. Confirm accounts receivable and accounts payable balances.
  6. Reconcile fixed assets and depreciation schedules.
  7. Verify loans, accrued liabilities, and related-party balances.
  8. Review partner contributions, distributions, loans, and reimbursements.
  9. Confirm beginning and ending partner capital accounts.
  10. Review income, loss, deduction, and credit allocations.
  11. Verify partner ownership information and Schedule K-1 details.
  12. Determine whether Schedule K-2 or Schedule K-3 reporting applies.
  13. Review state, local, international, and withholding obligations.
  14. Confirm that supporting documents are complete and properly stored.
  15. Obtain final approval from the partnership and submit the return through the appropriate process.

This final review can help identify inconsistencies before they become filing problems.

Frequently Asked Questions

What is the purpose of Form 1065?

Form 1065 is used by partnerships to report income, gains, losses, deductions, credits, and other information to the IRS. Partnership income and other tax items generally pass through to the partners.

When is Form 1065 generally due?

Form 1065 is generally due on the 15th day of the third month after the end of the partnership’s tax year. Calendar-year partnerships generally have a March filing deadline, while an eligible extension can move the filing deadline later in the year. IRS 

Does a partnership extension provide more time to pay tax?

A partnership generally does not pay federal income tax on its income at the entity level in the same way as a C corporation. However, partners may have individual tax obligations relating to their shares of partnership income. Other partnership-level taxes, withholding obligations, and state liabilities may still apply.

Why are partner capital accounts important?

Partner capital accounts help track contributions, allocations, and distributions. They are important for financial reporting and Schedule K-1 preparation, although a partner’s capital account is not automatically the same as the partner’s adjusted tax basis.

What is the difference between Schedule K and Schedule K-1?

Schedule K reports the partnership’s total distributive shares of income, deductions, credits, and other items. Schedule K-1 reports each individual partner’s share of those items.

Can bookkeeping errors affect a partnership tax return?

Yes. Incorrect bookkeeping can affect taxable income, balance-sheet accounts, partner capital accounts, distributions, liabilities, depreciation, and Schedule K-1 information.

Should a partnership review state requirements separately?

Yes. State filing and payment requirements can differ from federal rules. A partnership should review the requirements of every state and locality where it has relevant activities or obligations.

Conclusion

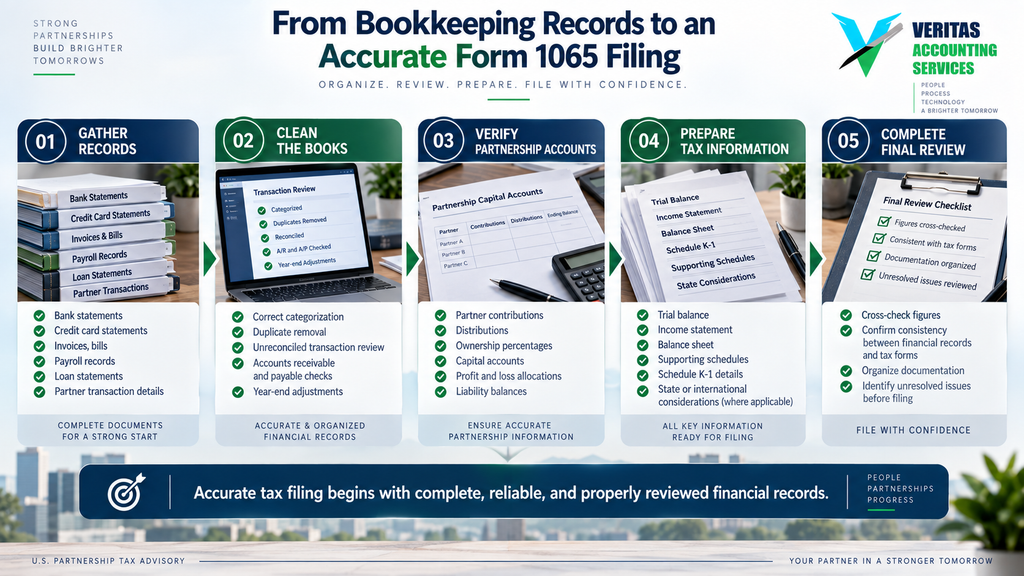
A successful Form 1065 filing depends on more than completing the tax forms before the deadline. It requires reliable accounting records, accurate partner information, appropriate allocations, complete documentation, and a careful review of financial accounts.

Partnerships should reconcile their books, review income and expenses, verify fixed assets and liabilities, examine partner contributions and distributions, and confirm that capital accounts and Schedule K-1 information are accurate.

The process should also include a review of state, local, international, and withholding responsibilities where applicable.

For CPA firms, completing these checks early can reduce last-minute questions, minimize rework, and improve the quality of the final tax return. For partnerships, it can provide greater confidence that the information delivered to the IRS and the partners is complete and consistent.

At Veritas Accounting Services, we support businesses and CPA firms with bookkeeping, accounting, financial reporting, tax preparation support, and outsourced accounting services. Reliable bookkeeping throughout the year can make the Form 1065 filing process more efficient and help tax professionals focus on review, compliance, and advisory work.

To prepare for your next partnership tax return, begin with the financial records rather than the tax software. A well-reviewed set of books is the foundation of a more accurate and efficient filing process.

Important: Tax requirements can vary depending on the partnership’s structure, tax year, ownership, activities, state obligations, international transactions, and other circumstances. This article is intended for general educational purposes and should not replace advice from a qualified U.S. tax professional.

GET IN TOUCH

Schedule a FREE Call

What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Your Simple Guide to Unpaid Invoice Mistakes and Better Records

An unpaid customer invoice is not automatically a tax deduction. Review the tax accounting method…

Connect on our Socials!

extended tax return

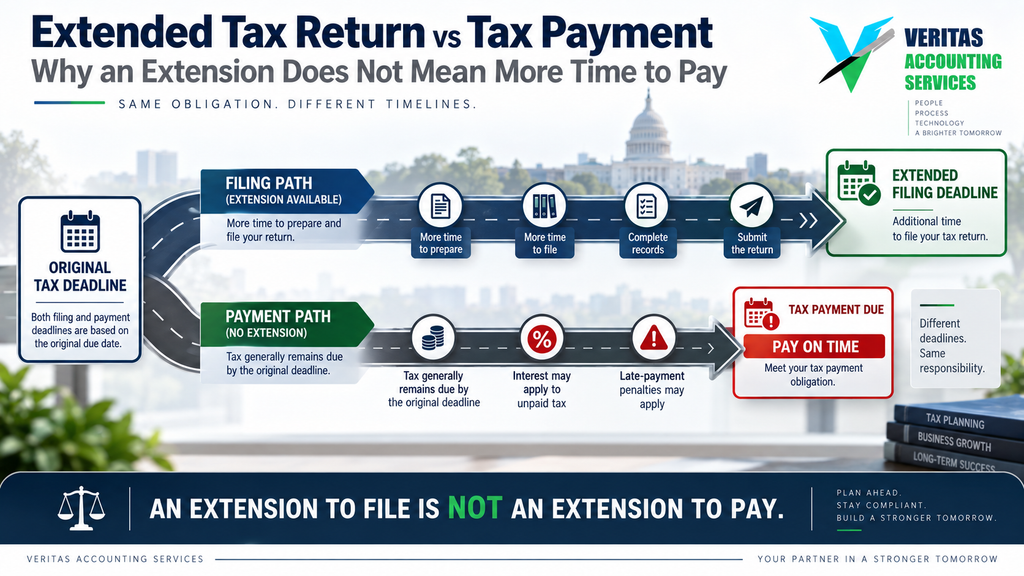
Extended Tax Return vs Tax Payment: Why an Extension Does Not Mean More Time to Pay

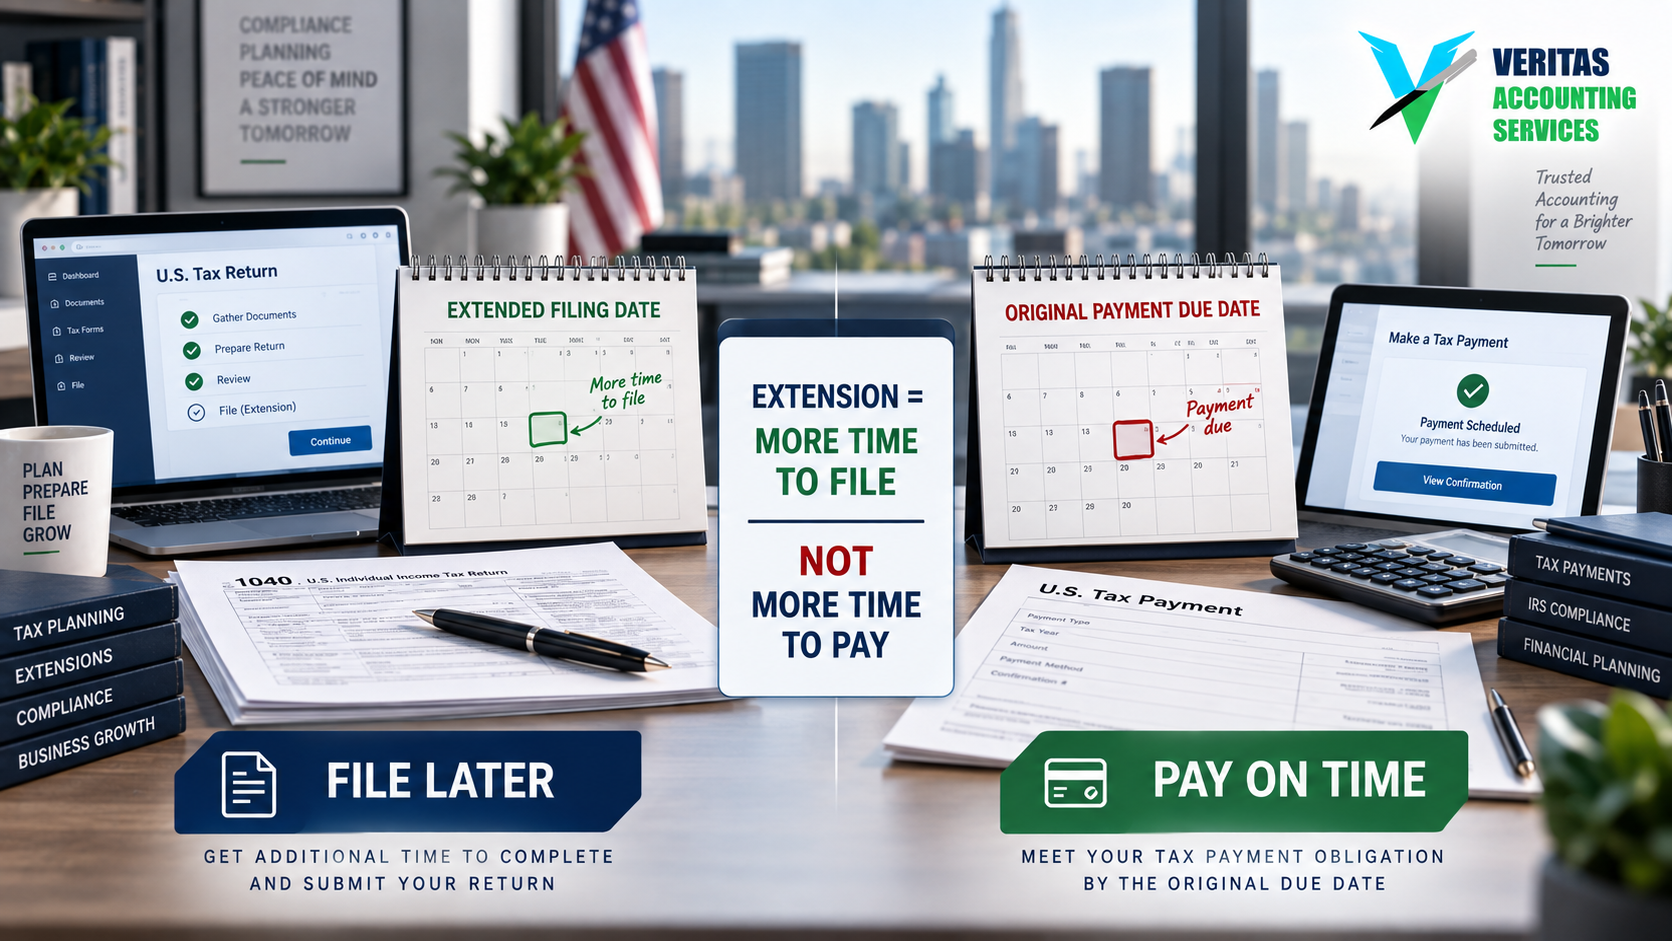
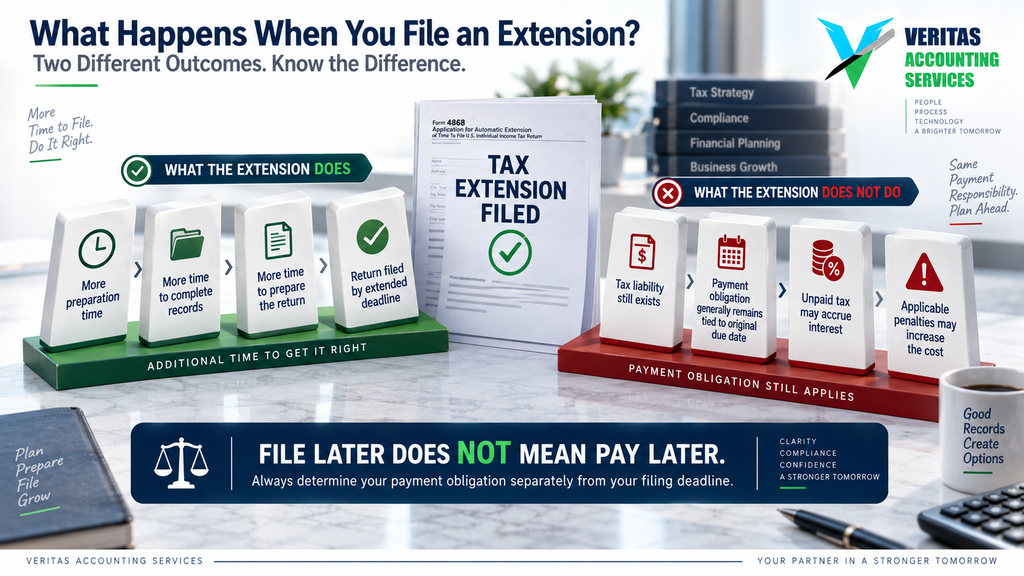
A tax extension can be extremely useful for a business that needs additional time to complete its tax return. But there is one important distinction that business owners often misunderstand: more time to file does not generally mean more time to pay.

An extended tax return allows an eligible taxpayer to postpone the filing of the return. The tax liability itself generally remains due by the original payment deadline.

The distinction matters because a business may file its return several months after the original deadline while still being responsible for tax, interest, and potentially penalties from the original due date.

The IRS is explicit about this distinction. Its instructions for Form 7004 state that the form does not extend the time to pay tax due. Interest generally applies to unpaid tax from the original due date until the tax is paid.

For U.S. businesses approaching an extended filing deadline, understanding the difference between filing and payment can prevent an expensive misunderstanding.

This article explains how tax extensions work, when payment is due, what happens when the final liability is higher than expected, and what businesses should do before an extension deadline.

Table of Contents

  1. What Is a Tax Extension?
  2. Filing Deadline vs Payment Deadline
  3. How Business Tax Extensions Work
  4. Why Tax Is Still Due by the Original Deadline
  5. What Happens If You Pay Less Than You Owe?
  6. Interest and Late-Payment Penalties
  7. How to Estimate the Amount to Pay
  8. Common Mistakes Businesses Make
  9. What CPA Firms Should Tell Their Clients
  10. Practical Checklist Before an Extended Filing Deadline
  11. Frequently Asked Questions
  12. Conclusion

What Is a Tax Extension?

A tax extension is a mechanism that gives an eligible taxpayer additional time to file a tax return.

For certain business returns, Form 7004 is used to request an automatic extension of time to file. The IRS describes Form 7004 as an application for an automatic extension for certain business income tax, information, and other returns.

The purpose of an extension is primarily to provide additional time to prepare accurate and complete information.

For example, a partnership may still be waiting for financial records, a business may need additional time to reconcile its books, or a tax preparer may require more time to finalize complex schedules.

An extension can therefore reduce the pressure of preparing a return by the original filing date.

However, an extended tax return should not be interpreted as a postponement of the underlying tax liability.

That is where the difference between filing and payment becomes important.

Filing Deadline vs Payment Deadline

There are two separate questions every business should ask:

When does the return need to be filed?

When does the tax need to be paid?

These dates may be different.

The extension generally changes the first date. It does not automatically change the second.

The IRS states that an extension of time to file is not an extension of time to pay. For individual taxpayers, the IRS similarly advises that taxes owed should generally be paid by the original filing deadline even when an extension is requested.

This distinction is particularly important when a business expects to owe federal income tax.

A taxpayer who waits until the extended filing date to make the entire payment may find that interest has accumulated from the original due date.

For businesses, this can also affect cash-flow planning. A company may have several additional months to finalize its return but still need to reserve funds for the tax liability much earlier.

How Business Tax Extensions Work

For many business taxpayers, Form 7004 provides an automatic extension for eligible returns when properly filed by the original due date.

The extension period depends on the specific return and taxpayer circumstances. Businesses should therefore confirm the applicable period rather than assuming that every return receives the same extension.

For example, a calendar-year partnership or S corporation may have an extended filing deadline later in the year. This is why September becomes an important filing period for many U.S. businesses.

The additional filing time can be valuable.

It allows the business and tax professional to:

  • complete bookkeeping;
  • reconcile accounts;
  • gather missing records;
  • review transactions;
  • prepare supporting schedules;
  • resolve tax questions; and
  • finalize the return accurately.

But none of these steps should create confusion about the payment obligation.

The business should separately determine whether tax was due by the original deadline and whether an estimated payment should have been made.

Why Tax Is Still Due by the Original Deadline

The basic principle is straightforward: the extension provides additional time to complete the paperwork, not additional time to settle an existing tax liability.

The IRS explains that Form 7004 does not extend the time to pay tax due. Its current instructions also explain that interest is charged on unpaid tax from the original due date until the tax is paid.

Consider a simple example.

A business estimates that it will owe $40,000 in federal tax. It requests an extension because its books and supporting records are not ready.

The business now has additional time to complete the return.

That does not automatically mean it can keep the $40,000 until the extended filing deadline without consequences.

If the business does not pay the tax when required, interest may begin accumulating from the original due date.

This is why businesses should treat the filing extension and payment obligation as two separate tasks.

What Happens If You Pay Less Than You Owe?

Estimating tax before the return is finalized is not always easy.

A business may make an estimated payment based on its available financial information and later discover that the actual tax liability is higher.

That does not necessarily mean the original payment was incorrect.

Tax returns often involve deductions, credits, depreciation, owner information, state adjustments, and other items that can affect the final liability.

However, any unpaid tax generally remains subject to applicable interest from the original due date.

The IRS also explains that late-payment penalties can apply when tax is not paid by the due date. The specific penalty depends on the taxpayer and circumstances.

The important point is that businesses should not avoid making a reasonable payment simply because the final return is not ready.

If the tax liability is uncertain, the business should work with its tax professional to develop a reasonable estimate.

Interest and Late-Payment Penalties

The financial consequences of waiting to pay can include both interest and penalties.

IRS guidance states that underpayment interest generally begins from the due date of the unpaid amount and continues until the balance is paid. This applies even when the taxpayer has received an extension to file.

The IRS instructions for Form 7004 also explain that a late-payment penalty can generally apply to tax that remains unpaid after the due date.

The exact amount depends on the taxpayer’s circumstances, the amount unpaid, applicable safe-harbor or payment rules, and other factors.

For certain corporations, there are specific rules concerning whether sufficient tax was paid by the original due date. The Form 7004 instructions, for example, describe a rule under which a corporation may avoid a late-payment penalty if the required percentage of tax was paid by the original deadline and the remaining balance is paid by the extended filing date.

Because these rules can vary, businesses should not assume that one payment strategy applies to every entity.

How to Estimate the Amount to Pay

One of the most practical steps before an extension deadline is estimating the expected tax liability.

This does not require the final tax return to be complete.

Instead, the business and tax preparer can use current financial information to develop a reasonable estimate.

Start with the year-to-date profit and loss statement and balance sheet. Then review significant transactions that may affect taxable income.

Consider:

  1. Current-year revenue and profitability.
  2. Major expenses and potential deductions.
  3. Depreciation and fixed-asset activity.
  4. Payroll and shareholder compensation.
  5. Owner or partner transactions.
  6. Estimated tax payments already made.
  7. Prior-year tax information.
  8. Significant changes in business operations.

The quality of this estimate depends heavily on the quality of the underlying bookkeeping.

If the books contain unreconciled accounts, missing transactions, or incorrect classifications, the estimated liability may be less reliable.

This is why tax planning and bookkeeping should not be treated as completely separate processes.

Common Mistakes Businesses Make

One of the most common mistakes is assuming that filing an extension means the business has no tax obligation until the extended filing date.

Another is waiting until the return is completely prepared before considering payment.

Businesses may also underestimate the liability because their financial statements are not current.

A further problem occurs when owners focus only on federal income tax and overlook state obligations.

State tax rules vary significantly, and a federal extension does not necessarily provide the same treatment for every state filing or payment.

Businesses operating across multiple states should review their state requirements separately.

Another mistake is failing to retain payment confirmations.

Tax payments should be properly documented and reconciled to the accounting records so the tax preparer can accurately reflect payments when completing the return.

What CPA Firms Should Tell Their Clients

CPA firms play an important role in helping clients understand the difference between filing and paying.

A client who says, “I filed an extension, so I can pay in September,” may have misunderstood the purpose of the extension.

The CPA should clearly explain that the extension primarily provides additional filing time and that tax payment obligations generally remain tied to the original deadline.

This conversation should happen before the original payment deadline whenever possible.

For CPA firms, proactive communication can also reduce later questions about interest and penalties.

A standardized client communication can explain:

  • what the extension covers;
  • what it does not cover;
  • the estimated tax liability;
  • the recommended payment amount;
  • the payment method;
  • the consequences of underpayment; and
  • what information is still needed to complete the return.

This creates a clearer process for both the firm and the client.

Practical Checklist Before an Extended Filing Deadline

Before an extended tax return is finalized, the business should review both filing and payment status.

Confirm that the extension was properly filed and accepted.

Review the estimated tax liability and compare it with payments already made.

Reconcile the accounting records through the relevant period.

Confirm that all major income and expense accounts have been reviewed.

Check shareholder, partner, and owner transactions.

Review fixed assets, loans, and other significant balance-sheet accounts.

Confirm federal and state filing requirements separately.

Provide missing documents and responses to the tax preparer.

Finally, confirm that all required tax payments have been made and properly recorded.

The objective is not simply to submit the return on time. It is to ensure that the return, payment records, and accounting records all tell the same story.

Frequently Asked Questions

Does an extension give a business more time to pay taxes?

Generally, no. An extension provides additional time to file an eligible return, but it does not generally extend the time to pay tax due. The IRS specifically states that Form 7004 does not extend the time to pay tax.

What happens if I cannot pay the full tax amount?

A taxpayer who cannot pay the full amount should still address the liability promptly. The IRS provides payment options for taxpayers who cannot immediately pay their full balance. Interest and applicable penalties can continue until the balance is paid.

Does interest apply if I filed an extension?

Yes. IRS guidance states that interest generally applies to unpaid tax from the original due date until payment is made, even when an extension was granted.

Can a business estimate its tax payment?

Yes. Businesses commonly estimate their expected tax liability before the final return is completed. The estimate should be based on reliable financial information and reviewed with the business’s tax professional.

What form is commonly used for a business filing extension?

Form 7004 is used to request an automatic extension for certain business income tax, information, and other returns.

Does a federal extension automatically extend state taxes?

Not necessarily. State filing and payment requirements can differ from federal rules. Businesses should confirm the requirements in each state where they have tax obligations.

Conclusion

The difference between filing and paying is one of the most important concepts businesses should understand when requesting a tax extension.

An extended tax return gives the taxpayer additional time to complete and submit the return. It does not generally provide additional time to pay the underlying tax liability.

That distinction matters because unpaid tax can lead to interest and potentially penalties from the original payment deadline.

Businesses can reduce the risk by keeping accurate books, estimating their liability before the original deadline, making appropriate payments, and communicating with their tax professional early.

For CPA firms, explaining this distinction clearly can also improve client relationships and reduce confusion when extended returns are finalized.

An extension should be viewed as a tool for completing an accurate return, not as a way to postpone the tax payment itself.

If your business needs support with bookkeeping, tax preparation, tax compliance, or U.S. tax filing, Veritas Accounting Services can help organize the financial information and tax workflow needed to manage these obligations more efficiently.

Important: Tax rules can vary based on entity type, tax year, state, payment history, and individual circumstances. This article is for general educational purposes and should not replace advice from a qualified tax professional. Always verify the applicable rules with the IRS and relevant state tax authorities.

Official IRS resources: IRS Form 7004 Instructions · IRS Topic No. 304 — Extensions of Time to File · IRS — Pay Taxes on Time

GET IN TOUCH

Schedule a FREE Call

What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Your Simple Guide to Unpaid Invoice Mistakes and Better Records

An unpaid customer invoice is not automatically a tax deduction. Review the tax accounting method…

Connect on our Socials!

September tax deadlines

September Tax Deadlines Are Approaching: A Practical Guide for U.S. Businesses

Introduction

September is one of the most important months on the U.S. tax calendar for many businesses. While April is widely recognized as the main tax season, September brings another significant filing period, particularly for partnerships and S corporations that received extensions.

For business owners, September is not simply about submitting a tax return. It is also a time to review accounting records, confirm estimated tax payments, resolve outstanding bookkeeping issues, gather missing documents, and make sure federal and state obligations have been considered.

The September tax deadlines can create considerable pressure when financial records are incomplete or tax documents arrive late. A return may technically have an extension, but that does not mean the business has unlimited time to organize its records.

For calendar-year businesses, September 15, 2026, is particularly important. The IRS lists that date for extended calendar-year Form 1065 and Form 1120-S returns when a timely six-month extension was requested. It is also an estimated tax payment date for individuals and corporations under the applicable rules.

Understanding what is due and preparing early can make the difference between a controlled filing process and a last-minute scramble.

Table of Contents

  1. Why September Is Important for U.S. Businesses
  2. Key September Tax Deadlines for 2026
  3. Form 1065 and Partnership Returns
  4. Form 1120-S and S Corporation Returns
  5. Estimated Tax Payments
  6. Other September Tax and Compliance Obligations
  7. Why Bookkeeping Matters Before Filing
  8. Common Problems That Delay Tax Returns
  9. How Businesses Can Prepare for September
  10. How CPA Firms Can Manage September Workload
  11. Frequently Asked Questions
  12. Conclusion

Why September Is Important for U.S. Businesses

The U.S. tax system operates on different deadlines depending on the entity type, tax year, filing requirement, and taxpayer circumstances.

For many calendar-year partnerships and S corporations, the original filing deadline occurs earlier in the year. If the business properly requested an extension, the extended filing deadline generally moves to September.

That creates a concentrated workload for business owners and CPA firms.

The September tax deadlines are also important because tax filing is connected to other financial responsibilities. A business may need to make estimated tax payments, provide Schedule K-1 information to owners or partners, complete state filings, make payroll-related deposits, or address specialized federal reporting requirements.

The IRS 2026 tax calendar specifically identifies September 15 as a major date for several business-related filings and payments.

The important point is that an extension should be viewed as additional preparation time, not as a reason to postpone preparation until September.

Key September Tax Deadlines for 2026

For calendar-year taxpayers, September 15, 2026, is one of the most significant dates on the tax calendar.

The IRS lists the following obligations for September 15, subject to the taxpayer’s circumstances:

Form 1065

Calendar-year partnerships that timely requested a six-month extension generally need to file their 2025 Form 1065 by September 15, 2026.

Form 1120-S

Calendar-year S corporations that timely requested an extension generally need to file their 2025 Form 1120-S by September 15, 2026.

Estimated tax payments

September 15 is also the third estimated tax payment date for 2026 under the standard calendar-year schedule. The IRS identifies June 1 through August 31 as the third estimated-tax payment period, with payment generally due September 15.

These are not the only September obligations. Depending on the business, there can be additional federal filings, withholding requirements, payroll deposits, and state-level obligations.

Therefore, businesses should create a deadline calendar based on their specific entity structure and activities rather than relying on one generic tax date.

Form 1065 and Partnership Returns

Partnerships are particularly important during the September filing period.

Form 1065 reports the partnership’s income, deductions, gains, losses, and other relevant information. The partnership generally does not pay federal income tax at the entity level in the same way a C corporation does. Instead, income and other tax information generally flow through to the partners.

That makes accurate bookkeeping especially important.

If the partnership’s bank accounts have not been reconciled, partner contributions and distributions are unclear, or balance-sheet accounts contain unexplained transactions, the tax preparer may have to spend additional time resolving accounting issues before completing the return.

Schedule K-1 information is also important because partners generally need it for their own tax reporting.

For businesses approaching the September tax deadlines, the best practice is to make sure the accounting records are substantially complete before the tax preparation process reaches its final stage.

A good review should include bank reconciliations, credit-card accounts, accounts receivable, accounts payable, loans, fixed assets, owner transactions, and unusual income or expenses.

Form 1120-S and S Corporation Returns

S corporations are another major part of the September filing cycle.

The IRS states that Form 1120-S is generally due on the 15th day of the third month following the end of the corporation’s tax year. A timely Form 7004 can generally provide an automatic six-month extension.

For an S corporation, tax preparation often requires careful review of shareholder activity, compensation, distributions, loans, fixed assets, business expenses, and other transactions.

Bookkeeping errors can complicate that process.

For example, a shareholder distribution may have been recorded as an expense. A shareholder loan may have been posted incorrectly. Payroll records may not agree with the accounting system. Fixed assets may not have been properly classified.

These issues may not be obvious when simply reviewing the profit and loss statement.

That is why September preparation should include a balance-sheet review, not just a review of income and expenses.

Estimated Tax Payments

One of the most important September tax deadlines is the third estimated tax payment date.

For 2026, the IRS lists September 15 as the due date for the third estimated tax installment under the standard calendar-year schedule.

Estimated tax requirements can apply to individuals who receive income without sufficient withholding, including certain self-employed individuals, partners, and S corporation shareholders. Corporations may also have estimated tax obligations when they expect to owe sufficient tax.

The amount of the payment should be considered carefully.

A business owner whose income has increased significantly during the year may need to reassess estimated payments. The same can apply when profitability has declined, a major deduction has occurred, or the business has experienced a significant change in operations.

The IRS notes that insufficient estimated payments can result in a penalty even when a taxpayer ultimately receives a refund when filing the annual return.

Current financial statements therefore have value beyond management reporting. They can provide the tax professional with better information for estimating the year’s tax position.

Other September Tax and Compliance Obligations

The September tax deadlines extend beyond Forms 1065 and 1120-S.

The IRS September calendar includes a range of other federal obligations depending on the taxpayer’s circumstances. These include certain payroll tax deposits, Form 1042 filings, partnership Forms 8804 and 8805, Form 8813 payments, Form 2290 filings, and other specialized requirements.

For example, Form 2290 may apply to businesses operating certain heavy highway vehicles. The IRS calendar lists September 30, 2026, as the filing and payment date for vehicles first used during August.

International businesses may also have additional reporting or withholding obligations.

State compliance requires separate attention. A federal filing extension does not automatically mean that every state filing, estimated payment, franchise tax, or other state obligation follows exactly the same rules.

Businesses operating across multiple states should therefore review each state’s requirements independently.

Why Bookkeeping Matters Before Filing

Tax preparation starts with accounting records.

If the books are incomplete, the tax preparer may have to spend significant time determining what happened before even beginning the tax review.

This becomes particularly important during the September tax deadlines because CPA firms often manage a large volume of extended returns at the same time.

Common bookkeeping issues include unreconciled bank accounts, uncategorized transactions, missing loan statements, incorrect owner transactions, old accounts receivable, duplicate expenses, and unexplained balance-sheet balances.

A tax professional can resolve these issues, but doing so consumes time and can increase the cost of preparing the return.

A stronger approach is to maintain the books throughout the year.

Monthly reconciliation, timely document collection, and regular financial review allow businesses to identify problems much earlier. When September arrives, the accounting records should ideally require review and adjustment rather than reconstruction.

For CPA firms, this also protects valuable professional capacity. CPAs can spend more time on tax analysis, planning, client communication, and advisory work when they are not spending deadline week rebuilding a client’s bookkeeping records.

Common Problems That Delay Tax Returns

Several problems repeatedly create pressure during the September filing period.

Incomplete financial records

Businesses sometimes provide their tax preparer with books that have not been fully reconciled. This creates additional work before the tax return can be finalized.

Missing supporting documents

Loan statements, fixed-asset invoices, expense records, payroll reports, and other documents may still be outstanding.

Unexplained balance-sheet accounts

Old receivables, stale checks, unidentified liabilities, shareholder loans, and clearing accounts can require investigation.

Incorrect owner transactions

Owner draws, distributions, capital contributions, and loans may be recorded incorrectly, particularly in small businesses.

Late responses from clients

Even when the accounting records are ready, tax preparation can be delayed because the preparer is waiting for answers to important questions.

State filing confusion

Businesses operating in several states may overlook state-specific filing or payment requirements because they focus only on the federal return.

These problems are manageable when identified early. They become much more difficult when discovered immediately before a deadline.

How Businesses Can Prepare for September

Businesses approaching the September tax deadlines should begin with a practical review of their financial records.

Start by confirming the exact tax forms that apply to the business and whether an extension was properly filed.

Next, review the accounting records through the latest completed month. Make sure bank and credit-card accounts have been reconciled and investigate significant unexplained balances.

Then gather supporting documents. Tax preparers should not have to repeatedly request basic information that could have been organized in advance.

The business should also review estimated payments made during the year and discuss the current-year tax position with its tax professional.

Finally, prepare a separate list of federal, state, payroll, and industry-specific obligations. This reduces the risk of focusing on one deadline while overlooking another.

A simple checklist can turn a stressful tax period into a manageable workflow.

How CPA Firms Can Manage September Workload

For CPA firms, September can be one of the busiest periods of the year.

The challenge is not simply the number of returns. It is the amount of cleanup and follow-up required before those returns can be completed.

A CPA firm can reduce pressure by establishing clear client deadlines well before the filing date.

It can also separate bookkeeping from tax preparation. Recurring bookkeeping, reconciliations, transaction classification, and financial reporting can be handled by a dedicated bookkeeping team while CPAs focus on tax review and advisory responsibilities.

Outsourced bookkeeping can be particularly useful when a CPA firm has seasonal demand but does not want to carry the full cost of additional year-round employees.

The right outsourcing partner should understand U.S. accounting practices, follow documented procedures, maintain confidentiality, communicate clearly, and work within the CPA firm’s existing review process.

For firms preparing for the September tax deadlines, the goal should not be simply to complete the current workload. It should be to build a process that makes the next filing season easier.

Frequently Asked Questions

What is the main September tax deadline for U.S. businesses?

September 15 is a major deadline in 2026. It includes extended calendar-year Form 1065 and Form 1120-S returns for taxpayers that timely requested extensions, along with certain estimated tax payments.

Does filing an extension mean taxes can be paid later?

Generally, an extension of time to file does not automatically provide an extension of time to pay tax that is due. Businesses should determine their payment obligations separately.

Who needs to make estimated tax payments?

Estimated tax rules can apply to individuals, self-employed taxpayers, partners, S corporation shareholders, and corporations depending on their expected tax liability and circumstances.

Are federal and state tax deadlines the same?

No. State filing and payment requirements can differ from federal requirements. Businesses should review the rules applicable to every state in which they have filing obligations.

Why should businesses complete bookkeeping before tax preparation?

Clean and reconciled accounting records reduce the amount of time required to investigate transactions and allow tax professionals to focus on tax reporting, review, and planning.

Can a CPA firm outsource bookkeeping work?

Yes. CPA firms can outsource recurring bookkeeping, cleanup, reconciliations, and accounting support to an experienced provider. The arrangement should include clear responsibilities, quality controls, secure information handling, and appropriate review procedures.

Conclusion

The September tax deadlines are an important reminder that U.S. tax compliance is a year-round process.

For many businesses, September brings together extended partnership and S corporation returns, estimated tax payments, payroll obligations, state requirements, and specialized federal filings.

The businesses that handle September smoothly generally do not start preparing in September. They maintain their books throughout the year, organize supporting documents, monitor tax obligations, and communicate with their tax professionals before deadlines become urgent.

For CPA firms, the same principle applies.

Reliable bookkeeping processes can reduce cleanup work, improve turnaround times, protect CPA capacity, and create more room for tax planning and advisory services.

If your business or CPA firm is preparing for the September tax deadlines, now is the time to review your accounting records, identify missing information, and resolve outstanding questions.

Veritas Accounting Services supports U.S. businesses and CPA firms with bookkeeping, accounting, U.S. tax preparation, tax support, and outsourced accounting services.

Important: Tax deadlines can vary based on entity type, tax year, extension status, state requirements, and individual circumstances. Businesses should verify their specific obligations with the IRS, applicable state tax authorities, or a qualified tax professional. The IRS 2026 tax calendar should be consulted for current federal deadlines.

GET IN TOUCH

Schedule a FREE Call
What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Your Simple Guide to Unpaid Invoice Mistakes and Better Records

An unpaid customer invoice is not automatically a tax deduction. Review the tax accounting method…

Connect on our Socials!

outsourced accounting

Why Bookkeeping Cleanup Is Eating Into CPA Firm Profitability

Behind every successful tax return, audit, or financial report is one critical foundation: clean bookkeeping.

Yet across the United States, CPA firms are quietly fighting a growing operational problem — bookkeeping cleanup chaos.

Most firms are no longer spending their time on advisory services or strategic accounting. Instead, they are stuck fixing incomplete books, correcting reconciliations, chasing client documents, and cleaning years of financial errors before deadlines hit.

The issue is not a lack of accounting knowledge. The real problem is operational breakdowns, inconsistent systems, and increasingly messy bookkeeping environments.

Today, modern CPA firms face far more than traditional bookkeeping. They deal with multi-state tax complexity, e-commerce reconciliations, payroll corrections, offshore coordination, and AI-driven data quality issues — all while clients expect faster turnaround times.

Below are the 10 biggest bookkeeping cleanup problems draining time, margins, and productivity inside U.S. CPA firms today.


1. Client Document Delays

One of the biggest drivers of bookkeeping cleanup chaos is delayed client communication.

Business Performance Metrics

CPA firms constantly struggle with:

  • Missing bank statements
  • Delayed payroll reports
  • Incomplete expense documentation
  • Unorganized receipts

When documents arrive late, month-end closings fall behind, reconciliations remain incomplete, and cleanup work piles up near tax deadlines.

The result:

  • Staff burnout
  • Rushed reviews
  • Reduced profitability

Many firms spend more time chasing clients than performing actual accounting work.


2. Payroll Reconciliation Errors

Payroll errors create serious cleanup problems because they affect:

  • Financial statements
  • Payroll tax filings
  • W-2 accuracy
  • Employee liabilities

Common issues include:

  • Duplicate payroll entries
  • Incorrect payroll mapping
  • Tax payment mismatches
  • Uncleared payroll liabilities

Fixing payroll reconciliations often requires tracing transactions across payroll platforms, bank feeds, and accounting software.

This type of bookkeeping cleanup chaos becomes even more dangerous during audits or year-end reporting.


3. Sales Tax Nexus Confusion

Sales tax compliance has become one of the most difficult bookkeeping areas for CPA firms.

Businesses operating across multiple states often trigger:

  • Economic nexus
  • Marketplace facilitator rules
  • State-specific filing obligations

Many clients:

  • Do not understand nexus rules
  • Fail to register correctly
  • Collect incorrect sales tax
  • Miss filing deadlines

CPA firms then inherit massive cleanup work involving:

  • Historical transaction reviews
  • State-by-state corrections
  • Late filing calculations

Sales tax errors are no longer small compliance issues — they are major financial risks.


4. Multi-State Bookkeeping Complexity

Modern businesses rarely operate in just one state.

Remote work, e-commerce, and digital services have created:

  • Multi-state payroll exposure
  • State tax allocation challenges
  • Apportionment complications

For CPA firms, this creates bookkeeping complexity far beyond simple transaction categorization.

Without standardized systems, firms face:

  • Incorrect state coding
  • Missing allocations
  • Duplicate reporting errors

Multi-state bookkeeping has become a major source of operational inefficiency.


5. QuickBooks Cleanup Chaos

QuickBooks remains one of the most widely used accounting platforms — but poorly maintained QuickBooks files create enormous cleanup problems. Why Bookkeeping Cleanup Chaos Is Growing ?

Common issues include:

  • Duplicate transactions
  • Broken chart of accounts
  • Misclassified expenses
  • Negative balances
  • Reconciliation discrepancies

Many firms inherit books that have not been reviewed for months or even years.

Instead of performing strategic accounting, teams spend hours repairing damaged bookkeeping files before real work can begin.

This is one of the most visible forms of bookkeeping cleanup chaos affecting CPA firms today.


6. E-Commerce Reconciliation Problems

bookkeeping cleanup chaos

E-commerce bookkeeping is no longer simple.

Businesses selling through:

  • Shopify
  • Amazon
  • Stripe
  • PayPal
  • Walmart Marketplace

generate thousands of transactions with:

  • Fees
  • Refunds
  • Chargebacks
  • Multi-channel deposits

Many businesses record only bank deposits without understanding platform-level reconciliation.

CPA firms must then untangle:

  • Gross sales
  • Merchant fees
  • Inventory adjustments
  • Sales tax liabilities

E-commerce cleanup projects have become one of the most time-consuming bookkeeping areas in modern accounting.


7. Lack of Month-End Closing Systems

Many businesses operate without a structured month-end close process.

This creates:

  • Unreconciled accounts
  • Missing accruals
  • Incomplete financials
  • Reporting delays

Without monthly review systems, bookkeeping errors accumulate quietly throughout the year.

Then during tax season or audits, CPA firms face:

  • Massive catch-up work
  • Time pressure
  • Increased risk of mistakes

A strong month-end close system is one of the most effective ways to reduce bookkeeping cleanup chaos.


8. AI + Bookkeeping Quality Control Problems

Automation and AI tools are transforming bookkeeping — but they are also creating new risks.

bookkeeping cleanup chaos

AI-powered systems can:

  • Auto-categorize transactions
  • Sync bank feeds
  • Generate reports quickly

However, automation without review creates:

  • Incorrect categorizations
  • Duplicate entries
  • Hidden reconciliation problems

Many firms now spend significant time reviewing AI-generated bookkeeping errors instead of preventing them proactively.

Technology improves efficiency only when quality control systems exist.


9. Offshore Bookkeeping Management Challenges

Many CPA firms rely on offshore bookkeeping teams to manage workload and improve scalability. Why Bookkeeping Cleanup Chaos Is Growing ?

While outsourcing creates efficiency, it also introduces:

  • Communication gaps
  • Process inconsistencies
  • Review bottlenecks
  • Time zone delays

Without proper SOPs and review systems, offshore workflows can contribute to bookkeeping cleanup chaos instead of solving it.

Successful firms build:

  • Standardized procedures
  • Clear documentation systems
  • Layered review processes

Offshore bookkeeping succeeds only when operational control remains strong.


10. Revenue Recognition Mistakes

Revenue recognition remains one of the most misunderstood bookkeeping areas that grows Bookkeeping Cleanup Chaos.

Common issues include:

  • Incorrect accrual timing
  • Deferred revenue errors
  • Subscription revenue misstatements
  • Partial project recognition mistakes

These problems are especially common in:

  • SaaS businesses
  • Service industries
  • Construction companies
  • Subscription models

Incorrect revenue recognition affects:

  • Financial statements
  • Profitability analysis
  • Tax reporting
  • Investor reporting

CPA firms often discover these issues only during cleanup reviews.


Why Bookkeeping Cleanup Chaos Is Growing

The bookkeeping environment has fundamentally changed.

CPA firms now manage:

  • More software platforms
  • More compliance rules
  • Faster client expectations
  • Larger transaction volumes

At the same time, many businesses still treat bookkeeping as simple data entry.

The result is operational overload.

Firms are spending valuable hours fixing preventable bookkeeping problems instead of focusing on:

  • Advisory services
  • Strategic growth
  • Client relationships

How CPA Firms Can Reduce Cleanup Chaos

The solution is not simply hiring more staff.

Modern firms need:

  • Standardized bookkeeping systems
  • Monthly closing procedures
  • Automated workflows with human review
  • Clear client communication processes
  • Quality control checkpoints

The firms that scale successfully are the ones that build operational discipline around bookkeeping.


Final Thoughts

The real accounting crisis today is not tax law complexity — it is bookkeeping cleanup chaos.

From payroll errors and sales tax nexus issues to QuickBooks cleanup and offshore management, CPA firms are losing time and profitability fixing avoidable bookkeeping problems.

Firms that solve these operational issues will gain:

  • Better margins
  • Faster turnaround times
  • Stronger client relationships
  • Greater scalability

Because clean bookkeeping is no longer just administrative work — it is the foundation of modern accounting success.

GET IN TOUCH

Schedule a FREE Call
What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Your Simple Guide to Unpaid Invoice Mistakes and Better Records

An unpaid customer invoice is not automatically a tax deduction. Review the tax accounting method…

Connect on our Socials!

due diligence

Due Diligence for Business Owners: How to Get Your Financial House in Order

Most business owners do not think seriously about financial scrutiny until a buyer, investor, lender or strategic partner asks for detailed records.

Suddenly, questions start appearing.

Are the books accurate? Are all bank accounts reconciled? Can the company explain its revenue growth? Are tax returns available? Are there outstanding liabilities? Which customers generate the most revenue? Are contracts properly documented?

These questions are not necessarily a sign that something is wrong.

They are part of understanding the business before an important financial decision is made.

For owners, the real lesson is simple: a business should be organized before someone asks to inspect it.

Good preparation can reduce delays, uncover problems early and give management greater confidence in its own numbers.

It can also reveal weaknesses that may affect the value of the company, even if a sale or investment is not currently being considered.

Table of Contents

  1. What Is Due Diligence?
  2. Why Financial Records Matter
  3. Start With Your Bookkeeping
  4. Reconcile Bank and Credit Card Accounts
  5. Review Accounts Receivable and Payable
  6. Organize Tax Records
  7. Review Revenue and Expenses
  8. Identify Debt and Other Liabilities
  9. Organize Contracts and Business Documents
  10. Strengthen Internal Controls
  11. Prepare Management Reporting
  12. Common Red Flags
  13. How Accounting Professionals Can Help
  14. A Practical Readiness Checklist
  15. FAQ
  16. Conclusion

What Is Due Diligence?

Due diligence is a structured review of a business before a major financial or commercial decision.

A potential buyer may use it to verify the company’s financial performance and understand its risks. An investor may want to evaluate whether the business is worth funding. A lender may examine its ability to repay debt.

The scope varies by situation, but a review can include:

  • Financial statements
  • Bank accounts
  • General ledger
  • Revenue
  • Expenses
  • Accounts receivable
  • Accounts payable
  • Tax records
  • Payroll
  • Debt
  • Contracts
  • Assets
  • Legal obligations
  • Internal controls

The purpose is not to prove that a business has no weaknesses.

Very few businesses are completely free of risks.

The purpose is to understand those risks, verify the information presented by management and determine whether anything could materially affect the proposed transaction.

Why Financial Records Matter

Financial records tell the story of a business.

If the accounting records are accurate, consistent and well supported, an outside reviewer can understand how the company generates revenue, where it spends money and how cash moves through the organization.

Consider two businesses with similar revenue and profitability.

The first has reconciled accounts, organized supporting documents, consistent financial statements and clearly documented liabilities.

The second has old reconciliation items, inconsistent expense classifications, missing documents and unclear balances.

Both may be economically healthy, but the first business will generally be easier to evaluate.

This is why due diligence preparation should not begin when a buyer appears.

It should be part of normal financial management.

Start With Your Bookkeeping

The general ledger is one of the first areas management should review.

Ask some basic questions:

  • Are all bank accounts included?
  • Are credit cards properly recorded?
  • Are transactions categorized consistently?
  • Are old suspense balances still outstanding?
  • Are owner transactions clearly identified?
  • Are loans correctly recorded?
  • Are fixed assets up to date?
  • Are intercompany balances properly accounted for?

Small bookkeeping errors can accumulate.

For example, if personal expenses are regularly mixed with company expenses, profitability may be distorted. If loan payments are recorded incorrectly, liabilities and interest expenses may not be accurate.

A clean ledger makes financial reporting more reliable and reduces the amount of explanation required later.

Professional bookkeeping is therefore more than transaction entry. It creates a financial record that management and external stakeholders can understand.

due diligence

Reconcile Bank and Credit Card Accounts

Bank reconciliation is a fundamental financial control.

Every business bank account should be reconciled regularly. Credit cards and other financial accounts should receive the same attention.

Look for:

  • Old outstanding checks
  • Unidentified deposits
  • Duplicate transactions
  • Unusual transfers
  • Bank fees
  • Old reconciling items
  • Incorrect credit card balances

An old reconciliation difference may seem insignificant, but unexplained balances can raise questions about the reliability of the accounting records.

During due diligence, reviewers may want to understand why the cash reported on the balance sheet differs from the bank records.

Resolving these issues before an external review is much easier than trying to explain years of unresolved differences later.

Review Accounts Receivable and Payable

Accounts receivable deserves particular attention.

A company may report a large receivable balance, but that does not necessarily mean all of the money will be collected.

Management should review:

  • Current invoices
  • Overdue balances
  • Long-outstanding accounts
  • Disputed invoices
  • Related-party balances
  • Potential bad debts

Accounts payable should also be reviewed.

Identify unpaid vendor invoices, disputed amounts, old balances and obligations that may not be obvious from a quick review of the financial statements.

A realistic view of working capital helps management understand the company’s actual financial position.

It also makes due diligence discussions more straightforward because management can explain the quality of its receivables and obligations.

Organize Tax Records

Tax documentation should be easy to locate.

Depending on the business and jurisdictions involved, relevant records may include:

  • Federal or national tax returns
  • State or local filings
  • Sales tax or VAT returns
  • Payroll tax filings
  • Information returns
  • Tax payment records
  • Tax registrations
  • Notices from tax authorities
  • Open tax matters

Missing documentation does not necessarily mean the company has a tax problem.

However, it can create uncertainty.

Business owners should maintain a clear record of filings, payments, notices and outstanding matters.

Tax records should also agree with the underlying accounting records wherever appropriate.

If the financial statements report one position while tax records suggest another, management should be able to explain the difference.

Review Revenue and Expenses

Revenue is normally one of the most important areas for an external reviewer.

Business owners should be able to explain:

  • Where revenue comes from
  • Which customers contribute the most
  • Whether revenue is recurring
  • Whether pricing has changed
  • Whether unusual one-time transactions occurred
  • Whether customer concentration is significant

Expenses deserve similar attention.

Review major expense categories and investigate unusual changes.

Ask whether costs are:

  • Recurring or one-time
  • Properly classified
  • Business-related
  • Supported by documentation
  • Consistent with previous periods

A business should be able to explain its own financial story.

If revenue increased significantly, management should know why.

If gross margin declined, management should understand the cause.

If cash decreased despite higher profits, management should be able to explain the working-capital movement.

This level of understanding demonstrates financial discipline.

Identify Debt and Other Liabilities

A company’s financial health cannot be evaluated by looking only at revenue and profit.

Management should understand all significant obligations.

Review:

  • Bank loans
  • Lines of credit
  • Equipment financing
  • Credit cards
  • Lease commitments
  • Tax liabilities
  • Accrued expenses
  • Customer deposits
  • Employee-related obligations
  • Guarantees
  • Other contractual commitments

Some obligations may not be immediately obvious from a basic profit-and-loss report.

A complete review helps management identify its actual financial exposure.

During due diligence, undisclosed or poorly understood liabilities can become a major source of concern.

Transparency is therefore important.

Organize Contracts and Business Documents

Financial statements tell only part of the story.

Important contracts and legal documents should also be organized.

These may include:

  • Customer agreements
  • Supplier contracts
  • Lease agreements
  • Employment agreements
  • Insurance policies
  • Loan documents
  • Licensing agreements
  • Intellectual property records
  • Partnership or shareholder agreements

Management should know which agreements are active, when they expire and whether they contain obligations that could affect the business.

Customer concentration is another important consideration.

If one customer represents a substantial percentage of revenue, the business should understand the contractual relationship and the potential risk if that customer leaves.

Good documentation makes the business easier to understand.

Strengthen Internal Controls

As businesses grow, financial controls become increasingly important.

Review who has authority to:

  • Access bank accounts
  • Approve payments
  • Create vendors
  • Process refunds
  • Modify accounting records
  • Approve expenses
  • Process payroll
  • Post journal entries

A small company may initially operate largely on trust.

That can work for a period of time, but growing organizations need clear responsibilities and appropriate checks.

Internal controls do not need to create unnecessary bureaucracy.

The objective is to reduce errors, limit fraud risk and ensure that important financial activities have appropriate oversight.

Strong controls can also demonstrate that the business is professionally managed.

Prepare Management Reporting

Historical financial statements are important, but management should also understand what is happening today.

Useful management reports can include:

  • Monthly profit and loss
  • Balance sheet
  • Cash-flow report
  • Budget versus actual
  • Accounts receivable aging
  • Accounts payable aging
  • Gross-margin analysis
  • Revenue by customer
  • Revenue by product or service
  • Key performance indicators

The numbers should not simply be produced.

Management should understand them.

For example, if revenue increased by 20%, what caused the increase?

If profitability declined, was the reason pricing, labor, materials or overhead?

If cash flow weakened, was it caused by lower sales or slower collections?

This analytical understanding can make due diligence much more efficient because the owner can answer questions with confidence.

Common Red Flags

Not every issue will stop a transaction, but certain patterns can attract additional scrutiny.

Unreconciled Accounts

Old differences can suggest weaknesses in financial controls.

Large Owner Transactions

Personal and business expenses that are not clearly separated can complicate financial analysis.

Old Receivables

Long-outstanding invoices may not represent realistic future cash collections.

Missing Tax Records

Incomplete documentation can create uncertainty about potential liabilities.

Unusual Revenue Patterns

Large one-time transactions may require additional explanation.

Customer Concentration

Heavy dependence on one customer can create business risk.

Poor Documentation

If management cannot quickly locate supporting records, the review may take longer.

The purpose of identifying these issues is not to hide them.

It is to find them early, understand their impact and correct them where possible.

How Accounting Professionals Can Help

Financial preparation can require considerable time.

Business owners are already managing customers, employees, operations and growth. As a result, accounting cleanup can remain on the priority list without receiving enough attention.

An experienced accounting team can help bring structure to the financial side of the business.

Support may include:

  • Bookkeeping cleanup
  • Bank reconciliation
  • Credit-card reconciliation
  • General ledger review
  • Accounts receivable analysis
  • Accounts payable review
  • Financial statement preparation
  • Management reporting
  • Cash-flow forecasting
  • Tax record organization
  • Financial analysis

At Veritas Accounting Services, we work with businesses and professional firms that need bookkeeping, accounting, tax support, financial reporting and outsourced finance services.

Our role is not simply to make the books look organized when a transaction is approaching.

The objective is to establish reliable financial processes throughout the year.

That approach makes due diligence less stressful because the company is maintaining its financial records continuously instead of reconstructing several years of information at the last minute.

Professional support can also help management identify accounting issues that may otherwise remain hidden.

A Practical Readiness Checklist

Business owners can use the following checklist to evaluate their preparedness.

Financial Records

☐ Books are current
☐ Bank accounts are reconciled
☐ Credit cards are reconciled
☐ General ledger has been reviewed
☐ Old balances have been investigated
☐ Fixed assets are properly recorded

Working Capital

☐ Accounts receivable aging is reviewed
☐ Uncollectible balances are identified
☐ Accounts payable is current
☐ Customer deposits are understood
☐ Working-capital trends are documented

Tax and Compliance

☐ Tax returns are organized
☐ Payroll filings are available
☐ Sales tax or VAT records are available where applicable
☐ Tax liabilities are reconciled
☐ Tax notices are documented

Business Documents

☐ Customer contracts are organized
☐ Supplier agreements are available
☐ Loan documents are current
☐ Lease agreements are accessible
☐ Insurance documents are available
☐ Ownership documents are organized

Management Information

☐ Monthly financial statements are available
☐ Cash-flow reporting is current
☐ Budgets and forecasts are maintained
☐ Major revenue changes are understood
☐ Major expense changes are understood
☐ Key performance indicators are tracked

Completing this checklist does not guarantee a successful transaction.

It does, however, put management in a stronger position to respond to questions and demonstrate control over the company.

FAQ

What is due diligence in a business transaction?

It is the process of examining a company’s financial, operational, legal and other relevant information before a transaction, investment, financing arrangement or major business decision.

How far back can a review go?

The period varies depending on the transaction, industry and circumstances. Buyers and investors may examine several years of financial information.

What financial records should a business maintain?

Businesses should maintain organized financial statements, general ledgers, bank reconciliations, accounts receivable and payable records, tax documentation, debt information and supporting transaction records.

Can bookkeeping problems affect a business sale?

Yes. Inaccurate or incomplete books can make financial performance difficult to verify, create additional questions and potentially delay negotiations.

Should owners wait until a buyer asks for records?

No. Maintaining accurate books and organized documentation throughout the year is much more efficient than attempting to reconstruct records when an external review begins.

Can an accounting firm help prepare a business?

Yes. An experienced accounting firm can help clean up bookkeeping, reconcile accounts, organize financial records, prepare management reports and identify potential financial issues. Legal and tax matters should be reviewed with the appropriate qualified professionals.

Conclusion

A well-managed business should not need a crisis to discover what is happening inside its own financial records.

Preparing for external scrutiny is valuable even when no sale or investment is currently planned.

Clean bookkeeping, reconciled accounts, organized tax records, documented contracts, understood liabilities and consistent management reporting create a stronger business.

They also improve everyday decision-making.

When owners know their numbers, they can identify profitable customers, manage expenses, improve collections and make better decisions about hiring and investment.

This is one of the biggest benefits of preparing for due diligence before it becomes necessary.

At Veritas Accounting Services, we help businesses and professional firms maintain accurate bookkeeping, accounting, tax support, financial reporting, budgeting, forecasting and outsourced finance functions.

The objective is not simply to make a business look prepared for an external reviewer.

It is to help create a business that is financially organized, transparent and ready for its next opportunity.

Whether that opportunity is a new investor, a bank relationship, an acquisition, a strategic partnership or simply the next stage of growth, preparation creates options.

The best time to get your financial house in order is before someone asks to inspect it.

GET IN TOUCH

Schedule a FREE Call
What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Your Simple Guide to Unpaid Invoice Mistakes and Better Records

An unpaid customer invoice is not automatically a tax deduction. Review the tax accounting method…
Family Business Succession

Family Business Succession: How to Transfer Leadership Without Disrupting the Business

Building a family business can take decades.

The founder may have started with a small operation, built relationships with customers and employees, reinvested profits, survived difficult economic periods and gradually created an organization that supports an entire family.

Eventually, however, every successful family business faces an important question:

What happens when the person who built the business is ready to step away?

This is where family business succession becomes important.

A leadership transition is much more than changing the name of the person at the top. It can affect employees, customers, suppliers, ownership, financial decisions and the overall direction of the company.

If the transition is rushed, the business can lose valuable knowledge and create uncertainty among employees and customers.

If it is planned properly, the next generation can gradually take responsibility while the founder continues to provide guidance during the transition.

The objective is not simply to replace one leader with another.

It is to create a business that can continue performing successfully after the founder’s role changes.

Table of Contents

  1. Why Succession Planning Should Start Early
  2. Leadership and Ownership Are Different
  3. Choosing the Right Successor
  4. Preparing the Next Generation
  5. Create a Gradual Leadership Transition
  6. Protect Employees and Customer Relationships
  7. Prepare the Business Financially
  8. Review Ownership and Tax Considerations
  9. Document the Founder’s Knowledge
  10. What If the Next Generation Is Not Ready?
  11. The Role of Professional Advisors
  12. A Practical Succession Roadmap
  13. FAQ
  14. Conclusion

Why Succession Planning Should Start Early

One of the biggest mistakes families make is waiting until the founder is ready to retire before starting the conversation.

At that point, there may be limited time to train a successor, restructure ownership, document processes or resolve disagreements among family members.

Good family business succession planning can begin years before an actual transition.

Starting early gives the business time to:

  • Identify potential successors
  • Develop leadership capabilities
  • Improve financial reporting
  • Document critical processes
  • Clarify ownership expectations
  • Review tax considerations
  • Communicate with important stakeholders
  • Create contingency plans

Starting early also gives the founder an opportunity to test the transition gradually.

A potential successor can take responsibility for a department, major customer relationship or strategic project while the founder remains available as a mentor.

This creates a much more controlled transition than simply announcing a new leader on a particular date.

Leadership and Ownership Are Different

One of the most important considerations in family business succession is understanding that ownership and leadership do not have to be transferred together.

For example, parents may transfer ownership interests to their children while an experienced family member or non-family executive manages daily operations.

Another possibility is that one family member becomes CEO while another remains an owner but does not participate in management.

This distinction creates flexibility.

The best person to inherit ownership may not necessarily be the best person to manage employees, customers and operations.

Similarly, the strongest operational leader may not need to hold the majority ownership interest.

A well-designed family business succession plan should therefore answer two separate questions:

Who should own the business?

Who should run the business?

Sometimes the answer will be the same person.

Sometimes it should not be.

Choosing the Right Successor

Family relationships can make this decision difficult.

Parents may naturally want their children to continue the business. However, leadership should ultimately be based on capability, commitment and readiness.

Potential successors should be evaluated on:

  • Leadership ability
  • Industry knowledge
  • Financial understanding
  • Communication skills
  • Strategic thinking
  • Decision-making
  • Employee management
  • Customer relationships
  • Ability to handle pressure
  • Commitment to the long-term business

Being a family member does not automatically make someone ready to become the CEO.

A son or daughter may eventually become an excellent leader but still require additional experience and development.

A strong family business succession process identifies these gaps early instead of discovering them after the founder has already stepped away.

Preparing the Next Generation

A successor should understand more than the part of the company they currently manage.

If someone is expected to lead the entire organization, they should understand how different functions work together.

That includes:

  • Sales
  • Operations
  • Finance
  • Human resources
  • Customer service
  • Technology
  • Cash flow
  • Profitability
  • Risk management

Financial understanding is especially important.

Future leaders should know how to read financial statements and understand the difference between revenue, gross profit, operating profit and cash flow.

They should also understand working capital, accounts receivable, debt and major business expenses.

This makes family business succession more than a leadership-development exercise. It becomes an opportunity to build the next generation of financially informed decision-makers.

family business succession

Create a Gradual Leadership Transition

A sudden change at the top can create uncertainty.

Employees may ask whether their responsibilities will change. Customers may wonder whether service will remain consistent. Suppliers and lenders may want reassurance.

A gradual transition can reduce these concerns.

A practical approach may include four stages.

Stage 1: Observe

The successor works closely with the founder and learns how major decisions are made.

Stage 2: Participate

The successor takes responsibility for selected departments, customers or projects.

Stage 3: Lead

The successor begins making important operational decisions while the founder becomes less involved in daily activities.

Stage 4: Transition

The successor assumes primary leadership while the founder moves into an advisory, ownership or board role.

This approach gives everyone time to adjust.

It also allows the founder to discover whether the successor is genuinely ready before making the final transition.

Protect Employees and Customer Relationships

A business transition is not only an internal family matter.

Employees, customers, suppliers and other stakeholders may have strong relationships with the founder.

Some customers may have worked with the company for decades. Employees may have joined because they trusted the founder personally.

Therefore, communication should be part of the family business succession strategy.

Management should consider:

  • When employees should be informed
  • Which customers need personal communication
  • How responsibilities will change
  • Who will manage important relationships
  • How customer service will remain consistent
  • How employee concerns will be addressed

The objective is to create confidence.

The message should be that the business is changing leadership while preserving the strengths that made it successful.

Prepare the Business Financially

Financial readiness is one of the most overlooked aspects of succession planning.

Before a leadership or ownership transition, the company’s financial records should be reliable and current.

That includes:

  • Accurate bookkeeping
  • Reconciled bank accounts
  • Properly recorded liabilities
  • Updated accounts receivable
  • Clear debt information
  • Reliable financial statements
  • Current budgets
  • Cash-flow forecasts
  • Management reporting

A successor should not have to depend entirely on the founder’s memory to understand the financial position of the company.

This is why financial preparation is an important part of family business succession.

Good financial records create institutional knowledge that stays with the organization even when people change.

They also help the family and its advisors evaluate the company’s value, financial capacity and future requirements.

Review Ownership and Tax Considerations

Ownership transfers can create significant financial, legal and tax considerations.

The appropriate structure depends on factors such as the country, business entity, ownership arrangement and method of transfer.

Potential areas to review may include:

  • Business valuation
  • Sale or transfer of ownership
  • Gift considerations
  • Estate planning
  • Capital gains
  • Tax basis
  • Buy-sell agreements
  • Financing arrangements
  • Insurance
  • Shareholder agreements

These matters should not be handled informally simply because the parties are family members.

The accounting team can provide financial information and support valuation analysis, while qualified legal and tax professionals can advise on the applicable structure and requirements.

Bringing these professionals into the family business succession process early can give the family more time to evaluate alternatives.

Document the Founder’s Knowledge

Founders often possess knowledge that never appears in the company’s manuals.

They know:

  • Which customers require special attention
  • Which suppliers are reliable
  • How important relationships were established
  • Why certain decisions were made
  • Which employees have specialized knowledge
  • How unusual operational problems are handled

This knowledge can disappear quickly when a founder steps away.

The solution is documentation.

Important processes should be written down and transferred gradually to the next generation.

Consider documenting:

  • Customer onboarding
  • Vendor management
  • Financial approvals
  • Billing and collections
  • Banking procedures
  • Payroll processes
  • Month-end closing
  • Tax coordination
  • Key operating procedures

Documenting these processes makes the company less dependent on one individual.

It also makes the family business succession process significantly more manageable.

What If the Next Generation Is Not Ready?

Sometimes the preferred successor is simply not prepared.

That does not mean the business must be transferred immediately.

The family may consider:

  • Extending the development period
  • Hiring a non-family executive
  • Creating a co-leadership arrangement
  • Bringing in an external CEO
  • Maintaining family ownership while professional managers run operations
  • Selling the business in the future

The objective of family business succession should always be the long-term health of the company.

Family ownership can continue even if daily management is handled by an experienced non-family professional.

In some cases, that may actually protect both the business and family relationships.

family business succession

The Role of Professional Advisors

A successful transition often requires several different types of expertise.

An accountant can help ensure that the financial records are accurate and up to date.

A tax professional can evaluate the tax implications of potential ownership transfers.

A lawyer can assist with agreements and legal documentation.

A financial advisor can help with personal wealth and estate considerations.

A CFO or financial consultant can help management understand profitability, cash flow, valuation drivers and future financial requirements.

At Veritas Accounting Services, we support businesses with bookkeeping, accounting, financial reporting, budgeting, forecasting, tax support and CFO-related services.

During a transition, our role can include maintaining clean financial records, preparing management reports, analyzing business performance and giving the incoming leadership team reliable financial information.

This support can make family business succession less dependent on the founder’s personal knowledge.

The objective is not to replace the family’s role.

It is to give the family and incoming management better information for better decisions.

A Practical Succession Roadmap

A family business can begin preparing with this practical roadmap.

Step 1: Start the Conversation

Discuss long-term ownership and leadership expectations before an immediate transition becomes necessary.

Step 2: Identify Potential Successors

Evaluate family members and other potential leaders based on capability, interest and readiness.

Step 3: Develop the Successor

Provide exposure to different areas of the business and gradually increase responsibility.

Step 4: Strengthen Financial Reporting

Ensure bookkeeping, financial statements, cash-flow reports and management information are reliable.

Step 5: Document Critical Processes

Transfer important institutional knowledge from the founder to the organization.

Step 6: Review Legal and Tax Structures

Work with qualified professionals to evaluate ownership transfers and related considerations.

Step 7: Communicate With Stakeholders

Prepare employees, customers, suppliers and other key parties for the transition.

Step 8: Transfer Responsibility Gradually

Allow the successor to take increasing responsibility while the founder reduces day-to-day involvement.

Step 9: Define the Founder’s Future Role

The founder may become an advisor, board member, shareholder or completely step away.

Step 10: Review the Plan Regularly

Business conditions and family circumstances change, so the plan should be revisited periodically.

FAQ

What is family business succession?

Family business succession is the process of preparing for the future transfer of leadership, management and potentially ownership from one generation or group of family members to another.

When should a family business start succession planning?

Ideally, planning should begin several years before the expected transition. Early preparation gives the family time to develop successors, strengthen systems and address financial, legal and tax considerations.

Does the next generation have to run the business?

No. Ownership and management can be separated. A family can retain ownership while appointing a qualified family member or external professional to manage operations.

Why are financial records important during succession?

Accurate financial records help the incoming leadership team understand profitability, cash flow, assets, liabilities and the overall financial position of the business.

Can an accounting firm help with family business succession?

Yes. An experienced accounting firm can maintain accurate books, prepare financial statements, support business-performance analysis and provide management reporting. Tax and legal matters should be coordinated with the appropriate qualified professionals.

Conclusion

A family business represents more than financial assets.

It often represents decades of work, relationships, reputation and a family’s long-term financial future.

That is why family business succession should be approached as a planned business transition rather than a last-minute handover.

The strongest plans do not focus only on who will inherit the company.

They consider who should lead it, how that person will be prepared, how employees and customers will be protected, and whether the company’s financial and operational systems are ready for the next stage.

Start early.

Develop the next generation.

Separate ownership from management when appropriate.

Document important processes.

Strengthen financial reporting.

And involve qualified accounting, tax and legal professionals before major decisions are finalized.

At Veritas Accounting Services, we help businesses maintain accurate bookkeeping, accounting, financial reporting, budgeting, forecasting and outsourced finance support.

This gives current and future leaders reliable information to understand the business and make informed decisions.

Ultimately, successful family business succession is not about replacing one person with another.

It is about building an organization strong enough to succeed when the founder is no longer running the day-to-day business.

GET IN TOUCH

Schedule a FREE Call
What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Your Simple Guide to Unpaid Invoice Mistakes and Better Records

An unpaid customer invoice is not automatically a tax deduction. Review the tax accounting method…

Global Business

Global Business Growth: The Hidden Challenges of Operating Across Borders

Expanding into another country can be one of the most exciting stages in a company’s development. New markets can create additional revenue, access to new customers, international talent and opportunities that simply do not exist in the domestic market.

But global business growth also changes the way a company needs to operate.

A business that was relatively easy to manage in one country can become significantly more complicated when it starts operating across several jurisdictions. Multiple currencies, tax systems, payroll rules, banking relationships and reporting requirements can quickly create a level of complexity that management did not anticipate.

The challenge is not simply entering another market.

The challenge is maintaining financial visibility, compliance and operational control while the business becomes more international.

For business owners, understanding these challenges early can make international expansion much more manageable.

Table of Contents

  1. Why International Expansion Changes the Business
  2. Managing Multiple Currencies
  3. Accounting Across Different Countries
  4. Tax and Compliance Complexity
  5. International Payroll and Employees
  6. Banking and Cross-Border Payments
  7. Intercompany Transactions and Transfer Pricing
  8. Financial Reporting and Management Visibility
  9. Internal Controls Across Borders
  10. Communication and Operational Challenges
  11. What Should You Outsource?
  12. How Professional Accounting Teams Can Help
  13. A Practical Framework for International Expansion
  14. FAQ
  15. Conclusion

Why International Expansion Changes the Business

In a domestic business, many processes can be relatively straightforward.

The company may have one primary currency, one banking environment, one payroll system and a familiar tax structure.

Once operations cross borders, the picture changes.

A growing international company may need to manage:

  • Multiple currencies
  • Different tax systems
  • Foreign bank accounts
  • Local payroll requirements
  • Different accounting requirements
  • Multiple legal entities
  • Cross-border transactions
  • Intercompany payments
  • International contracts
  • Country-specific compliance

Each requirement may be manageable individually. The difficulty comes from managing them simultaneously and consistently.

This is why global business growth can create pressure even when revenue and customer numbers are increasing.

A company can be growing successfully from a sales perspective while its financial and administrative infrastructure is falling behind.

Managing Multiple Currencies

Currency management is one of the first issues international businesses encounter.

A company may receive revenue in U.S. dollars, pay suppliers in euros, maintain a bank account in British pounds and prepare consolidated reports in another currency.

That creates important accounting and management questions.

Which exchange rate should be applied?

How should foreign-currency transactions be recorded?

How should realized and unrealized foreign-exchange gains or losses be treated?

How should management compare profitability between countries when exchange rates are constantly changing?

Currency movements can also affect cash flow.

For example, a foreign subsidiary may increase its local revenue while the parent company’s reporting-currency results appear weaker because of exchange-rate movements.

Management therefore needs reporting that helps distinguish actual operating performance from currency movements.

Without this visibility, business owners may make decisions based on numbers that do not tell the complete story.

Accounting Across Different Countries

International expansion also changes the role of bookkeeping and accounting.

Different jurisdictions may have different accounting practices, statutory requirements and documentation standards.

Even when a group uses a common internal reporting structure, local requirements may still need to be addressed.

The key is consistency.

Management should be able to answer questions such as:

  • How much revenue did each country generate?
  • Which entity is profitable?
  • Where is cash being held?
  • What does each entity owe?
  • Which customers have unpaid balances?
  • Which costs are increasing?
  • How does each market compare with the group?

A standardized chart of accounts and consistent bookkeeping procedures can make this information much easier to analyze.

The objective is not necessarily to make every country’s accounting identical.

The objective is to produce reliable and comparable information for decision-making.

For global business growth, that distinction becomes increasingly important.

Global Business

Tax and Compliance Complexity

Tax is another major consideration when a company begins operating internationally.

Depending on its activities, a business may have obligations in its home country as well as other jurisdictions.

Potential areas may include:

  • Corporate income tax
  • Sales tax or VAT
  • Payroll taxes
  • Withholding taxes
  • Tax registrations
  • Information reporting
  • Local filings
  • Cross-border transactions
  • Permanent-establishment considerations
  • Transfer pricing

The exact requirements depend on the countries involved and the structure of the business.

That is why businesses should not wait until a filing deadline to determine what obligations apply.

A better approach is to identify requirements before entering a new market, assign responsibility, maintain documentation and coordinate with qualified professionals in each relevant jurisdiction.

Tax compliance should be part of the expansion strategy—not an administrative task addressed after the business has already entered the market.

International Payroll and Employees

Hiring employees internationally can provide access to valuable skills and help businesses establish a presence in new markets.

It also introduces additional responsibilities.

Employment and payroll rules can vary significantly from one country to another.

Businesses may need to consider:

  • Payroll taxes
  • Social contributions
  • Employment classifications
  • Benefits
  • Leave requirements
  • Local employment agreements
  • Reporting requirements
  • Currency of payment
  • Employee documentation

Payroll also connects directly with accounting.

Employee costs need to be accurately recorded and reflected in management reporting.

As international teams grow, companies should establish a consistent process for collecting payroll information from each country and incorporating it into their financial reporting.

Poor coordination between payroll and accounting can lead to inaccurate expenses, cash-flow forecasts and profitability analysis.

Banking and Cross-Border Payments

International businesses also need strong control over how money moves.

A company may have several bank accounts across different countries, each with different currencies, fees, payment processes and reconciliation requirements.

This can lead to:

  • Unreconciled transactions
  • Duplicate payments
  • Unidentified bank charges
  • Delayed transfers
  • Foreign-exchange costs
  • Weak approval procedures
  • Poor visibility over cash

Management should know more than the company’s total cash balance.

It should understand where the cash is located, which entity owns it and how readily it can be used.

A consolidated cash-flow report can help management understand working capital requirements and make better decisions about investments, transfers and operating expenses.

Strong bank reconciliation procedures are equally important because small errors across multiple accounts can become significant when they accumulate over time.

Intercompany Transactions and Transfer Pricing

As companies establish subsidiaries or related entities, transactions between those entities become more common.

For example:

  • One entity may provide management services to another.
  • A parent company may fund a subsidiary.
  • One entity may purchase inventory from another.
  • A central office may allocate shared costs across locations.

These transactions require appropriate accounting and documentation.

Transfer pricing can also become an important consideration when related entities operate in different tax jurisdictions.

Businesses should be able to explain:

  • What service or product was provided?
  • Which entity benefited?
  • How was the transaction priced?
  • How was it recorded?
  • What documentation supports the transaction?
  • What local requirements apply?

Poorly documented intercompany transactions can create unnecessary accounting and tax risks.

This is one area where coordination between accounting and tax professionals can provide significant value.

Financial Reporting and Management Visibility

One of the hidden risks of international expansion is losing visibility into the business.

A company may receive one type of report from its U.S. operation, another from Europe and another from Asia.

Each report might be individually accurate, yet management may struggle to compare them.

A strong international finance function should establish standardized management reporting.

Useful reports may include:

  • Consolidated profit and loss
  • Balance sheet
  • Cash-flow reports
  • Country-level profitability
  • Accounts receivable aging
  • Accounts payable
  • Budget versus actual
  • Revenue by market
  • Gross-margin analysis
  • Key performance indicators

This allows leadership to view the organization as one connected business rather than several unrelated operations.

As global business growth accelerates, financial visibility becomes more important—not less.

Internal Controls Across Borders

Geographic expansion also increases the number of places where financial errors can occur.

Different employees may access different systems. Payments may be processed from different countries. Documentation may be stored across multiple platforms.

Appropriate internal controls should cover areas such as:

  • Bank access
  • Payment approvals
  • Vendor setup
  • Expense approvals
  • Journal entries
  • User permissions
  • Account reconciliations
  • Financial close procedures

Controls do not need to make the organization bureaucratic.

The goal is to create a reasonable balance between control and efficiency.

A growing company should regularly review whether its internal controls still match the size and complexity of its operations.

Communication and Operational Challenges

Not every international challenge involves finance.

Time zones can make meetings difficult. Cultural differences can influence communication and expectations. Teams in different locations may develop their own working habits.

Even basic processes can become inconsistent.

One finance team might close its books on the fifth working day while another takes two weeks.

One manager might expect weekly reporting while another works with monthly information.

These differences can create confusion.

Standard operating procedures, reporting calendars, shared documentation and clearly assigned responsibilities can create consistency without preventing local teams from operating effectively.

Good international operations require both global standards and reasonable local flexibility.

Global Business

What Should You Outsource?

International expansion does not mean every capability needs to be built internally.

In fact, hiring a complete accounting, tax and finance team in every country may not be financially practical.

Business owners should evaluate each function based on:

Complexity + Frequency + Risk + Expertise Required + Cost

Some responsibilities need daily internal involvement and should remain within the organization.

Others can be handled efficiently by experienced external professionals.

Common outsourced functions include:

  • Bookkeeping
  • Accounts payable
  • Accounts receivable
  • Bank reconciliation
  • Payroll support
  • Tax compliance support
  • Financial reporting
  • Budgeting
  • Cash-flow forecasting
  • CFO advisory

Outsourcing can therefore become a useful part of global business growth when it provides access to expertise without unnecessarily increasing fixed overhead.

However, outsourcing should not mean losing control.

The business should establish clear deliverables, deadlines, review procedures, communication expectations and data-security requirements.

How Professional Accounting Teams Can Help

International businesses often need more than someone to record transactions.

They need reliable financial information that management can use.

An experienced outsourced accounting team can help standardize bookkeeping, reconciliations, reporting and financial processes across locations.

For example, an external professional team can support:

  • Monthly bookkeeping
  • Bank and credit-card reconciliation
  • Accounts receivable and payable
  • Financial statement preparation
  • Management reporting
  • Budgeting
  • Cash-flow forecasting
  • Tax coordination
  • Intercompany accounting support
  • Financial analysis

At Veritas Accounting Services, we support businesses and professional firms with bookkeeping, accounting, tax support, financial reporting and outsourced finance services.

The objective is not simply to keep financial records organized.

It is to provide management with timely, accurate and useful financial information.

For an international business, this can make a meaningful difference.

When financial processes are standardized and reporting is timely, business owners can spend less time trying to understand what happened and more time deciding what should happen next.

That is particularly valuable when the organization is entering new markets, adding employees or managing multiple entities.

A Practical Framework for International Expansion

Before entering a new country, business owners can work through seven practical questions.

1. Is the Market Opportunity Strong Enough?

Understand the potential revenue and strategic value before committing significant resources.

2. What Compliance Requirements Apply?

Identify accounting, tax, payroll and regulatory obligations before operations begin.

3. How Will the Financial Structure Work?

Determine which entity will generate revenue, hold contracts, employ people and incur expenses.

4. What Information Does Management Need?

Establish consistent reporting requirements across countries.

5. Who Controls the Cash?

Define bank access, payment approvals and transfer authority.

6. Which Functions Should Be Outsourced?

Identify activities where an external professional team can provide expertise more efficiently than building an internal department immediately.

7. When Will the Structure Be Reviewed?

International operations change as the business grows. Review processes, controls and reporting regularly.

This framework makes global business growth more deliberate and less reactive.

FAQ

What are the biggest challenges of global business growth?

The most common challenges include multiple currencies, different tax systems, international payroll, banking, intercompany transactions, financial reporting, internal controls and communication across countries.

Why does international expansion make accounting more complicated?

Businesses may need to manage multiple currencies, entities, accounting requirements and intercompany transactions while still producing consistent information for management.

How can businesses manage international tax compliance?

Businesses should identify applicable obligations early, maintain accurate records, use a compliance calendar and work with qualified professionals who understand the relevant jurisdictions.

Should businesses outsource accounting when expanding internationally?

Outsourcing can be effective when a company needs specialized bookkeeping, accounting, reporting or tax support without the cost of establishing a complete internal finance function in every country.

How can management maintain financial visibility across countries?

Standardized bookkeeping, consistent reporting formats, consolidated financial statements, regular reconciliations and clear performance indicators can significantly improve visibility.

Conclusion

International expansion creates opportunities, but it also changes the infrastructure a business needs.

More countries can mean more currencies, employees, banking relationships, tax obligations, transactions and financial information.

The goal is not to eliminate that complexity.

The goal is to build systems capable of managing it without losing control.

Strong bookkeeping, reliable accounting, timely financial reporting, appropriate tax support, effective internal controls and disciplined cash management provide the foundation.

Business owners should also avoid assuming that every capability must be built internally.

Experienced outsourced professionals can provide specialized accounting, bookkeeping, tax and financial support while the internal team focuses on customers, products, strategy and growth.

For businesses pursuing global business growth, the important question is not simply:

“How quickly can we expand?”

It is:

“Can our financial and operational infrastructure support that expansion responsibly?”

At Veritas Accounting Services, we help businesses and professional firms manage bookkeeping, accounting, tax support, financial reporting, forecasting and outsourced finance requirements.

The right financial partner can help an expanding business turn cross-border complexity into better visibility, stronger controls and more confident decisions.

GET IN TOUCH

Schedule a FREE Call
What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Your Simple Guide to Unpaid Invoice Mistakes and Better Records

An unpaid customer invoice is not automatically a tax deduction. Review the tax accounting method…
Leadership

The Difference Between Leadership and Management: Why Businesses Need Both

A business can have talented employees, strong products and healthy revenue—and still struggle to grow.

One common reason is the gap between leadership and management.

The two terms are often used interchangeably, but they represent different responsibilities. Leadership is largely about direction, purpose and people. Management is about execution, systems, resources and accountability.

A growing business needs both.

A company with strong leadership but weak management may have an inspiring vision but struggle with deadlines, processes and consistency. A company with strong management but weak leadership may run efficiently but lack innovation, direction or the ability to adapt.

The challenge for business owners is learning when to lead, when to manage, and when to build systems that allow others to take responsibility.

Table of Contents

  1. What Is Leadership?
  2. What Is Management?
  3. Leadership vs. Management: The Core Difference
  4. Why Businesses Need Both
  5. Leadership Creates Direction
  6. Management Turns Plans Into Results
  7. Where Business Owners Often Struggle
  8. Delegation: The Bridge Between Leadership and Management
  9. Financial Information Supports Better Management
  10. How Outsourced Professionals Can Support Leaders
  11. Building a Business That Does Not Depend on One Person
  12. Practical Questions for Business Owners
  13. FAQ
  14. Conclusion

What Is Leadership?

Leadership is about influencing people toward a shared objective.

A leader answers questions such as:

  • Where are we going?
  • Why does the business exist?
  • What do we want to achieve?
  • What values should guide our decisions?
  • What kind of organization are we building?

Leadership requires communication, judgment and the ability to make decisions when the future is uncertain.

For a founder, leadership might mean deciding which market to enter, which customers to serve, what type of culture to build, or when the business needs to change direction.

Leadership is not necessarily connected to a job title.

A department head, project leader or experienced employee can demonstrate leadership even without being the business owner.

What Is Management?

Management focuses on turning objectives into organized action.

Managers are responsible for areas such as:

  • Planning
  • Budgeting
  • Scheduling
  • Resource allocation
  • Performance monitoring
  • Process management
  • Delegation
  • Accountability
  • Problem resolution

If leadership determines where the organization should go, management helps determine how it will get there.

Consider a company that wants to expand into a new market.

Leadership may establish the objective and communicate why the expansion matters.

Management must then coordinate budgets, employees, timelines, technology, marketing, operations and reporting to make the plan achievable.

Neither function is sufficient on its own.

Leadership vs. Management: The Core Difference

The difference becomes clearer when we compare their primary focus.

LeadershipManagement
Creates directionOrganizes execution
Builds a visionBuilds processes
Inspires peopleCoordinates people
Encourages changeCreates consistency
Focuses on the futureFocuses on current performance
Makes strategic choicesImplements plans
Builds commitmentCreates accountability

These are not competing responsibilities.

They are complementary.

A strong business leader should understand management, and an effective manager should understand the broader direction of the organization.

The most successful companies create an environment where vision and execution reinforce each other.

Why Businesses Need Both

A business needs leadership to determine its destination and management to make the journey sustainable.

Imagine a company with an ambitious five-year growth target.

Leadership might establish the target, define the strategic priorities and communicate the vision to the team.

Management then needs to answer practical questions:

  • How much investment is required?
  • How many employees are needed?
  • What processes need to change?
  • Which performance indicators should be monitored?
  • What is the monthly budget?
  • How will customer service capacity increase?
  • What risks need to be controlled?

Without leadership, the organization may lack direction.

Without management, the strategy may never become reality.

This is why leadership and management should be developed together rather than treated as completely separate disciplines.

Leadership Creates Direction

One of the most important responsibilities of a business leader is deciding what not to pursue.

Growing companies constantly encounter new opportunities.

A new customer may request a different service. An employee may suggest a new product. A competitor may enter a new market.

Leadership requires evaluating these opportunities against the company’s long-term strategy.

For example, a professional services firm may receive an opportunity to offer ten different services.

The leadership question is not simply:

“Can we do this?”

It is:

“Should this be part of our strategic direction?”

Good leaders create focus.

They communicate priorities clearly so that employees understand what deserves attention and what does not.

Management Turns Plans Into Results

Once direction has been established, management becomes critical.

A strategy is only valuable when it can be executed.

Suppose management has decided to improve profitability by 10%.

That objective needs to become measurable actions.

The management team may need to:

  1. Analyze current margins.
  2. Identify high-cost areas.
  3. Review pricing.
  4. Monitor employee productivity.
  5. Reduce unnecessary expenses.
  6. Improve billing and collections.
  7. Establish monthly performance targets.

This is where effective management creates structure.

Without processes and accountability, even a strong strategy can remain an attractive presentation rather than a measurable business outcome.

Where Business Owners Often Struggle

Many founders begin as both the leader and the manager.

They sell to customers, approve payments, supervise employees, review bookkeeping, solve operational problems and make strategic decisions.

That may work in the early stages.

The problem arises when the business grows but the owner’s role does not change.

A founder who continues to personally approve every small decision can become the organization’s biggest bottleneck.

This is often a sign that management systems have not evolved with the business.

Business owners should gradually move away from being the person who solves every problem and toward becoming the person who builds the people, processes and systems that solve problems consistently.

That transition is an important part of leadership development.

Delegation: The Bridge Between Leadership and Management

Delegation is not simply assigning tasks to employees.

Effective delegation involves transferring responsibility and authority while maintaining appropriate accountability.

A business owner should be clear about:

  • What needs to be completed
  • Who owns the responsibility
  • What standard is expected
  • When it must be completed
  • How performance will be measured
  • When the issue should be escalated

Poor delegation sounds like:

“Please take care of this.”

Effective delegation sounds more like:

“You own this process. Here is the expected outcome, deadline and reporting requirement. Let me know if an issue exceeds these defined limits.”

This allows the owner to spend more time on strategic decisions while managers and employees handle operational responsibilities.

Financial Information Supports Better Management

Leadership decisions become stronger when they are supported by reliable financial information.

Revenue alone does not tell a business owner whether the company is performing well.

Management should understand:

  • Gross margins
  • Operating expenses
  • Cash flow
  • Accounts receivable
  • Accounts payable
  • Customer profitability
  • Budget versus actual results
  • Revenue trends
  • Key performance indicators

For example, a business may report strong sales growth while cash flow deteriorates because customers are taking longer to pay.

Leadership needs to decide how the company should respond.

Management needs reliable reporting to identify the problem, monitor collections and measure whether corrective action is working.

This is one reason accounting should not be viewed only as a compliance function.

Accurate financial reporting provides information that supports better management decisions.

How Outsourced Professionals Can Support Leaders

As businesses grow, owners often discover that they need more expertise than they can build internally.

That does not necessarily mean hiring a full-time specialist for every function.

Outsourcing can provide access to experienced professionals in areas such as:

  • Bookkeeping
  • Accounting
  • Tax support
  • Financial reporting
  • Budgeting
  • Cash-flow forecasting
  • Payroll
  • CFO advisory

An external accounting team can take responsibility for recurring financial processes while giving management timely information for decision-making.

For example, instead of spending hours reviewing transactions, a business owner can receive organized monthly financial reports and focus on questions such as:

Why did gross margin change?

Which customers are most profitable?

Can we afford the next hire?

What will our cash position look like three months from now?

This is where professional accounting support can contribute to both management and leadership.

At Veritas Accounting Services, we support businesses and professional firms with bookkeeping, accounting, tax support, financial reporting, budgeting, forecasting and CFO-related services.

The objective is not simply to maintain records.

It is to help businesses maintain reliable financial information so owners and managers can spend more time making informed decisions.

Building a Business That Does Not Depend on One Person

A strong business should not stop functioning when its founder takes a week off.

If every customer relationship, approval, financial decision and operational process depends on one person, the business has a scalability problem.

Leaders should gradually build:

Clear Roles → Documented Processes → Delegated Authority → Reliable Reporting → Accountability

This creates organizational independence.

For example, instead of the owner personally reviewing every supplier invoice, the business can establish an approval process with defined limits.

Instead of the owner preparing every management report, the accounting team can produce standardized reports each month.

Instead of employees asking the founder about every operational issue, documented procedures can provide clear guidance.

These systems allow the leader to focus on growth while management keeps the organization running effectively.

Practical Questions for Business Owners

If you are evaluating your own organization, ask these questions:

1. Am I spending enough time on strategy?

If most of your week is consumed by operational tasks, your business may need better delegation or management systems.

2. Are responsibilities clearly assigned?

Every important recurring process should have an identifiable owner.

3. Do managers have enough authority?

Responsibility without authority creates frustration and slows decision-making.

4. Do I receive financial information on time?

Late or unreliable reports make both management and leadership decisions harder.

5. Can the business operate without me?

If the answer is no, identify the processes that depend on you and begin documenting and delegating them.

6. Are we measuring outcomes?

Employees should understand how their work contributes to business objectives.

7. Where do we need external expertise?

Some functions can be handled internally, while others may be more efficiently supported by specialized external professionals.

These questions can reveal whether the organization has a leadership problem, a management problem, or simply a systems problem.

FAQ

What is the main difference between leadership and management?

Leadership focuses primarily on direction, vision, people and strategic change, while management focuses on planning, execution, processes, resources and accountability.

Can someone be both a leader and a manager?

Yes. In many businesses, particularly smaller companies, the same person performs both roles. As organizations grow, these responsibilities may become distributed across different people.

Why do growing businesses need both leadership and management?

Leadership provides direction and purpose, while management creates the structure needed to execute the strategy consistently.

How does accounting support leadership and management?

Reliable accounting provides financial information about profitability, cash flow, expenses, margins and performance, helping leaders and managers make informed decisions.

Can outsourcing help improve management?

Yes. Outsourcing specialized functions such as bookkeeping, accounting and tax support can give businesses access to expertise while allowing internal managers to focus on core operations.

Conclusion

Leadership and management are not opposing approaches.

They are two sides of building a sustainable business.

Leadership establishes direction, creates purpose and helps people understand where the organization is going.

Management turns that direction into processes, responsibilities, budgets, measurements and results.

As a business grows, the owner’s role must evolve as well. Doing everything personally may help a company get started, but building systems, developing people and delegating responsibility are essential for sustainable growth.

Financial information plays an important role in that transition. Reliable bookkeeping, accounting and reporting allow owners to understand what is happening inside the business rather than relying solely on intuition.

At Veritas Accounting Services, we work with businesses and professional firms to provide bookkeeping, accounting, tax support and financial advisory services that help management operate with better information.

The goal is not simply to keep the numbers organized.

It is to give business leaders the information, structure and support they need to lead with confidence and manage with clarity.

GET IN TOUCH

Schedule a FREE Call
What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Your Simple Guide to Unpaid Invoice Mistakes and Better Records

An unpaid customer invoice is not automatically a tax deduction. Review the tax accounting method…