OBBBA tax rules have reshaped several areas of federal taxation, and as 2025 draws to a close, even hypothetical clients deserve a fresh look. Santa Claus has long been a seasonal favorite for tax professionals exploring complex classification issues, but the introduction of the One Big Beautiful Bill Act adds new relevance to his case.
If Santa were a real client today, OBBBA tax rules would force practitioners to reassess how his activities are categorized, what deductions remain available, and how modern compliance standards apply to unconventional operations.
Is Santa Performing a Service Under OBBBA Tax Rules?
Santa operates a global system that tracks behavior, records outcomes, and determines benefits. From a tax standpoint, that activity begins to resemble a service model. While Santa does not invoice families, tax law focuses less on intent and more on structure and consideration.
Under OBBBA tax rules, the classification of services becomes even more important because new deductions and compliance thresholds hinge on how labor is defined. Santa himself may not receive wages, tips, or overtime, but his workforce certainly does.
The elves’ extended hours during peak production bring OBBBA’s overtime-related deductions into focus. Even in a fictional setting, OBBBA tax rules highlight how compensation structures affect deductions at the entity level.
Are Santa’s Deliveries “Gifts” for Tax Purposes?
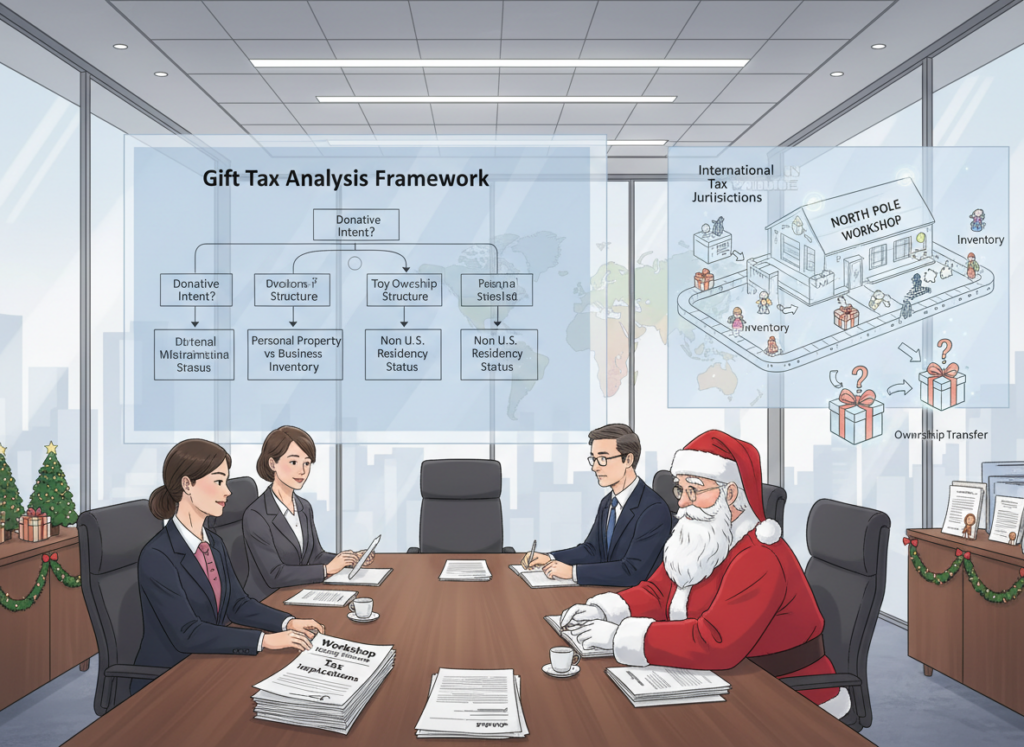
Gift tax analysis always begins with donative intent, and Santa’s intent appears clear. However, tax professionals must ask deeper questions that OBBBA tax rules do not override but make more visible:
Who owns the toys before delivery?
Are the toys personal property or business inventory?
Does the workshop function as a producing entity?
If the workshop owns the toys, Santa may not be the donor at all. Additionally, Santa’s non-U.S. residency status likely removes him from federal gift tax exposure entirely. Still, OBBBA tax rules reinforce the importance of identifying ownership and residency before assuming tax treatment.
Business or Hobby: Why OBBBA Tax Rules Raise the Stakes
One of the most critical questions under OBBBA tax rules is whether Santa’s workshop operates as a business or a hobby. The distinction matters far more after 2025.
Tax professionals would evaluate:
Profit motive
Recordkeeping practices
Reliance on royalties and licensing income
If the workshop is a business, expenses reduce taxable income directly. If it is a hobby, the outcome is dramatically different.
Under OBBBA tax rules, the suspension of miscellaneous itemized deductions becomes permanent. This means hobby expenses are largely nondeductible going forward. Combined with a larger standard deduction, Santa would gain no tax benefit from hobby-related expenses.
This is exactly why OBBBA tax rules make entity and activity classification more important than ever.
Royalties, Licensing, and Passive Income Considerations
Santa’s image generates significant licensing income through films, merchandise, and branding. These royalties would typically be reported as passive income. However, OBBBA tax rules indirectly affect how these income streams interact with deductions and loss limitations.
If Santa’s workshop is treated as a business, certain expenses could offset active income. If not, royalties may remain taxable without corresponding deductions, reinforcing the importance of proactive planning under OBBBA tax rules.
Does the Sleigh Qualify Under New Deduction Rules?
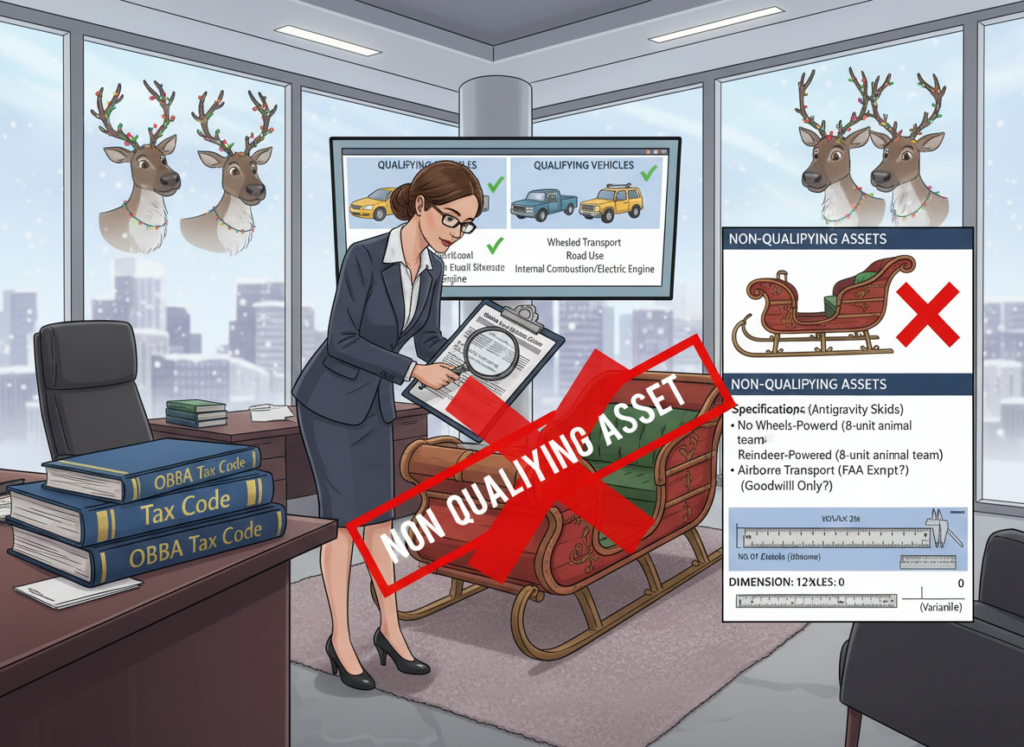
OBBBA introduced a personal auto loan interest deduction, prompting questions about asset eligibility. Santa’s sleigh, while iconic, does not meet statutory definitions of a qualifying vehicle.
While the answer is clearly no, the example is instructive. OBBBA tax rules demonstrate how narrowly drafted deductions require precise asset classification. Practitioners must evaluate eligibility carefully rather than relying on assumptions.
Santa’s Digital Operations and Cross-Border Issues
Santa’s operation now includes real-time tracking, online engagement, and digital visibility across borders. While not all of this generates income, expanding commercialization could create sourcing and nexus considerations.
Under OBBBA tax rules, digital income streams and licensing arrangements require careful review, particularly when U.S.-source income is involved. Even hypothetical clients illustrate how global operations intersect with modern tax compliance.
Residency and Where Santa Pays Tax
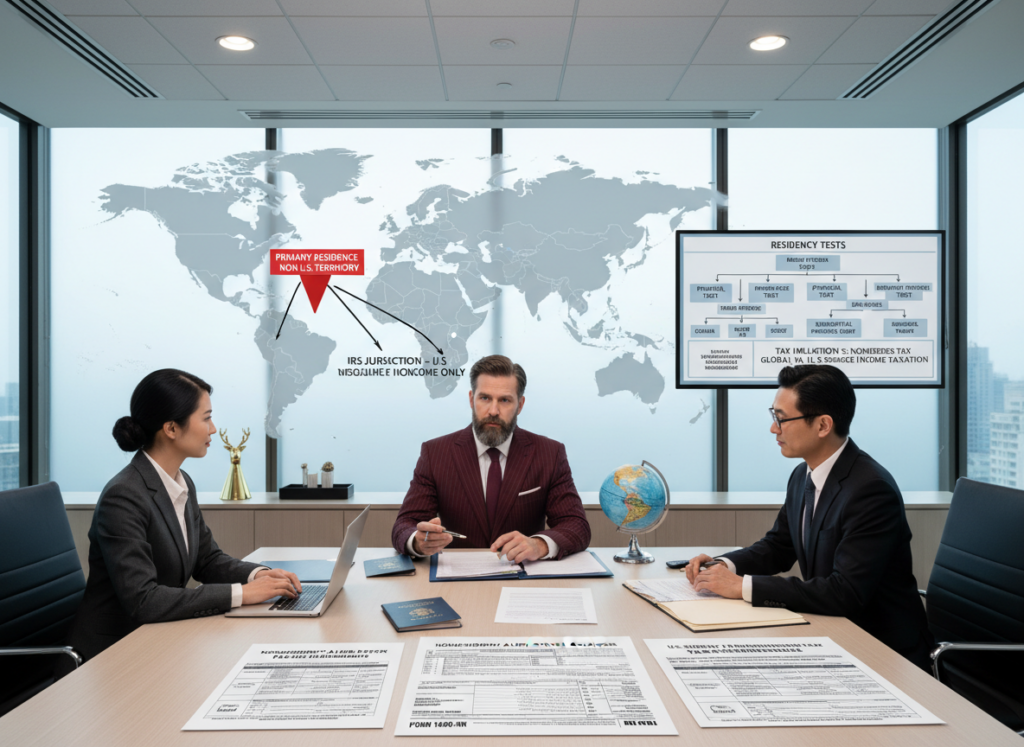
Residency remains the starting point for all tax analysis. Santa’s North Pole residence suggests nonresident alien status. As a result, only U.S.-source income would fall under IRS jurisdiction.
While OBBBA tax rules do not change residency tests, they do influence how deductions, withholding, and reporting apply to nonresident taxpayers. Santa’s situation underscores the continued importance of jurisdictional analysis.
What Tax Professionals Can Learn from Santa’s 2025 Puzzle
Santa’s hypothetical return demonstrates how OBBBA tax rules affect real-world decision-making. Classification, intent, structure, and timing now carry greater consequences than before.
Seasonal examples like this are more than entertainment. They sharpen analytical skills, reinforce compliance fundamentals, and help practitioners stay alert to emerging changes.
Final Takeaway
Santa’s 2025 tax puzzle reminds us that tax law complexity doesn’t disappear just because the facts are unconventional. With OBBBA tax rules reshaping deductions, classifications, and planning strategies, tax professionals must approach every client—real or imagined—with renewed precision.
Understanding how these rules apply today ensures better outcomes tomorrow, long after the sleigh has left the rooftop.
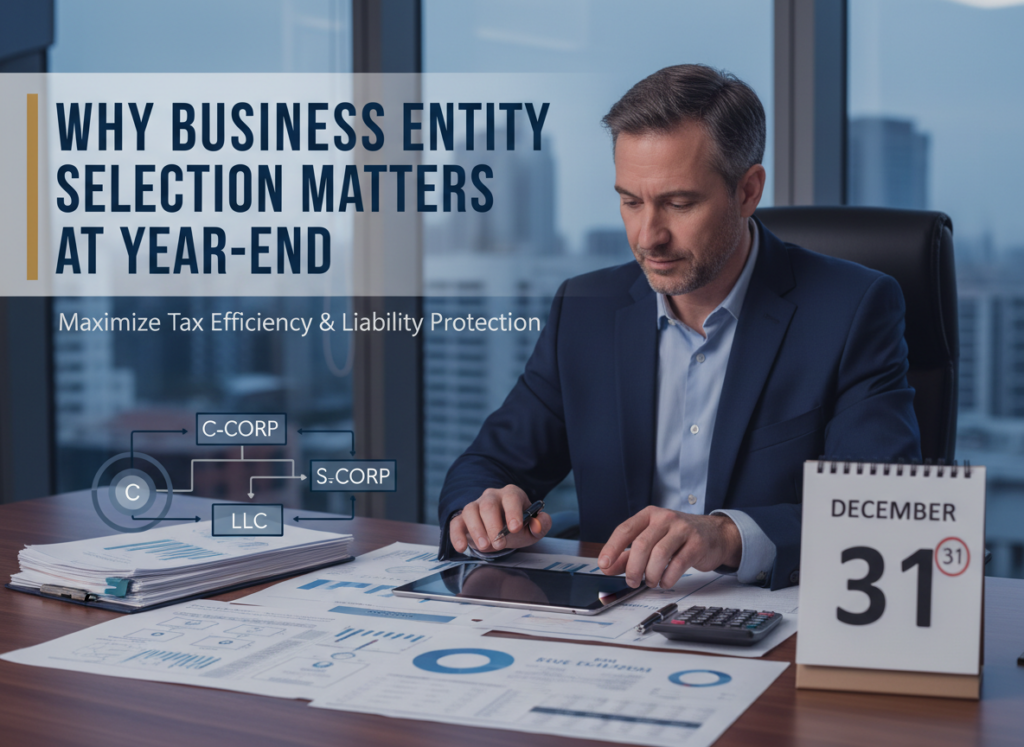
Business entity selection is one of the most impactful decisions a business owner can make, yet it is often left untouched for years. As 2025 draws to a close and the tax landscape prepares for meaningful changes in 2026, year-end planning offers a critical opportunity to reassess whether a company’s current structure still supports its financial, tax, and long-term goals.
Entity selection affects far more than tax rates. It shapes how income is taxed, how losses are used, how compensation is structured, and how a business prepares for growth, retirement, or succession. A thoughtful review before year-end allows tax professionals and business owners to align structure with strategy—before deadlines pass and options narrow.
Why Business Entity Selection Matters at Year-End
Year-end is when income levels become clear, ownership changes are finalized, and planning for the coming year begins. This timing makes business entity selection especially important. Decisions made now can influence tax outcomes not only for the current year but well into 2026 and beyond.
Expected rate adjustments, evolving compliance requirements, and shifting business goals mean that a structure that worked in prior years may no longer be optimal. Reviewing entity choice at year-end allows advisors to identify whether staying the course makes sense or whether restructuring could deliver meaningful tax or operational benefits.
Understanding Business Entity Selection Across Common Structures
Effective business entity selection requires understanding how each entity type operates under current law and how it may be affected by upcoming changes.
C Corporations
C corporations offer a flat corporate tax rate and a familiar legal framework. They are often well-suited for businesses that plan to reinvest profits, pursue outside investors, or prepare for equity-based growth. However, double taxation remains a central consideration. Profits taxed at the corporate level may be taxed again when distributed to shareholders, which can reduce overall tax efficiency for owners seeking regular distributions.
S Corporations
S corporations provide pass-through taxation while allowing flexibility in managing compensation and distributions. For many closely held businesses, this balance can be attractive. That said, eligibility rules—such as limits on shareholders, ownership restrictions, and the single-class-of-stock requirement—must be reviewed regularly. Reasonable compensation remains a key compliance issue and should be part of any year-end evaluation.
Partnerships and Multi-Member LLCs
Partnerships and multi-member LLCs offer the greatest flexibility in business entity selection. Special allocations, tiered ownership, and customized economic arrangements make them ideal for complex or evolving businesses. However, this flexibility comes with added administrative responsibility, including basis tracking, capital account maintenance, and careful handling of self-employment tax exposure.
How Business Entity Selection Impacts Tax Outcomes
Choosing the right entity structure affects how income and losses flow to owners. As income increases or business activity shifts, the tax efficiency of one entity compared to another can change significantly.
Year-end planning allows professionals to model how 2026 tax rules may affect pass-through income, corporate earnings, or owner compensation. A structure that minimizes tax under current conditions may become less favorable as thresholds, rates, or limitations change.
Year-End Planning Tools That Affect Business Entity Selection
Several planning tools can influence business entity selection, but many come with strict timing requirements. Late S elections, check-the-box classifications, or restructuring transactions may be available only if action is taken before year-end or within specific election windows.
Missing these deadlines can delay a desired strategy by an entire year, potentially resulting in higher taxes or lost planning opportunities. Reviewing entity options before year-end ensures that clients do not miss critical elections that could support their 2026 objectives.
Business Entity Selection and Long-Term Planning Goals
Entity choice does not exist in isolation. Business entity selection interacts closely with retirement planning, succession strategies, and compensation design.
A business planning for a future sale or generational transfer may benefit from the flexibility offered by partnership structures. Owners seeking to maximize retirement contributions may find different opportunities depending on whether they operate as an S corporation or C corporation. Evaluating entity choice with a long-term lens helps ensure that today’s structure does not limit tomorrow’s options.
Communicating Business Entity Selection Decisions to Clients
Many business owners find business entity selection confusing, especially when an LLC can be taxed in multiple ways. Clear communication is essential. Explaining how distributions, wages, basis, and compliance obligations differ between entities empowers clients to participate in the decision-making process.
When clients understand the trade-offs involved, they are more likely to feel confident in the chosen structure and committed to long-term planning strategies. Year-end conversations provide a natural opportunity to revisit these topics and reinforce proactive planning.
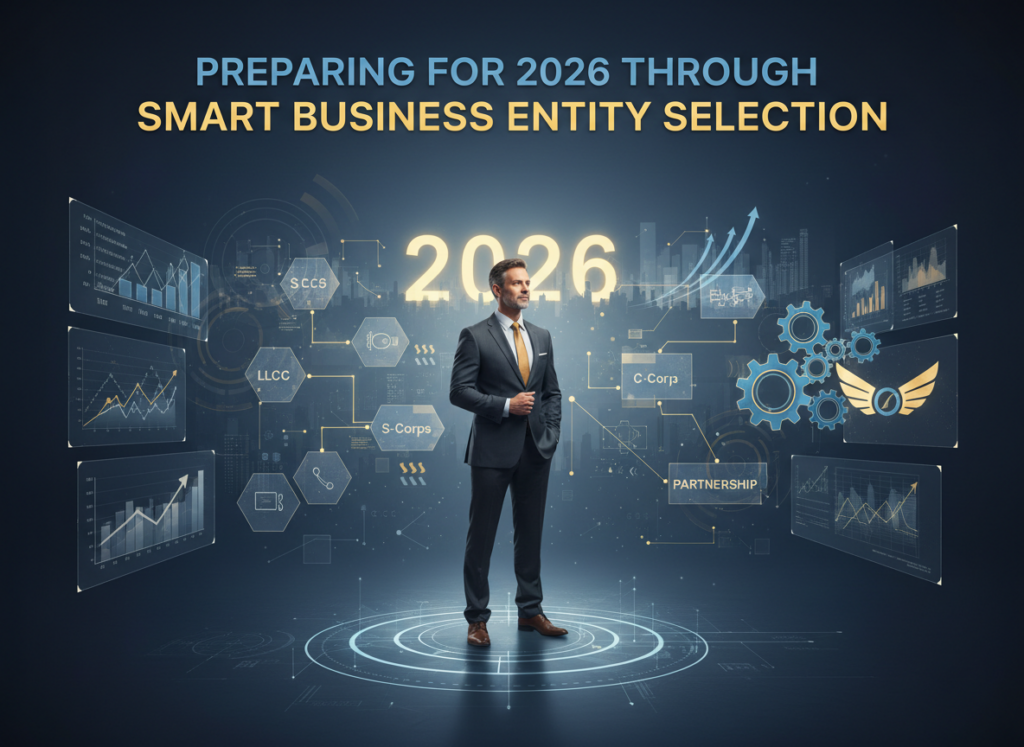
Preparing for 2026 Through Smart Business Entity Selection
As 2026 approaches, tax professionals should encourage clients to view business entity selection as an evolving strategy rather than a one-time decision. Economic conditions change, tax laws evolve, and business goals shift. Regular reviews ensure that entity choice remains aligned with both current operations and future plans.
Proactive evaluation at year-end allows businesses to enter the new tax year with clarity, confidence, and a structure designed to support growth and compliance.
Key Takeaway
Business entity selection is a foundational element of effective tax and business planning. Year-end offers the ideal moment to reassess whether a company’s current structure still supports its goals in light of upcoming 2026 changes.
By reviewing entity choice now—before deadlines pass—business owners and advisors can position the business for tax efficiency, operational flexibility, and long-term success. A well-timed evaluation today can prevent costly adjustments tomorrow and ensure the business is built for what lies ahead to support sustainable growth.
Final Thoughts
Business entity selection is not a decision that should be made once and forgotten. As tax laws evolve and business goals change, the structure that once worked well may no longer deliver the best results. Reviewing entity choice at year-end allows business owners to step into the next tax year with clarity, confidence, and a structure aligned to both current operations and future plans.
Taking time now to reassess entity selection can help avoid missed opportunities, reduce tax inefficiencies, and support long-term growth. A proactive review before year-end ensures that your business enters the new year prepared, compliant, and strategically positioned for what lies ahead.
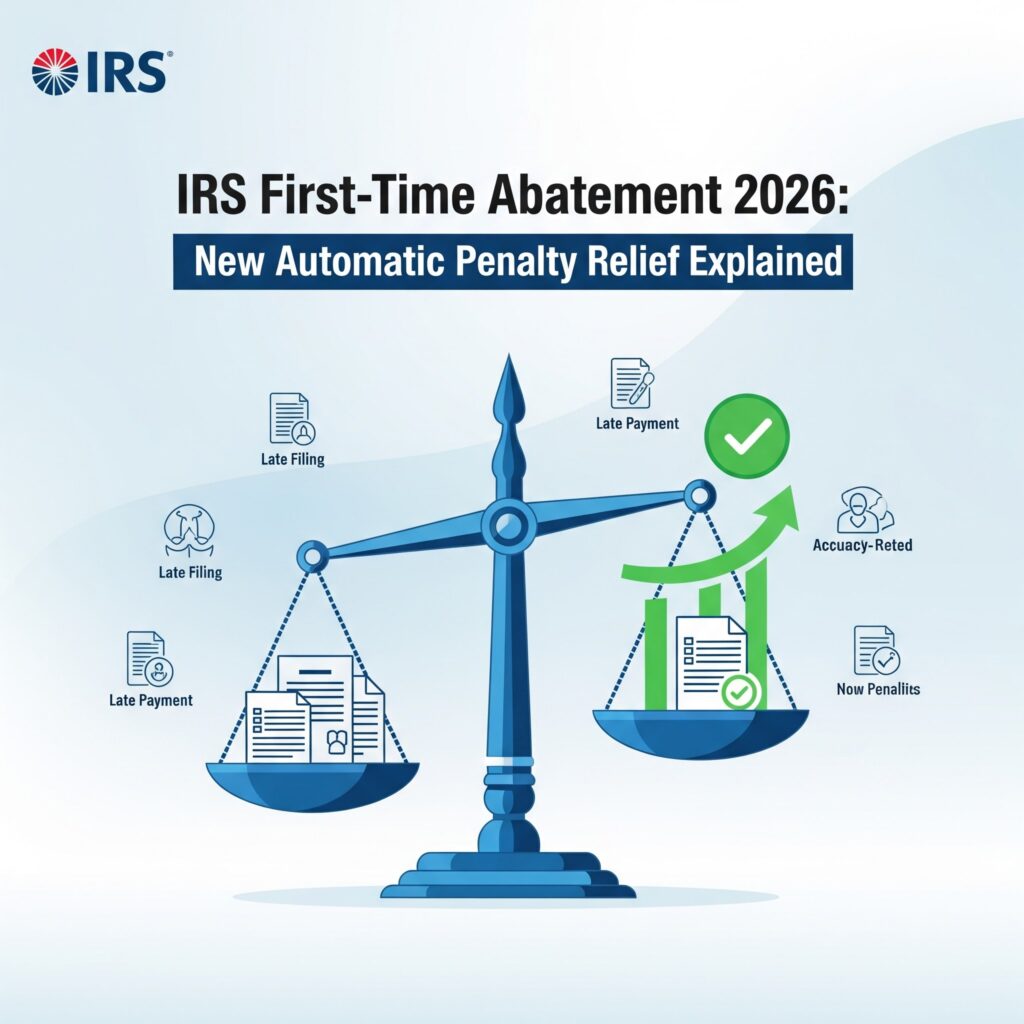
The first-time abatement 2026 update marks a major shift in how the IRS administers penalty relief for taxpayers. For years, taxpayers struggled with penalty notices—many not knowing that the IRS offered a First-Time Abatement (FTA) program at all. The IRS required taxpayers or tax professionals to call, write, or file a request to receive the penalty waiver.
Starting in 2026, the IRS will automatically apply first-time abatement 2026 relief when a taxpayer qualifies. This is one of the most significant modernization steps in recent IRS history.
This blog breaks down what first-time abatement 2026 means, who qualifies, how the automatic waiver works, and what tax professionals must do to prepare.
⭐ What Is First-Time Abatement (FTA)?
First-Time Abatement (FTA) has existed since 2001 and is one of the most widely applicable forms of IRS penalty relief. FTA is available for taxpayers who have a good compliance history and need relief from certain penalties.
Under first-time abatement 2026, the IRS will shift from a request-based model to an automatic system—helping millions of taxpayers who previously missed out due to lack of awareness.
FTA applies only to penalties related to:
Failure to file
Failure to pay
Failure to deposit (for payroll taxes)
These penalties can be substantial, and first-time abatement 2026 may prevent financially strained taxpayers from paying unnecessary penalties.
📌 Penalties Eligible Under First-Time Abatement 2026
FTA continues to apply to only three penalty categories. Under the first-time abatement 2026 system, these penalties will be reviewed automatically:
✔ Failure to File Penalty
Assessed when a taxpayer submits a return after the due date.
✔ Failure to Pay Penalty
Applied when taxes remain unpaid by the deadline.
✔ Failure to Deposit Penalty
Relevant to employers who do not deposit payroll taxes on time.
Under first-time abatement 2026, these penalties may no longer require taxpayers to call the IRS or file Form 843 to request relief.
❌ Penalties NOT eligible for FTA include:
Accuracy penalties
Estimated tax penalties
Information return penalties (W-2, 1099, 3520, 5471, etc.)
Event-based returns (estate tax, gift tax)
🧾 Who Qualifies for First-Time Abatement 2026?
To qualify for first-time abatement 2026, taxpayers must meet existing FTA rules. These requirements remain unchanged.
🔹 1. Eligible Return Types
FTA applies only to:
Individual: Form 1040 series
Business: Form 1120, Form 1065
Payroll: Form 940, 941, 944, 945
Not eligible under first-time abatement 2026: Form 990 series, gift tax returns, estate tax returns, international forms.
🔹 2. Clean Compliance History
Taxpayer must have:
No disqualifying penalties in the three years prior to the penalty year
Estimated tax penalties do NOT disqualify
For joint returns: BOTH spouses must meet the criteria
For payroll taxes: must not have more than three prior Failure to Deposit waivers
Even under first-time abatement 2026, the IRS will evaluate compliance history before applying automatic relief.
🔹 3. Filing Compliance
All required tax returns for the previous three years must be filed.
This rule is unchanged under the first-time abatement 2026 automatic system.
🔹 4. Good Standing on Balances
Taxpayers must be current with IRS agreements or payment plans.
Automatic FTA in first-time abatement 2026 will be blocked if a taxpayer is not in good standing.
🚀 What’s Changing in 2026?
Currently, taxpayers must manually request FTA by:
Calling the IRS
Writing a letter
Filing Form 843
Beginning in first-time abatement 2026, the IRS will automatically issue the waiver when all criteria are met.
This modernization comes after years of recommendations from:
Treasury Inspector General for Tax Administration (TIGTA)
National Taxpayer Advocate (NTA)
Industry tax associations
In November 2025, Erin Collins (NTA) confirmed that the IRS will be implementing the automatic first-time abatement 2026 capability.
🌟 Benefits of Automatic FTA:
Taxpayers no longer miss out due to lack of awareness
Reduced IRS call volume
Faster processing
Fairer and more consistent application of penalty relief
🧠 Why First-Time Abatement 2026 Matters
Millions of taxpayers qualify for FTA every year, but only a small percentage receive the waiver. Reasons include:
Not knowing the program existed
Difficulty contacting the IRS
Confusion about eligibility
Filing delays that complicate penalty removal
With first-time abatement 2026, the IRS aims to eliminate these barriers.
This change especially benefits:
First-time filers
Taxpayers facing temporary financial hardship
Small businesses with payroll deposit issues
Tax professionals who handle high call volumes during tax season
🛠️ Action Steps for Tax Professionals
Even though first-time abatement 2026 becomes automatic, tax professionals must remain vigilant.
🔍 1. Review Client Accounts for Missed Past FTA Opportunities
Clients may still qualify for relief for earlier years (before 2026). Tax pros can:
Obtain Form 2848
Call the IRS Practitioner Priority Service
File Form 843 when appropriate
📅 2. Watch for IRS Implementation Guidance
Key details will be published as the IRS finalizes:
System automation rules
Exception-handling processes
How to address cases where automatic FTA is not applied
Employer deposit penalty workflows
📝 3. Ensure Clients Maintain Filing Compliance
Missing returns automatically disqualify taxpayers from first-time abatement 2026.
Encourage clients to catch up before penalties hit.
The IRS provided administrative penalty waivers for:
2019–2020 late filing
2020–2021 failure to pay
These do NOT disqualify taxpayers from first-time abatement 2026, but IRS coding inconsistencies may require manual intervention.
🔚 Final Thoughts
The introduction of first-time abatement 2026 represents a major IRS modernization that brings more fairness and access to penalty relief. Millions of taxpayers will benefit from automatic evaluations rather than needing to request relief through complex processes.
Tax professionals should stay informed, monitor IRS publications, and proactively review client accounts to ensure no qualified taxpayer misses out on penalty relief.
📞 Need Help Navigating IRS Penalties or Compliance?
Veritas Accounting Services is here to support you.
As the year draws to a close, year-end tax planning should be at the top of every taxpayer’s financial checklist. Preparing early gives you the power to reduce what you owe, avoid unnecessary penalties, and maximize tax-saving opportunities that disappear once the calendar resets on January 1. Whether you are an employee, business owner, investor, or self-employed professional, the steps you take now can make tax season smoother, cheaper, and far less stressful.
Below are seven powerful and practical year-end tax planning tips that every taxpayer should act on before December 31.
1. Get Organized Early
Good year-end tax planning starts with good organization. Gather all essential financial documents in one place to avoid scrambling at the last minute. This includes:
Pay stubs and W-2 forms
1099 forms for contractors or side gigs
Receipts for deductible expenses
Bank and credit card statements
Investment statements
Business income and expense records
Charitable donation receipts
Medical expense records
Use digital folders, cloud storage, or an envelope system—whatever helps you keep everything accessible and secure. Tracking deductible expenses throughout the year such as mortgage interest, student loan interest, or medical bills will make filing much easier if you plan to itemize deductions.
2. Review Your Withholding and Estimated Payments
A quick review of your withholding could save you from an unwanted shock in April. Life changes—marriage, divorce, a new baby, a second job, or higher pay—can significantly affect your tax liability.
Before year-end:
✔ Check your most recent pay stub ✔ Use the IRS withholding calculator ✔ Adjust form W-4 if needed ✔ Review your quarterly estimated taxes if you’re self-employed
Correcting underpayments now helps you avoid penalties. Correcting overpayments helps you avoid giving the government an interest-free loan.
3. Maximize Retirement Contributions
One of the smartest year-end tax planning strategies is contributing to tax-advantaged retirement accounts:
Traditional IRA
Contributions may be tax-deductible depending on income and filing status.
401(k), 403(b), and similar plans
Increasing your pre-tax contributions reduces your taxable income today while boosting long-term savings.
Health Savings Accounts (HSAs)
HSAs offer a triple tax advantage for year-end tax planning:
Contributions are tax deductible
Growth is tax-free
Withdrawals for qualified medical expenses are tax-free
Flexible Spending Accounts (FSAs)
Review your FSA balance—many plans follow a “use-it-or-lose-it” rule. If needed, schedule healthcare visits or buy approved items before year-end.
4. Make Year-End Charitable Contributions
If you plan to itemize your deductions, year-end charitable giving is a powerful way to reduce taxable income.
You can donate:
Cash
Stock or appreciated assets
Clothing or household items
Donor-advised fund contributions
Important:Donations must be made by December 31 to count for the current tax year. Keep receipts, acknowledgment letters, or IRS Form 8283 for non-cash contributions.
Donating appreciated stock provides an added tax benefit: ✔ You avoid paying capital gains tax ✔ You deduct the fair market value of the donated asset
Just make sure the organization is a qualified §501(c)(3) charity.
5. Review Your Investment Portfolio (Tax-Loss Harvesting)
Year-end is the perfect time to evaluate your investment gains and losses.
If you sold assets at a profit, consider selling underperforming assets to offset those gains—this is known as tax-loss harvesting.
Key rules:
Capital losses offset capital gains
Excess losses (up to $3,000) can offset ordinary income
Unused losses carry forward to future years
Avoid violating the IRS “wash-sale rule” (selling and rebuying the same asset within 30 days)
Thoughtful investment adjustments now can improve your overall tax outcome and strengthen your portfolio for the next year and also year-end tax planning.
6. Check Your Eligibility for Valuable Credits and Deductions
Many taxpayers unintentionally leave money on the table by overlooking eligible tax credits and deductions.
Common Tax Credits:
Child Tax Credit
Earned Income Tax Credit
American Opportunity Credit
Lifetime Learning Credit
Common Deduction Opportunities:
Student loan interest (up to $2,500)
Teacher expense deduction (up to $300)
Home office deduction
Business expenses for freelancers
If you’re self-employed, maintain detailed records of:
Mileage
Supplies
Equipment
Software
Continuing education
Home office expenses
These deductions lower taxable income and increase your refund potential.
7. Strategically Manage Income and Expenses
Timing matters when it comes to tax planning.
If you expect lower income next year:
Defer income (bonuses, invoices, freelance payments) to next year
Accelerate deductible expenses into this year
If you expect higher income next year:
Accelerate income into this year
Delay some deductions to next year when they are more valuable
You can also prepay deductible expenses like property taxes, mortgage interest (if eligible), or qualified medical bills for better year-end tax planning.
Prepare for Upcoming Tax Law Changes
Tax laws evolve regularly. Stay updated on changes to:
Standard deductions
Income tax brackets
Retirement contribution limits
Energy-efficient home credits
Child tax credit rules
A short consultation with a tax professional can help you avoid costly mistakes and ensure that you’re maximizing every available tax benefit.
Plan Ahead for the New Year
Effective year-end tax planning doesn’t end on December 31. Set up a system for next year:
✔ Digital document storage ✔ Quarterly financial reviews ✔ Estimated tax reminders ✔ Mileage and expense tracking apps ✔ Organized business records
These small habits build a smoother, more predictable tax season.
Final Thoughts
Year-end tax planning is one of the smartest financial moves you can make. By organizing your documents, adjusting withholding, maximizing contributions, reviewing investments, and planning your income and deductions strategically, you can enter the new year with confidence and peace of mind.
Don’t wait until tax season to get ready—start today and set yourself up for a successful filing season.
📞 Need Expert Tax Planning Help Before the Year Ends?
Let professionals handle the complexity of year-end tax planning so you can focus on your financial goals.
Contact Veritas Accounting Services
📧 Email:hello@veritasaccountingservices.com 📞 Phone: +1 (678) 723-6003 | +91 97255 52243 🏢 US Office: 8735 Dunwoody Place – 4549, Atlanta, GA 🏢 India Office: C-305, The Imperial Heights, 150ft Ring Road, Rajkot
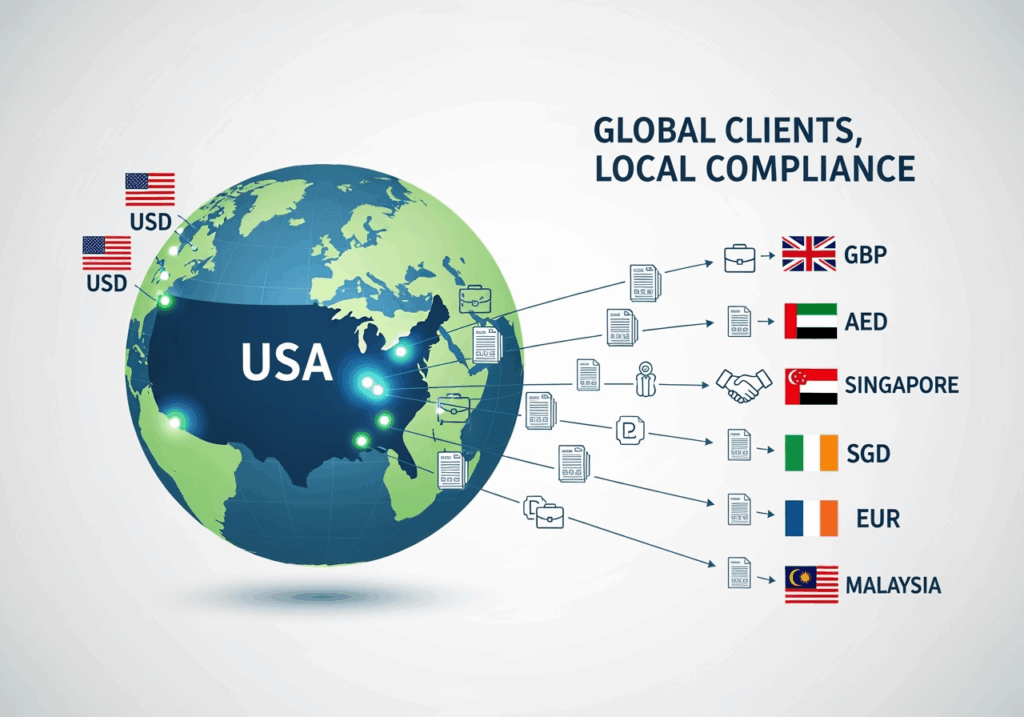
We proudly serve clients across the US, UK, UAE, Singapore, Ireland, and Malaysia, offering expert tax planning, filing, and financial management solutions.
Schedule Your FREE Consultation Today
Start the new year with clarity, confidence, and do your year-end tax planning that truly supports your financial success.
If you’re drowning in credit cards, loans, or medical bills, you’re not alone—but you can Crush Your Debt Faster with a clear plan. The problem for most people isn’t a lack of effort; it’s a lack of strategy. You pay a little here, a little there, and it feels like nothing ever changes.
Two proven methods can turn that around:
The Debt Snowball Method
The Debt Avalanche Method
Both are powerful debt repayment strategies that help you stay focused and make real progress. In this guide, you’ll learn how each method works, who they’re best for, and how to choose the one that helps you Crush Your Debt Faster without burning out.
What Is the Debt Snowball Method?
The Debt Snowball Method is built around small, fast wins. Instead of worrying about interest rates, you focus on paying off your smallest debts first and create momentum.
How the Snowball Method Works
List all your debts from smallest balance to largest.
Pay the minimum on every debt.
Put all extra money toward the smallest debt.
Once that debt is gone, “snowball” its payment into the next smallest debt.
Repeat until every debt is paid off.
Even though this method isn’t always mathematically perfect, it helps you Crush Your Debt Faster because it keeps you emotionally engaged.
Why the Snowball Method Works
You eliminate entire balances quickly.
Each win builds motivation and confidence.
The plan is simple, so you’re less likely to quit.
Best for: people who feel overwhelmed, emotional spenders, and anyone who needs quick proof that their efforts are working.
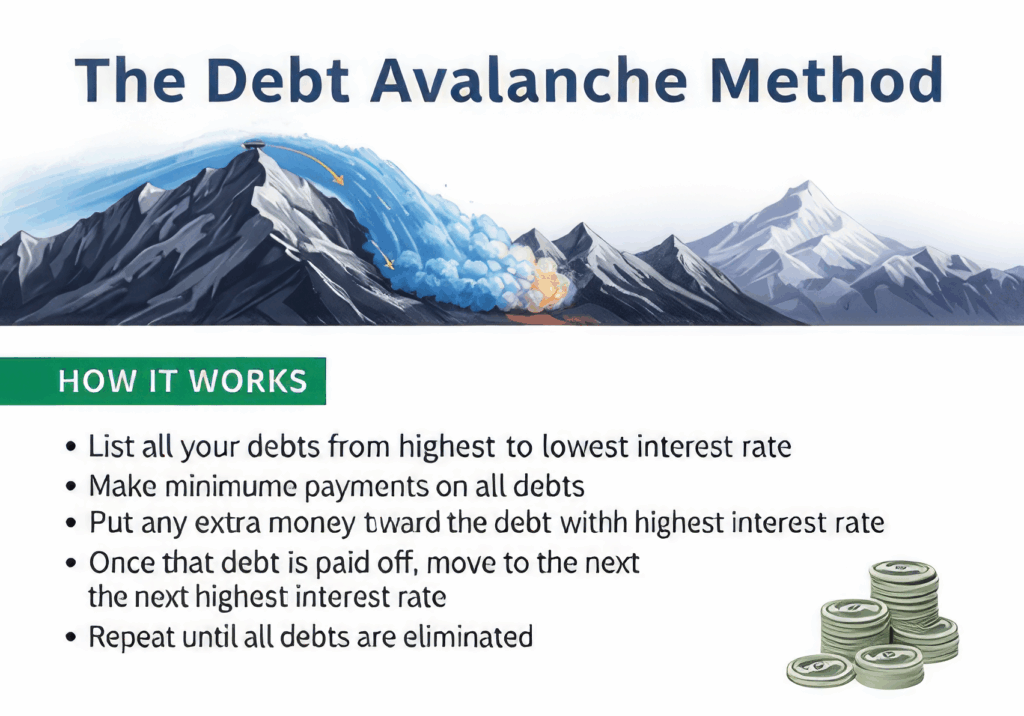
What Is the Debt Avalanche Method?
The Debt Avalanche Method is focused on saving the most money in interest and often paying off everything in less time overall. Instead of looking at balance size, you look at interest rates.
How the Avalanche Method Works
List all your debts from highest interest rate to lowest.
Pay the minimum on all debts.
Put all extra money toward the highest-interest debt.
Once it’s paid off, move to the next highest rate.
Continue until you’re completely debt-free.
This approach helps you Crush Your Debt Faster from a financial perspective, even if early progress is less visible.
Why the Avalanche Method Works
You pay less total interest.
You usually finish your debt-free journey sooner.
It’s especially powerful for high-interest credit cards.
Best for: disciplined people who like numbers, want to minimize interest, and don’t need immediate emotional wins.
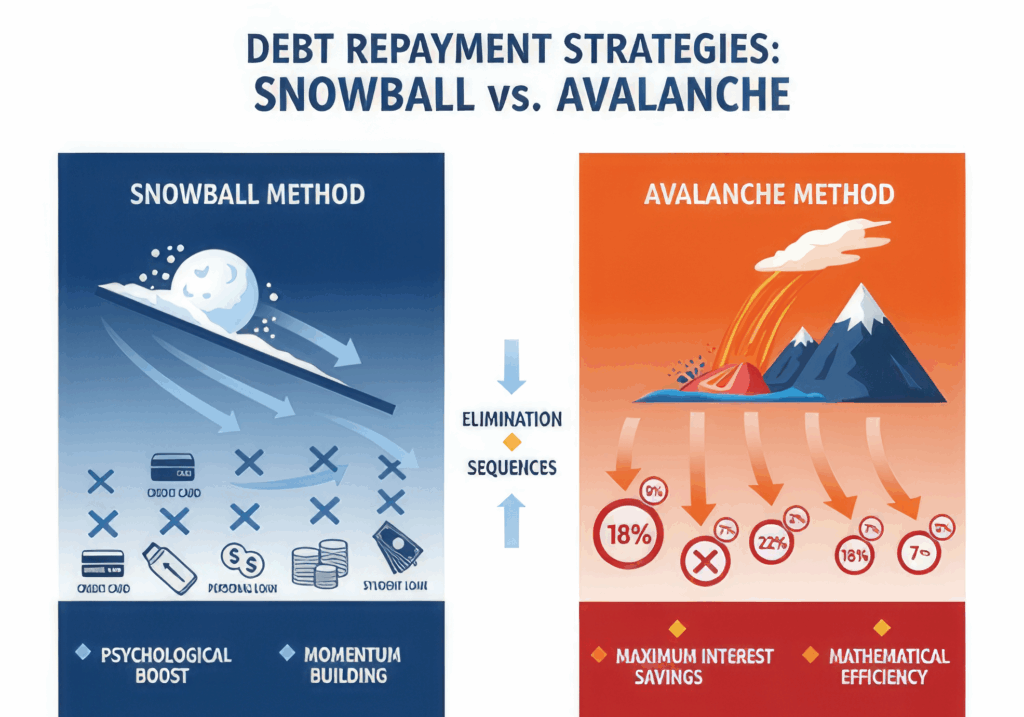
Snowball vs. Avalanche: Key Differences
Use this in a Table block in WordPress:
Feature
Debt Snowball
Debt Avalanche
Main Focus
Smallest balance first
Highest interest rate first
Motivation
Fast emotional wins
Long-term savings
Interest Saved
Less
More
Speed Overall
Sometimes slower
Often faster
Complexity
Very simple
Requires tracking rates
Best For
Motivation & momentum
Efficiency & savings
In simple terms:
Snowball is emotion-first, math-second.
Avalanche is math-first, emotion-second.
To Crush Your Debt Faster, you need the one that aligns with how you think and behave.
Which Strategy Will Help You Crush Your Debt Faster?
The “best” strategy is the one you actually stick with.
Ask yourself:
Do I lose motivation when progress is slow?
Do I care more about paying less interest or feeling progress sooner?
Do I like simple, no-math plans or detailed, optimized ones?
Choose the Snowball Method If…
You’ve started and stopped debt payoff plans before.
You feel better when you see entire accounts hit zero.
You want an easy way to Crush Your Debt Faster through motivation.
Choose the Avalanche Method If…
You’re patient and disciplined.
You want to save the most money on interest.
You’re okay waiting longer for the first “big win.”
There’s no wrong answer. The real mistake is staying stuck and using no system at all.
Can You Combine Both Strategies?
Absolutely. You don’t have to pick one and stay with it forever. A hybrid approach can help you Crush Your Debt Faster while balancing emotion and efficiency.
Start with a mini Snowball: Pay off one or two tiny debts first to create quick momentum.
Switch to Avalanche: Once you feel focused and confident, reorder your remaining debts by interest rate and attack the highest one.
Reset when needed: If you feel stuck again, temporarily use the Snowball on a small balance to regain motivation.
This blended method gives you the emotional wins of Snowball and the interest savings of Avalanche.
Real-Life Example: Which Method Wins?
Meet Sam. Sam has these debts:
Debt Type
Balance
Interest Rate
Credit Card A
$1,500
22%
Credit Card B
$800
18%
Personal Loan
$3,000
10%
Medical Bill
$500
0%
Sam can put $450 per month toward debt.
With the Debt Snowball
Order from smallest balance:
Medical Bill – $500
Credit Card B – $800
Credit Card A – $1,500
Personal Loan – $3,000
Sam wipes out the medical bill in just over one month, then Credit Card B a few months later. These fast wins make Sam feel powerful and in control—and that feeling helps Sam Crush Debt Faster because the plan doesn’t get abandoned.
With the Debt Avalanche
Order by highest interest rate:
Credit Card A – 22%
Credit Card B – 18%
Personal Loan – 10%
Medical Bill – 0%
Sam needs more time before one entire account disappears, but pays much less interest overall and finishes the total payoff sooner than with Snowball.
Takeaway:
Snowball helps Sam stay emotionally committed.
Avalanche helps Sam save more and mathematically Crush Debt Faster.
You choose which “faster” matters more: faster emotionally, or faster financially.
Final Thoughts: Start Crushing Your Debt Today
You don’t need perfect timing, a big income, or a miracle. You just need a plan you’ll actually follow.
Use Debt Snowball if motivation is your biggest challenge.
Use Debt Avalanche if interest savings and efficiency matter most.
Use a hybrid strategy if you want both.
Most importantly, take action. The sooner you start, the sooner you’ll Crush Your Debt Faster and free up your income for saving, investing, and building the life you actually want.
Pick your strategy today and start your debt-free journey.
📞 Ready to Finally Crush Your Debt Faster and Take Control of Your Financial Future?
If you need expert guidance on budgeting, debt repayment planning, or complete financial management, Veritas Accounting Services is here to support you every step of the way.
Contact Veritas Accounting Services:
📧 Email:hello@veritasaccountingservices.com 📞 Phone: +1 (678) 723-6003 | +91 97255 52243 🏢 US Office: 8735 Dunwoody Place – 4549, Atlanta, GA 🏢 India Office: C-305, The Imperial Heights, 150ft Ring Road, Rajkot
We proudly serve clients across the US, UK, UAE, Singapore, Ireland, and Malaysia, offering personalized bookkeeping, debt planning, tax filing, and CFO-level financial
In the complex world of investment planning, one of the most overlooked strategies is maximizing tax-free investment income. While many investors focus solely on returns, the smartest wealth builders understand that it’s not what you earn—it’s what you keep after taxes that truly matters.
What is Tax-Free Investment Income?
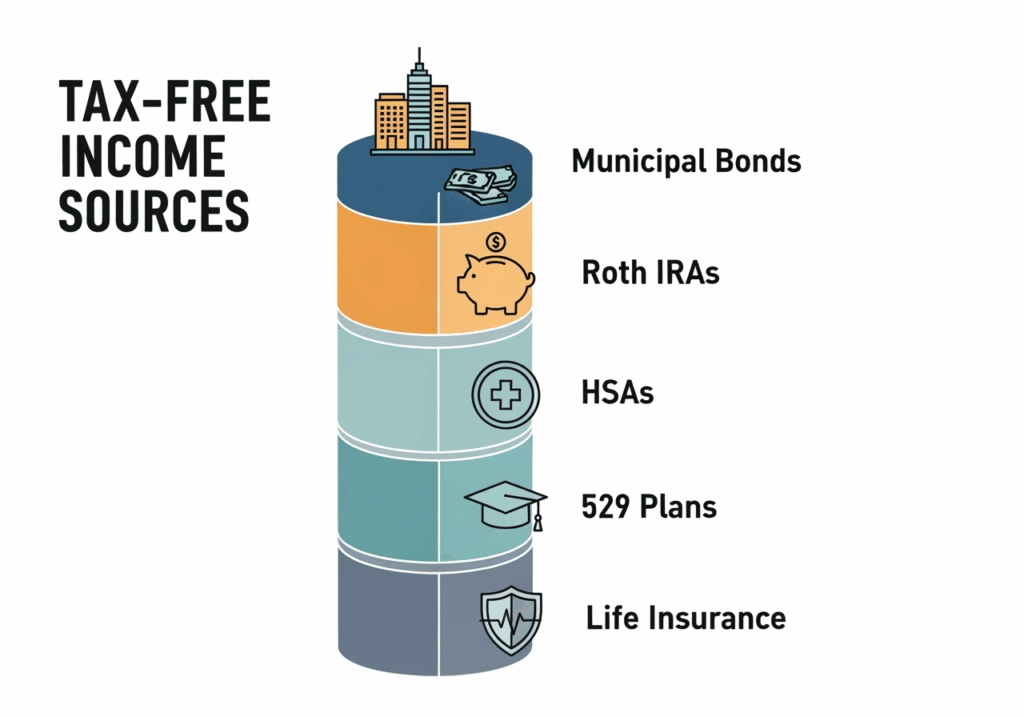
Tax-free investment income refers to earnings from specific investment vehicles that are exempt from federal income taxes, and in some cases, state and local taxes as well. The three primary sources include:
1. Municipal Bonds
Municipal bonds, or “munis,” are debt securities issued by state and local governments to fund public projects. The interest earned from these bonds is typically exempt from federal income tax and may also be exempt from state and local taxes if you live in the issuing state.
Types of Municipal Bonds to Consider:
General Obligation Bonds: Backed by the full faith and credit of the issuing municipality
Revenue Bonds: Secured by specific revenue streams from projects like toll roads or utilities
Private Activity Bonds: May be subject to AMT but offer higher yields
Build America Bonds: Federally subsidized municipal bonds with taxable interest
2. Roth IRAs
Unlike traditional IRAs, Roth IRA contributions are made with after-tax dollars. However, qualified withdrawals in retirement—including both contributions and earnings—are completely tax-free, making them a powerful long-term wealth-building tool.
Advanced Roth Strategies:
Roth Ladder Conversions: Systematic conversions over multiple years to manage tax brackets
Mega Backdoor Roth: For high earners with 401(k) plans allowing after-tax contributions
Roth IRA Inheritance Planning: Tax-free wealth transfer to beneficiaries
3. Life Insurance Payouts
Certain life insurance policies, particularly permanent life insurance with cash value components, can provide tax-free income through policy loans and withdrawals up to your basis in the policy.
Private Placement Life Insurance (PPLI): For ultra-high-net-worth individuals
Corporate-Owned Life Insurance (COLI): Business tax planning applications
Additional Tax-Free Income Sources
Health Savings Accounts (HSAs)
Often called the “triple tax advantage” account, HSAs offer:
Tax-deductible contributions
Tax-free growth
Tax-free withdrawals for qualified medical expenses
After age 65, withdrawals for non-medical purposes are taxed as ordinary income (like a traditional IRA)
529 Education Savings Plans
While contributions aren’t federally deductible, earnings grow tax-free and withdrawals for qualified education expenses are tax-free. Recent expansions allow:
K-12 tuition payments up to $10,000 annually
Student loan repayments up to $10,000 lifetime
Beneficiary changes to family members
Why Tax-Free Investment Income Matters More Than Ever
Protecting Your Overall Tax Picture
Tax-free investment income doesn’t just save you money on taxes—it provides strategic advantages that many investors overlook:
No impact on taxable income calculations: This income won’t push you into higher tax brackets
Medicare surcharge protection: High-income earners can avoid additional Medicare premiums triggered by modified adjusted gross income (MAGI)
Alternative Minimum Tax (AMT) benefits: Tax-free municipal bond interest generally doesn’t trigger AMT calculations
Social Security taxation: Lower taxable income may reduce the taxation of your Social Security benefits
The Compound Effect of Tax Efficiency
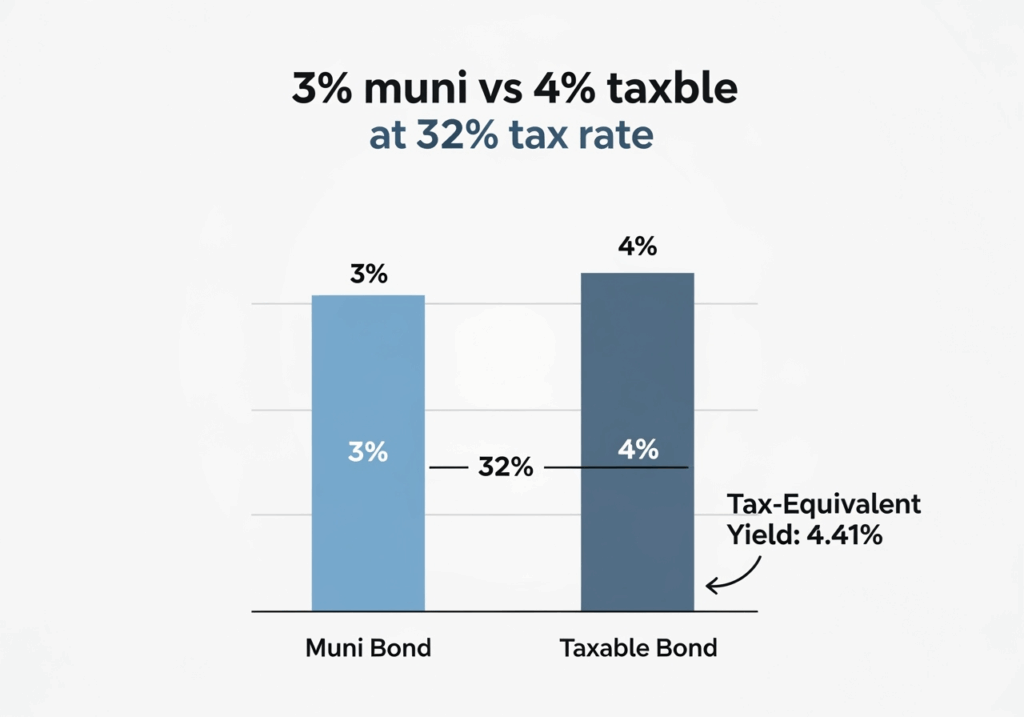
Consider this scenario: An investor in the 32% tax bracket earning 4% on taxable bonds nets only 2.72% after taxes. Meanwhile, a municipal bond yielding 3% provides the full 3% return—effectively outperforming the taxable investment while reducing risk.
Interest rate sensitivity: Shorter-duration municipal bonds provide protection against rate increases
Credit quality improvements: Many municipalities have strengthened their financial positions post-pandemic
Supply and demand imbalances: Limited municipal bond issuance has created attractive opportunities
The Missed Opportunity: Why Many Portfolios Aren’t Optimized
Common Portfolio Oversights
Many investors and their advisors focus primarily on gross returns without considering the tax implications. This oversight becomes particularly costly for:
Strategic Implementation: Making Tax-Free Income Work for You
1. Portfolio Assessment and Rebalancing
The first step is conducting a comprehensive analysis of your current investment allocation. This involves:
Evaluating your current tax burden from investments
Identifying opportunities to shift from taxable to tax-advantaged accounts
Analyzing the after-tax returns of your current holdings
2. Municipal Bond Strategy
For investors in higher tax brackets, municipal bonds can be particularly attractive:
General obligation bonds backed by the full faith and credit of the issuer
Revenue bonds supported by specific project income
Tax-exempt bond funds for diversification and professional management
3. Maximizing Roth IRA Benefits
Strategic Roth IRA planning includes:
Roth conversions during lower-income years
Backdoor Roth strategies for high-income earners
Long-term planning to maximize tax-free growth
4. Advanced Tax-Free Strategies
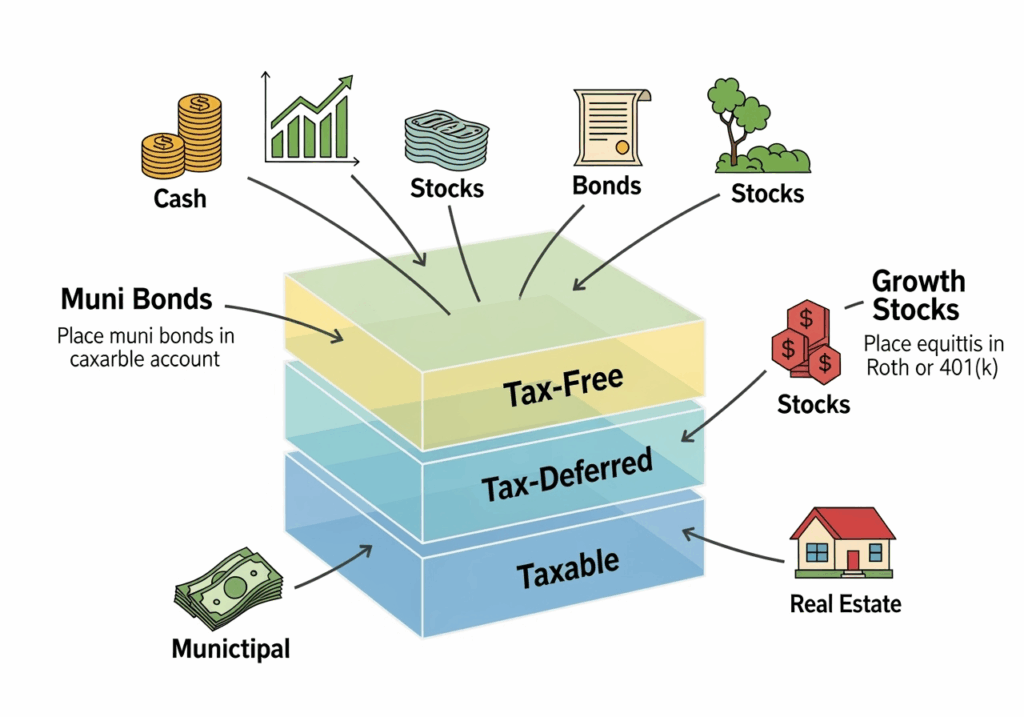
Asset Location Optimization:
Hold tax-inefficient investments in tax-advantaged accounts
Place tax-efficient investments in taxable accounts
Coordinate across multiple account types for maximum benefit
5. Tax-Loss Harvesting Coordination:
Realize losses in taxable accounts while maintaining tax-free growth elsewhere
Avoid wash sale rules when rebalancing across account types
Use tax-free income to reduce the need for taxable rebalancing
Global Considerations for International Investors
At Veritas Accounting Services, we understand that tax-efficient investing becomes even more complex for international investors and expatriates. Our global expertise across the US, UK, UAE, Singapore, Ireland, and Malaysia ensures that your tax-free investment strategy considers:
Treaty benefits between countries
Foreign tax credit optimization
Cross-border retirement planning
Compliance requirements in multiple jurisdictions
International Tax-Free Opportunities
Different countries offer unique tax-advantaged investment vehicles:
UK ISAs (Individual Savings Accounts): Tax-free growth and withdrawals
Singapore CPF: Comprehensive retirement and healthcare savings
Irish life assurance bonds: Tax-deferred growth opportunities
The Veritas Advantage: Comprehensive Tax-Efficient Planning
With over a decade of experience and 1000+ successful projects, Veritas Accounting Services specializes in creating holistic financial strategies that maximize after-tax returns. Our certified QuickBooks and Xero experts work closely with your investment advisors to ensure your portfolio is optimized for tax efficiency.
Our Integrated Approach Includes:
Tax planning consultations to identify optimization opportunities
Investment income analysis and tax impact assessments
Retirement planning coordination with tax-free income strategies
Ongoing monitoring to ensure continued tax efficiency
Technology-Driven Solutions
Our seamless integration with leading accounting platforms ensures:
Real-time tax impact monitoring of investment decisions
Automated reporting of tax-free income sources
Coordinated planning between business and personal finances
Compliance tracking across multiple jurisdictions
Take Action: Don’t Let Tax Inefficiency Erode Your Wealth
The opportunity cost of maintaining a tax-inefficient portfolio compounds over time. Every year you delay implementing tax-free investment strategies is another year of unnecessary tax payments and missed wealth accumulation.
Immediate Action Items:
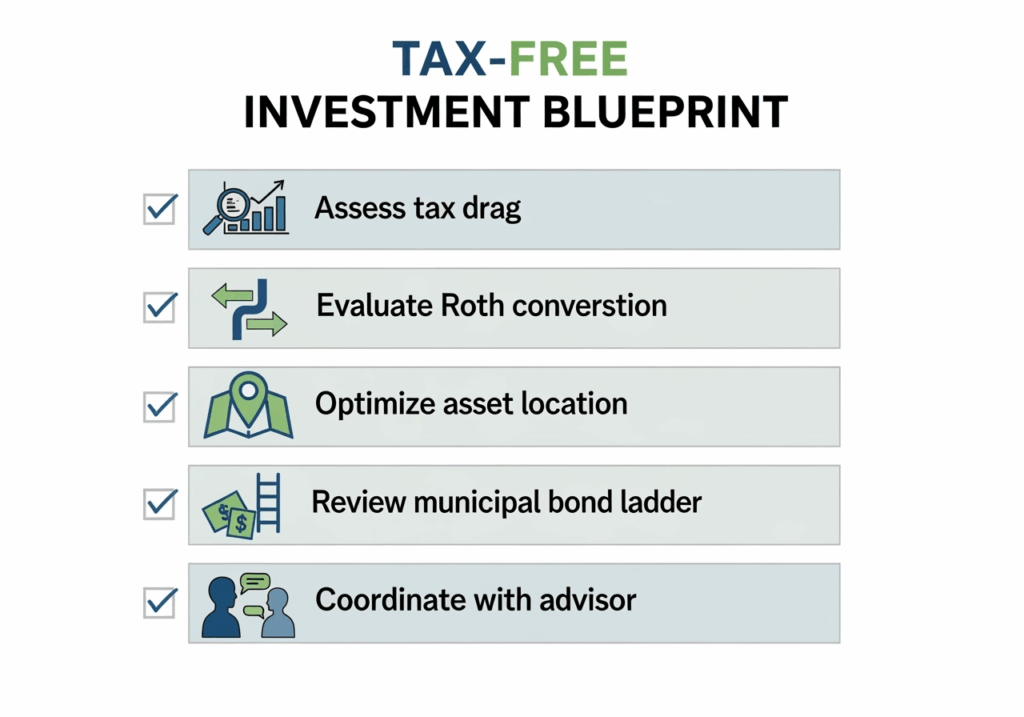
Calculate your current tax drag: Determine how much you’re paying in unnecessary investment taxes
Assess your tax bracket trajectory: Plan for future income changes
Review your asset location: Ensure tax-efficient placement of investments
Evaluate conversion opportunities: Consider Roth conversions during low-income periods
Next Steps:
Schedule a consultation to review your current investment tax burden
Analyze your portfolio for tax-efficiency opportunities
Develop a strategic plan to maximize tax-free income
Implement and monitor your optimized investment strategy
Conclusion
Tax-free investment income isn’t just about avoiding taxes—it’s about building a more efficient, sustainable wealth accumulation strategy. In today’s complex tax environment, the difference between tax-efficient and tax-inefficient investing can mean hundreds of thousands of dollars over a lifetime.
Don’t let this opportunity pass by. Contact Veritas Accounting Services today to discover how tax-free investment income strategies can transform your financial future.
Ready to optimize your investment portfolio for maximum tax efficiency?
Tax-Free Investment Income Tax-Free Investment Income Tax-Free Investment Income Tax-Free Investment Income Tax-Free Investment Income Tax-Free Investment Income Tax-Free Investment Income
To correctly classify business expenses is foundational to solid bookkeeping and financial decision-making. Yet, many business owners and freelancers trip up in this area—leading to lost deductions, inaccurate reporting, and extra stress during tax season. Let’s change that!
In this guide, you’ll learn:
What counts as a business expense (with real examples)
Why classification matters so much
Common and costly mistakes (and how to sidestep them)
Pro tips for flawless, stress-free accounting
Answers to the most frequent questions
A printable, actionable checklist to keep you organized
What Counts as a Business Expense? (With Real-World Examples)
Business expenses are the ordinary and necessary costs of running your company. But what does that mean in practice?
Here are popular categories and real examples for each:
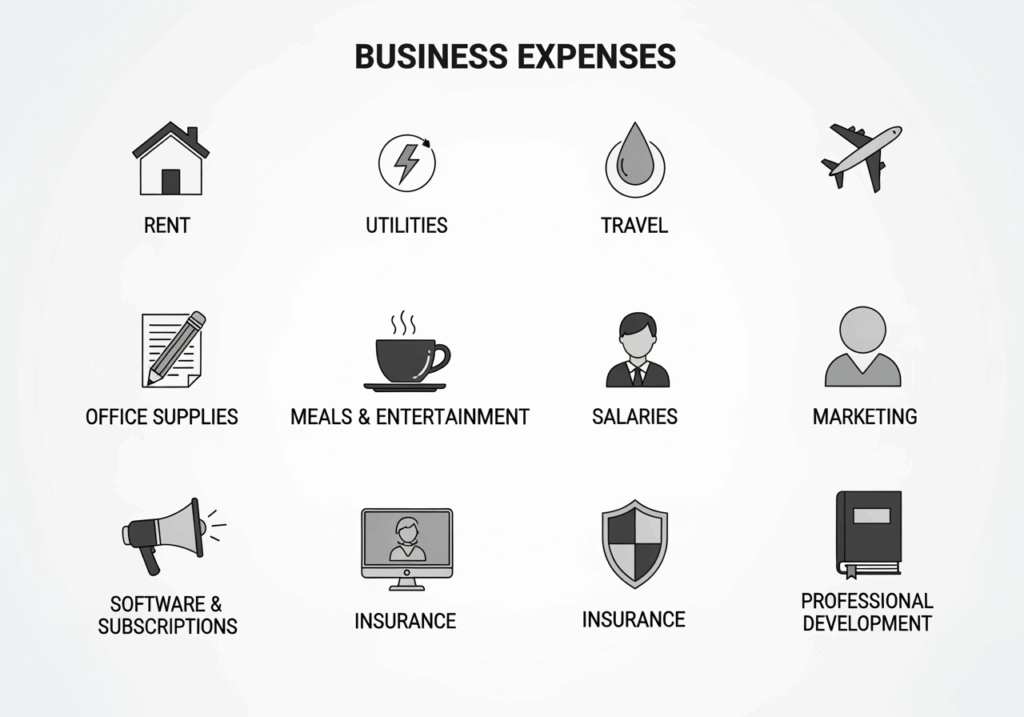
Travel: Airfare, mileage, taxis/rideshares, hotels, meals on work trips
Meals and Entertainment: Taking clients out for lunch, company event catering (subject to strict limits)
Salaries and Wages: Staff pay, bonuses, payroll taxes
Professional Services: Legal, accounting, consulting fees
Insurance: Business liability, workers comp, property insurance
Marketing and Advertising: Website fees, online ads, print materials
Depreciation: Gradual cost deduction for major purchases like machinery or vehicles
Pro Tip: If you’re ever unsure if an expense qualifies, ask yourself—”Is this cost directly related to earning business income?” If the answer’s yes, it likely qualifies.
Why Correct Classification Matters
Classifying business expenses correctly doesn’t just make life easier for your accountant. Here’s why it truly matters:
Maximize Tax Deductions: Many allowable business expenses directly reduce taxable income, meaning less money owed to the government (and more in your pocket).
Financial Insights: Accurate expense tracking reveals which parts of your business are costing the most—and where you can cut back.
Audit Readiness: Clean, careful records make audits quick and painless if you ever get selected.
Credibility with Investors/Banks: Lenders or investors like to see well-organized, easy-to-explain financials.
Common Expense Classification Mistakes (With Solutions)
Let’s explore mistakes in detail, with real-world fixes:
1. Mixing Personal and Business Finances
Example: You grab a coffee using your business card, but it’s not a work-related purchase.
Fix: Set up separate bank accounts and credit cards. If you make a mistake, note the transaction as an owner draw or personal reimbursement.
2. Misclassifying Expenses
Example: Coding a business lunch with a client as “Office Supplies,” or putting software under “Equipment.”
Fix: Use accounting software with preset categories. Review transactions monthly for accuracy.
3. Missing Out on Small Deductions
Example: Ignoring small subscriptions or petty cash expenses; assuming they’re “too minor.”
Fix: Track every expense, even $2 ones. Digital tools make this frictionless; use expense scanning apps or file receipts in Google Drive.
4. Lost or Incomplete Documentation
Example: Tossing receipts or not collecting itemized bills.
Fix: Go digital—scan with your phone, save PDFs, or use receipt-management platforms like Expensify or Dext.
5. Over- or Underclaiming Deductions
Example: Claiming the full cost of your personal mobile as a business expense, or not claiming your home office at all.
Fix: Claim only the business-use portion. For mixed-use items (like utilities at home), use a percentage based on actual use.
6. Not Updating Categories as Business Grows
Example: Sticking to overly simple categories (“other expenses,” “miscellaneous”) as your business expands.
Use cloud-based software like QuickBooks, Xero, Zoho, or Wave, which auto-categorizes common expenses (and syncs with your bank!).
Set up rules so recurring transactions (like your internet bill) are always coded to the right category.
Be Consistent
Define your categories clearly and always use them the same way.
If you have a team, create a simple one-pager explaining what belongs where.
Schedule a Monthly “Money Date”
Take 30 minutes at the end of each month to review your transactions, match receipts, and fix any uncategorized expenses.
Educate the Whole Team
Train employees on proper receipt submission and expense types.
Use an approval system for purchases, so random expenses don’t slip through.
Document Your Expense Policy
Put your rules in writing! This helps if you ever hire a bookkeeper or get audited.
Ask for Professional Help
An accountant or bookkeeper can review your setup, optimize your categories, and ensure you’re maximizing deductions.
FAQs: Business Expense Classification
Classify Business Expenses
Q: Can I deduct all meals with clients? A: Not always. Many tax authorities cap meal deductions at 50%, and receipts/documentation are required. Casual or non-business meals don’t qualify.
Q: What if I work from a home office—how do I classify those expenses? A: Calculate the percentage of your home used for business (by area or time) and claim that portion of rent, utilities, and insurance as a business expense.
Q: Is my car a business expense if I also use it personally? A: Only claim the percentage of car expenses related to business miles. Use a mileage log or mileage-tracking app.
Q: What if I make a mistake? A: Adjust the transaction and document the change. Most software allows easy recategorization.
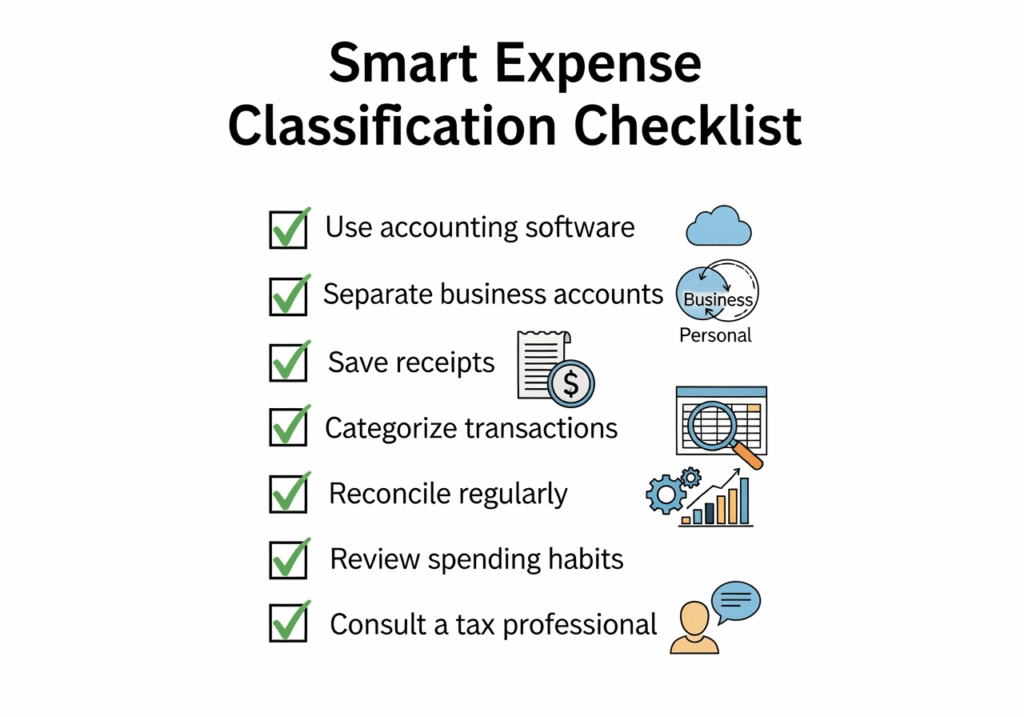
Actionable Checklist for Smarter Expense Classification
Feel free to print or bookmark this!
Setup
✅ Open designated business bank accounts ✅ Choose accounting or expense tracking software ✅ Create a clear chart of accounts (categories)
Ongoing Process
✅ Always use the business account for business purchases ✅ Save digital or physical receipts for all transactions ✅ Enter all expenses into your accounting system ✅ Review uncategorized/“miscellaneous” expenses each month ✅ Match bank and credit card transactions to entries ✅ Update categories as business grows
At Year-End
✅ Reconcile all accounts ✅ Check for missed deductions ✅ Provide clear records to your accountant ✅ Adjust categories for the new year’s goals
Final Thoughts
Getting business expense classification right isn’t just about tax season—it’s about taking charge of your business finances and making smarter decisions year-round. The more consistent (and organized) you are, the less likely you are to miss deductions, make costly errors, or panic during audits.
By using technology, documenting your process, and reviewing transactions regularly, you’ll build a system that works for you—not against you.
Need help setting up or reviewing your expense categories? Drop your questions in the comments or connect with our bookkeeping pros for a no-obligation consultation. Your future self—and your bottom line—will thank you!
classify business expenses classify business expenses classify business expenses classify business expenses classify business expenses classify business expenses classify business expenses classify business expenses classify business expenses classify business expenses classify business expenses classify business expenses classify business expenses classify business expenses classify business expenses classify business expenses classify business expenses classify business expenses
The need for bookkeepers to become strategic partners in today’s eCommerce landscape has never been greater. With eCommerce businesses rapidly expanding to multiple sales channels and automation technologies advancing at lightning speed, understanding how to streamline compliance, especially for sales tax, is essential for both client success and the growth of bookkeeping practices.
Why Multi-Channel eCommerce Changes Everything
Moving Beyond Traditional Bookkeeping
In the past, bookkeeping focused on ledgers and periodic reconciliations for a single online platform like Shopify or Amazon. Today, thriving eCommerce businesses operate on numerous platforms—Amazon, Shopify, eBay, Etsy, Walmart, Facebook Shops, and their own websites. Each generates unique data streams, reporting requirements, and tax obligations.
Key challenge: Manual processes can’t keep up. Studies show bookkeepers relying on old methods spend significantly more time for lower accuracy—investing up to 73% more effort yet achieving only around 64% accuracy in tracking sales tax compliance for multi-channel clients.
The Opportunity: Bookkeepers must transform into orchestrators of automated systems and real-time data specialists—using technology to minimize manual work and maximize insight.
The Rise of AI in Bookkeeping
Artificial intelligence has revolutionized multi-channel bookkeeping. AI-powered tools can now:
Auto-categorize transactions across channels.
Detect sales tax nexus triggers in real time.
Predict upcoming compliance needs based on client growth.
Results from AI adoption include:
89% reduction in manual data entry.
94% increase in sales tax tracking accuracy.
Capability for a bookkeeper to handle 3x more clients without extra staff.
This shift frees professionals to move from repetitive data entry into valuable client advisory and strategic roles instead.
Common Platform-Specific Bookkeeping Challenges
Each sales platform presents unique headaches:
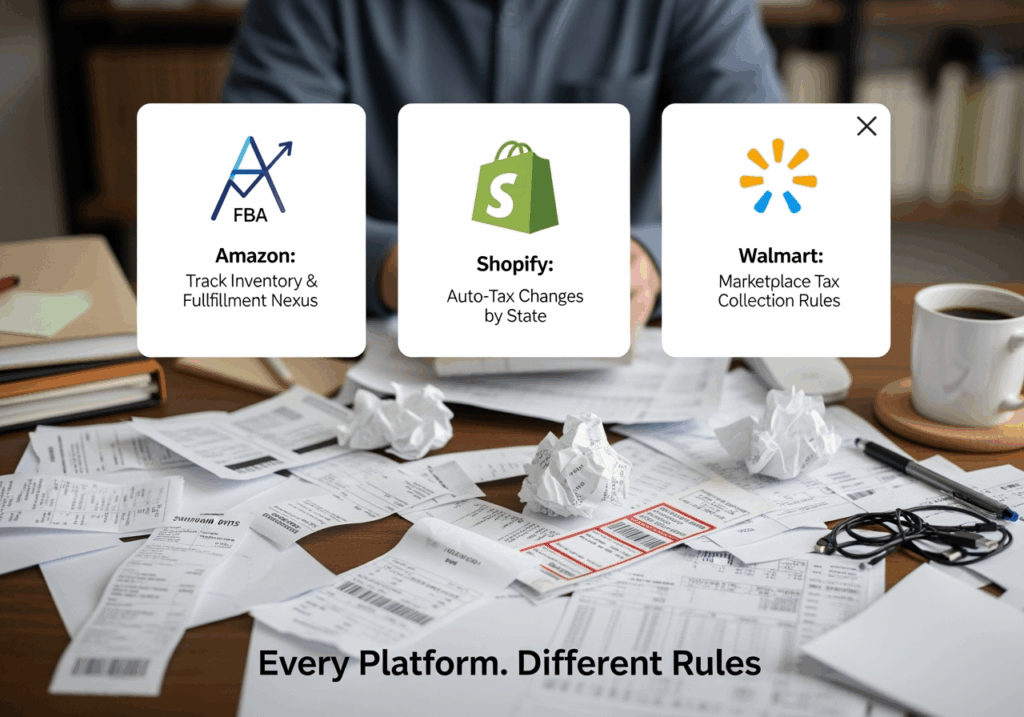
Amazon FBA: Requires inventory tracking across fulfillment centers and a deep understanding of marketplace tax collection rules.
Shopify: Ongoing regulatory changes make it crucial to re-examine sales tax setups, particularly as Shopify introduces automatic tax collection for relevant states.
Multi-channel Inventory: Managing stock and margins across platforms can quickly spiral out of control without automation.
General Compliance: Ensuring accurate documentation in the event of a tax audit is much more complex when multiple platforms are involved.
The Financial Impact of Multi-Channel Complexity
Bookkeepers can help clients not only avoid costly tax penalties but also directly improve operational efficiency.
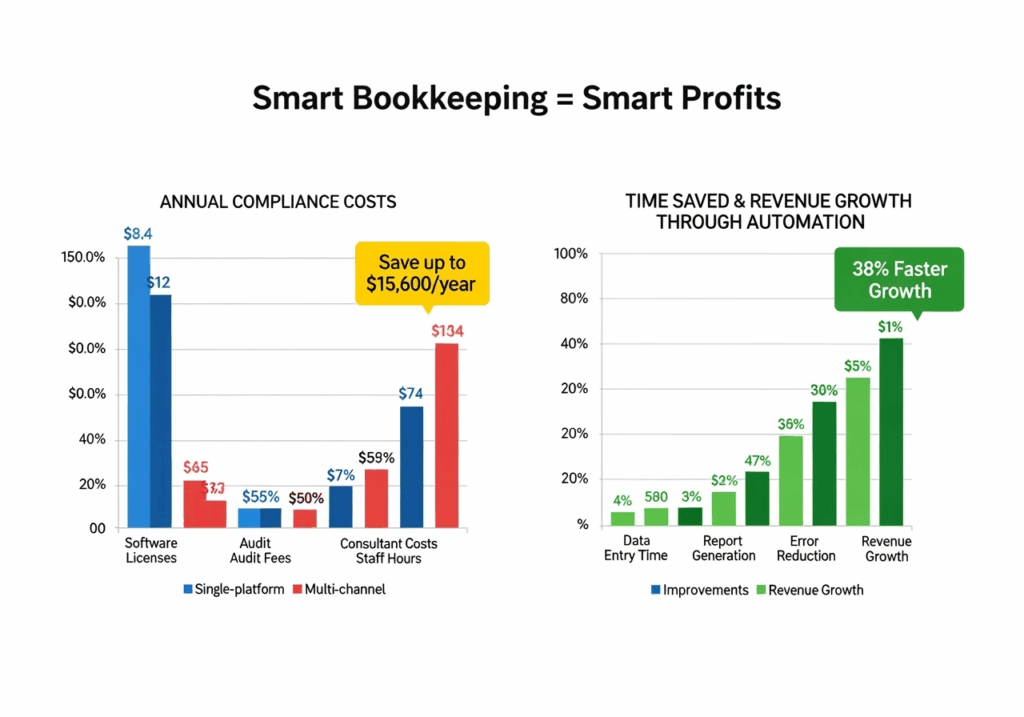
Cost of compliance and bookkeeping: Multi-channel stores typically spend $2,400–$4,800 a year (vs. $800–$1,200 for single-platform sellers).
Potential savings from professional management: $8,400–$15,600 per year through streamlined, automated workflows.
Revenue growth advantage: Businesses on multiple channels grow revenue 38% faster than those on a single platform.
The bottom line: Effective bookkeeping turns what many see as a cost into a profit driver, enabling scalability and peace of mind.
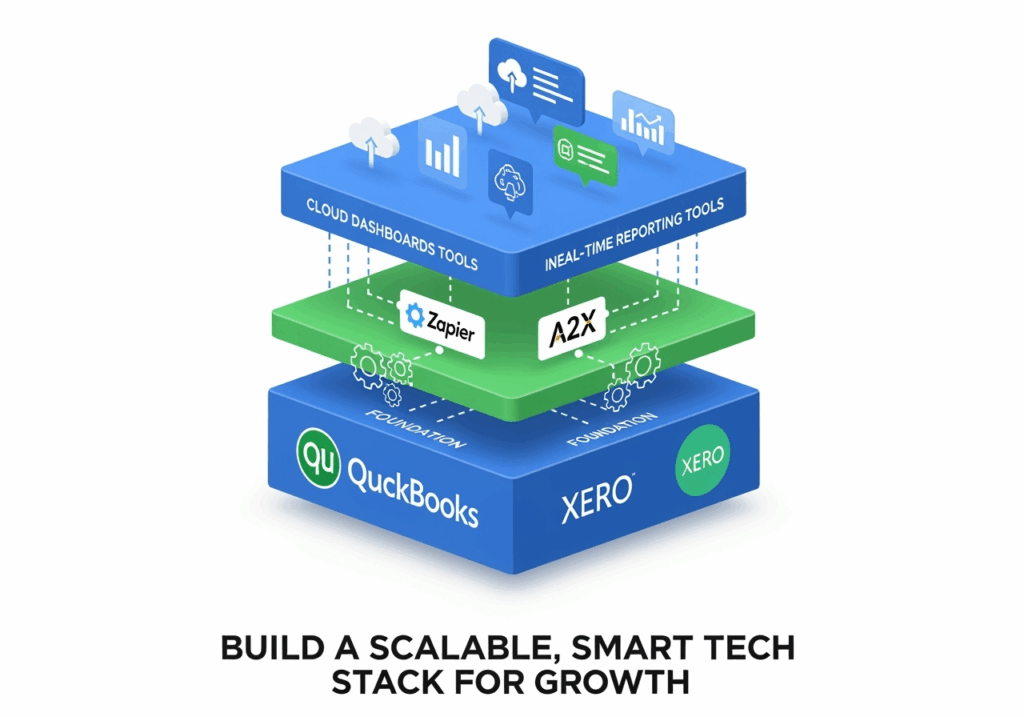
Today’s most successful bookkeeping practices rely on much more than accounting software like QuickBooks or Xero (though these should be your foundation).
Best-in-class practices also adopt:
eCommerce integration and automation tools (for sales data import, inventory sync, and multi-platform reconciliation).
Cloud-based dashboards, for 24/7 real-time access and collaboration.
Custom reports, breaking down profitability and compliance status by channel.
These investments deliver transparency, scalability, and confidence for both bookkeepers and clients.
Why Automated Sales Tax Management Is Essential
Sales tax compliance is the highest-value, most urgent service for eCommerce clients:
Multi-state nexus triggers: Identifying and registering for state sales tax as required by law.
Marketplace facilitators: Some platforms collect and remit tax, but your client is still responsible for reporting and proper record-keeping.
Automation platforms: Specialized sales tax apps eliminate manual tracking and ensure every filing is timely and complete.
Business impact: Clients typically see payback on automation within 4-6 months through penalty avoidance and saved time. For bookkeepers, sales tax services command premium rates but require minimal hands-on work after setup.
International Operations: A Lucrative Niche
International sellers entering the US face even greater complexity:
Navigating both US and home country regulations.
Handling US tax ID registration.
Managing currency and banking requirements.
These clients see the value in premium, expert services—often investing 40–60% more than domestic-only businesses. Mastering this area can set your firm apart and substantially grow your client base.
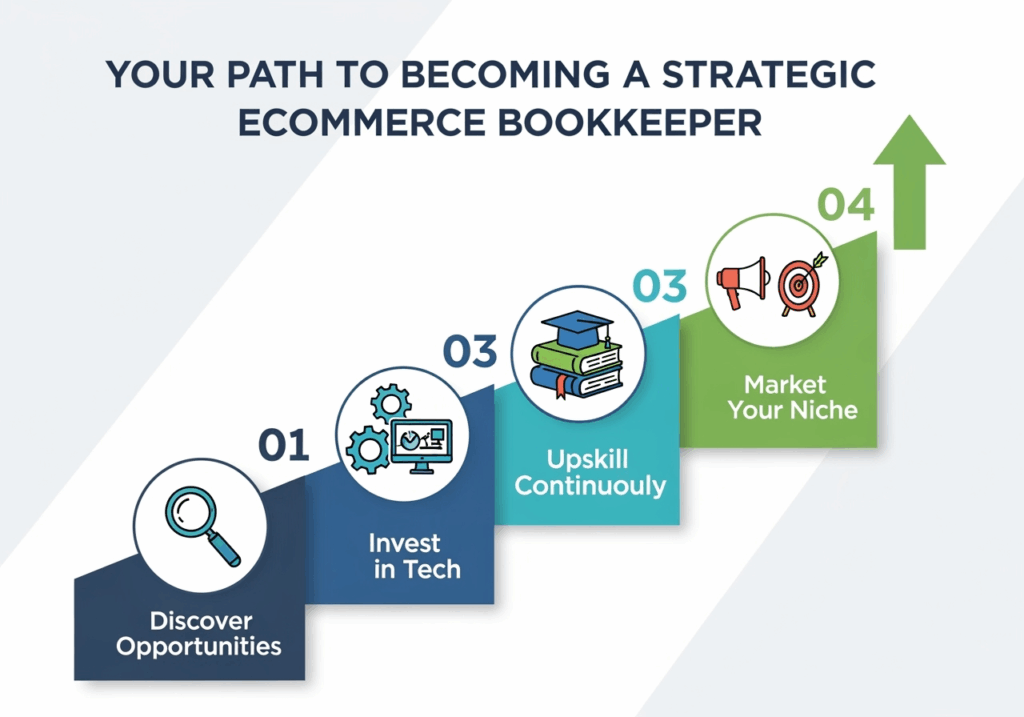
Step-by-Step: Growing Your Multi-Channel Bookkeeping Specialization
Identify potential within your existing clients. Many may be considering new sales channels—position yourself as their go-to advisor for expansion.
Invest systematically in technology. Start with core accounting integrations. Layer in automation as you add clients and revenue.
Commit to continuous learning. Stay up-to-date on eCommerce trends, tax rules, and new automation tools. This fosters innovation and justified premium billing.
Market your expertise. Tell your story clearly—how you help clients save time, avoid penalties, and optimize growth.
What the Future Holds?
eCommerce complexity and automation are only going to increase. Bookkeepers who future-proof their practices now will seize the biggest opportunities:
Combining technical skill with strategic advice.
Vying for top positioning in an expanding, lucrative market.
Serving as true partners in their clients’ growth journeys, rather than just vendors.
Why Partner with Veritas Accounting Services?
Choosing the right partner for your accounting and bookkeeping can be the difference between surviving and thriving in today’s eCommerce landscape. Veritas Accounting Services stands out through its deep expertise, innovative technology, and commitment to your business’s long-term success.
Built on Decades of Multi-Channel Experience
Veritas Accounting Services draws upon decades of hands-on experience, managing books and compliance for businesses with operations spanning the globe. This cross-border expertise means clients benefit from specialized knowledge in managing the challenges of international VAT, US sales tax, and complicated multi-channel reporting requirements. Whether you sell on Amazon, Shopify, Etsy, Walmart, or your own website, the Veritas team understands the pain points unique to eCommerce and knows how to navigate them smoothly.
Proprietary, Seamless Integration with Leading Software
The technology stack at Veritas is robust and highly adaptable. Clients enjoy seamless integration with industry-leading cloud platforms, including QuickBooks Online, Xero, Wave, Zoho Books, and other specialized eCommerce accounting tools. This integration not only speeds up processes, but also enables real-time reconciliation, inventory tracking, and advanced analytics across every channel you utilize—all while maintaining absolute accuracy and compliance. Automated solutions provided by Veritas eliminate manual data entry, drastically reduce errors, and free you to focus on scaling your business.
Proven Track Record: 340+ International Clients Served
When you work with Veritas, you join an expanding network of 340+ happy international brands who have successfully optimized and protected their financial operations. The results speak for themselves—Veritas clients consistently achieve a 99.7% compliance accuracy rate, drastically lowering exposure to penalties, tax audits, and administrative burden. By minimizing risk and creating transparent, audit-ready reporting, Veritas provides peace of mind so you can pursue growth with confidence.
More Than Bookkeepers—Strategic Growth Partners
Veritas doesn’t just keep your books; the team acts as your virtual CFO, advisor, and strategic partner. Their personalized process includes in-depth business analysis, proactive compliance monitoring, and recommendations on cashflow management, forecasting, and even process automation for scaling up efficiently. This level of involvement helps clients unlock hidden savings, capture new opportunities, and stay ahead of regulatory changes, both in the US and internationally.
Flexible, Scalable Services Designed for You
Whether you’re a fast-growing startup or a seasoned multinational, Veritas tailors its solutions to fit your needs. You gain the flexibility to scale services up or down as your operations evolve, thanks to the team’s experience with a wide range of business models and industries—from eCommerce and logistics to restaurants and professional services.
If you’re ready to build a future-proof, competitive, and growth-oriented practice—or need a dedicated accounting partner capable of supporting your multi-channel eCommerce ambitions—reach out to Veritas Accounting Services today at hello@veritasaccountingservices.com or call +1(678) 723-6003.
The landscape of multi-platform e-commerce selling has never been more complex, especially when it comes to sales tax nexus compliance. If you’re among the millions of entrepreneurs selling through both Shopify and Amazon, you’re navigating two fundamentally different tax collection systems that could cost you thousands in penalties if misunderstood.
Recent data shows that 73% of multi-platform sellers are making critical compliance mistakes, with the average penalty reaching $4,200 per business in 2024. The stakes have risen dramatically with Shopify’s announcement that they will begin collecting marketplace facilitator taxes automatically on all U.S. nexus transactions in 2025, fundamentally changing the compliance landscape for millions of sellers.
The Game-Changing Difference: Amazon vs. Shopify
Understanding the fundamental difference between Amazon and Shopify is crucial for your compliance strategy.
Amazon operates as a marketplace facilitator, meaning it creates a centralized storefront where multiple sellers offer products and maintains significant control over transactions. This classification requires Amazon to collect and remit sales tax on behalf of third-party sellers in all 45 sales tax states.
Amazon’s coverage is comprehensive — it handles approximately 89% of third-party seller obligations automatically. Whether you’re using FBA (Fulfilled by Amazon) or FBM (Fulfilled by Merchant), Amazon collects tax, manages complex inventory tracking across fulfillment centers, and even provides audit protection for covered transactions.
Shopify, conversely, has functioned as an e-commerce platform rather than a marketplace facilitator. It provides technology infrastructure for independent online stores but doesn’t create a centralized marketplace. This meant Shopify sellers were responsible for their own sales tax compliance — until now.
Shopify’s 2025 Revolution: What’s Changing
Here’s the game-changer: Shopify will begin automatic marketplace facilitator tax collection on U.S. nexus transactions in 2025. This represents a seismic shift affecting millions of Shopify stores and fundamentally altering the compliance landscape for multi-platform sellers.
Unlike Amazon’s blanket coverage, Shopify’s system will focus specifically on nexus-triggered obligations. This means Shopify will only collect tax in states where your business has established nexus through economic thresholds (typically $100,000 in annual sales) or physical presence.
The rollout timeline varies by store size. Shopify Plus merchants will see changes beginning in early 2025, while standard Shopify stores will transition throughout the year. This phased approach allows for system testing, but it also means you need to stay informed about your specific transition timeline.
The Multi-Platform Compliance Challenge
Here’s where it gets tricky for sellers using both platforms. Economic nexus thresholds are based on total sales into a state, regardless of platform. If you sell $60,000 through Amazon and $50,000 through Shopify into California, you’ve exceeded the $100,000 threshold and have nexus obligations.
Amazon will handle tax collection for its portion, but you’re responsible for ensuring compliance on Shopify sales. This coordination challenge is why multi-platform sellers reach nexus thresholds 67% faster than single-platform sellers and trigger nexus in an average of 4.7 states compared to 2.8 states for single-platform sellers.
State-by-State Variations That Matter
Different states have varying approaches that create additional complexity for multi-platform sellers:
California maintains a $500,000 threshold with no transaction count requirement. With $891 million collected in economic nexus enforcement revenue in 2024, California demonstrates aggressive enforcement that makes compliance essential.
Texas recently eliminated its transaction count requirement, focusing solely on the $500,000 revenue threshold. This simplification benefits multi-platform sellers by reducing tracking complexity.
New York maintains both revenue ($500,000) and transaction count (100 transactions) thresholds. The relatively low transaction count means multi-platform sellers can trigger nexus quickly, even with modest sales volumes.
Florida has implemented an automated nexus detection system that cross-references sales data from multiple sources — particularly relevant for multi-platform sellers who may not properly track combined sales.
The Hidden Costs of Multi-Platform Selling
The complexity of managing both platforms creates significant hidden costs. Research shows that businesses selling through both Amazon and Shopify spend an average of 73% more on compliance activities compared to single-platform sellers.
Data fragmentation represents one of the biggest challenges. Amazon provides detailed sales reports by state, but these must be combined with Shopify data to get a complete picture of nexus obligations. Many sellers struggle with this integration, leading to either over-compliance (unnecessary registrations) or under-compliance (missing nexus obligations).
Professional service utilization is significantly higher among multi-platform sellers, with 84% using external compliance help compared to 52% of single-platform sellers. This reflects both the increased complexity and the recognition that professional management often costs less than potential penalties.
Technology Solutions: Your Compliance Lifeline
Effective multi-platform selling requires sophisticated technology solutions that integrate data from both Amazon and Shopify while providing comprehensive compliance management. The complexity makes automation essential for most sellers.
Sales tax automation platforms now offer direct connections to both Amazon Seller Central and Shopify admin systems. These integrations automatically pull sales data, calculate combined nexus obligations, and provide real-time compliance monitoring across all channels.
The ROI is compelling: automated systems reduce compliance costs by an average of 67% compared to manual management, while improving accuracy from 77% to 97%. For sellers managing both platforms, automation typically pays for itself within 4–6 months.
International sellers face unique challenges when selling through both platforms in the U.S. market. The combination of cross-border requirements and multi-platform compliance creates challenges requiring specialized expertise.
U.S. tax ID requirements apply regardless of platform, but the process becomes more complex when selling through multiple channels. International sellers need an EIN (Employer Identification Number) that must be used consistently across all platforms to avoid compliance complications.
Banking considerations become critical. U.S. bank accounts are strongly recommended for tax remittance, and having a single account for both Amazon and Shopify sales simplifies reconciliation and compliance tracking.
Data shows that 91% of international multi-platform sellers use professional services, compared to 67% of domestic sellers, reflecting the additional complexity of managing both U.S. state tax obligations and home country requirements.
Preparing for Shopify’s 2025 Changes
The transition to Shopify’s marketplace facilitator system requires proactive planning. Here’s what you need to do:
Conduct a Nexus Analysis: Understand your current obligations before automatic collection begins. Include historical sales data, current registration status, and projected growth.
Review System Integration: Ensure your accounting systems can handle the change from manual to automatic tax collection. This may require software updates or configuration changes.
Update Documentation: Review existing exemption certificates, registration documents, and filing schedules to align with Shopify’s new system.
Stay Informed: Monitor your specific transition timeline, as changes will roll out throughout 2025.
Professional vs. DIY: Making the Right Choice
The decision between professional compliance management and DIY approaches becomes more complex for multi-platform sellers due to increased administrative burden and risk exposure.
DIY compliance for multi-platform sellers requires significant time investment — research shows sellers managing both platforms internally spend 18–25 hours monthly on compliance activities, compared to 8–12 hours for single-platform sellers.
The error rate is also significantly higher, with 34% of self-managed multi-platform sellers making compliance mistakes that result in penalties or over-compliance costs.
Professional service costs typically range from $400–800 monthly for comprehensive management, depending on sales volume and complexity. The break-even point occurs when monthly sales across both platforms exceed approximately $150,000, or when selling in more than 5 states with nexus obligations.
Veritas Accounting Services: Your Multi-Platform Partner
At Veritas Accounting Services, we understand the unique challenges facing multi-platform sellers navigating both Amazon and Shopify compliance requirements. Our decade of professional excellence across 6+ countries has equipped us with specialized expertise in managing complex, multi-channel tax obligations.
Our multi-platform clients achieve close to 99.7% compliance accuracy while reducing administrative burden by an average of 89%. Our integrated approach eliminates the data fragmentation that plagues many multi-platform sellers, providing clear visibility into combined nexus obligations and compliance requirements.
We offer comprehensive services including:
Automated threshold monitoring across all channels
Coordinated registration and filing management
Integrated reporting that combines Amazon and Shopify data
Strategic planning for platform expansion
For international sellers, we provide additional services including U.S. tax ID acquisition, cross-border banking coordination, and currency conversion tracking.
Your Path Forward
Success in multi-platform selling requires strategic thinking about compliance that goes beyond simply meeting minimum requirements. The most successful sellers view compliance as a competitive advantage, rather than a necessary burden.
With Shopify’s 2025 changes approaching, now is the time to evaluate your compliance strategy. Whether you choose professional management or enhanced DIY approaches, the key is taking action based on strategic priorities rather than reactive responses to regulatory complexity.
The e-commerce landscape continues evolving, with marketplace facilitator laws expanding and compliance requirements becoming more sophisticated. Multi-platform sellers who master these complexities now will be better positioned for future expansion and sustained profitability.
Don’t let compliance complexity limit your growth potential. 📩 Contact Veritas Accounting Services today at hello@veritasaccountingservices.com or +1 (678) 723-6003 to discuss your specific multi-platform compliance needs and discover how strategic compliance management can support your business success across both Amazon and Shopify.
Veritas Accounting Services — Transforming financial management with precision, compliance, and global expertise. Serving businesses across the US, UK, UAE, Singapore, Malaysia, and Ireland with over 1000+ successful projects completed.
Navigating sales tax compliance as a marketplace seller can be overwhelming, especially with constantly evolving regulations across 45 US states. With marketplace facilitator laws now generating over $13.7 billion annually and economic nexus thresholds affecting 2.4 million e-commerce businesses, knowing what to prioritize—and what to skip—has never been more critical. Prioritizing the right compliance strategies protects both your bottom line and your peace of mind.
Recent data from the sales tax Institute reveals a startling reality: 67% of marketplace sellers are either over-complying, wasting valuable resources on unnecessary tasks, or under-complying, risking substantial penalties. The average penalty for non-compliance reached $4,200 per business in 2024, while businesses that over-comply spend an unnecessary $2,400 annually on redundant compliance activities. This comprehensive guide will help you focus your efforts where they matter most while avoiding common compliance traps that drain time and resources without adding value.
Understanding Your Marketplace Coverage: The Foundation of Smart Compliance
Before diving into any compliance activities, you must understand your specific situation as a marketplace seller. Data-backed approach, 87% process reduction determines approximately 80% of your compliance obligations and can save you from countless hours of unnecessary work. The landscape has changed dramatically since marketplace facilitator laws took effect, with platforms now handling the vast majority of sales tax collection and remittance on behalf of their sellers.
Amazon, the largest marketplace, now collects tax in all 45 sales tax compliance states for FBA transactions, covering 89% of third-party seller obligations automatically. This means if you’re exclusively selling through Amazon FBA, your compliance burden has been reduced by nearly 90% compared to just five years ago. However, FBM (Fulfilled by Merchant) sellers still need to conduct separate analysis for transactions not covered by Amazon’s collection system.
eBay has similarly revolutionized compliance for its sellers through eBay Managed Payments, which covers 94% of transactions on the platform. Since implementation, seller registration requirements have been reduced by 67%, simplified the compliance landscape significantly for millions of sellers. Etsy handles collection in all applicable states for its craft and handmade sellers, maintaining a 91% compliance rate across its platform and providing small seller protection for transactions under $600 annually.
The key insight here is that many sellers are registering in states where their marketplace already handles everything, creating unnecessary filing obligations and ongoing costs. Data shows that 34% of marketplace sellers over-register, spending an average of $1,200 annually on compliance activities that provide no value. Understanding your platform’s coverage is the first step toward efficient compliance management.
Economic Nexus: Focusing on What Actually Matters
Economic nexus thresholds determine when you’re required to collect and remit sales tax in each state, but many sellers either over-monitor their obligations or focus on outdated metrics. The landscape has simplified significantly, with 67% of states eliminating transaction count requirements in favor of revenue-only thresholds.
California leads the pack with $891 million collected in 2024 from economic nexus enforcement, maintaining a $500,000 threshold with no transaction count requirement. Texas generated an additional $312 million through nexus enforcement, recently eliminating its transaction count requirement in January 2025. New York continues its aggressive enforcement approach with a $500,000 threshold and 100 transaction requirement, averaging $4,200 in penalties per non-compliant business. Florida has implemented a new automated nexus detection system, resulting in an 89% increase in penalty collections throughout 2024.
The smart approach to nexus monitoring involves tracking only revenue-based thresholds in states where you have realistic potential to reach them. Most marketplace sellers trigger nexus in an average of 3.2 states, making it counterproductive to monitor all 45 states if you’re only generating $200,000 in annual sales across all platforms. Setting alerts at 75% of relevant thresholds provides adequate planning time while avoiding the administrative burden of constant monitoring.
Transaction count tracking has become largely obsolete, with states like North Carolina, South Dakota, Wyoming, and Vermont eliminating these requirements in 2024-2025. This trend has resulted in an average 18% reduction in compliance costs for affected businesses and 4.2 hours of monthly time savings per business. The focus should be on states representing 80% of your sales volume rather than attempting to track every possible nexus scenario.
Strategic Registration: Avoiding the Over-Compliance Trap
Registration strategy is one of the most critical compliance decisions for marketplace sellers. Done correctly, it can save thousands annually. Done prematurely, it creates ongoing costs and filing burdens.
Home State vs. Multi-State Registration
Home State: Registration in your business’s home state is always required, even if your marketplace handles sales tax. Many sellers overlook this basic obligation.
Multi-State: Only register in other states if:
You’ve crossed economic nexus thresholds
Your marketplace doesn’t collect in those states
You conduct direct sales (non-marketplace)
Avoid registering in states just because they’re “potential” markets. Every registration triggers recurring obligations—even if you have no sales.
When Not to Register
Marketplace Handles Everything: If Amazon, Etsy, or eBay covers all tax collection and remittance in a state, registration is usually unnecessary.
No Nexus: If you’re far below the economic nexus threshold and not growing in that region, it’s inefficient to register.
No Sales Tax States: Alaska, Delaware, Montana, New Hampshire, and Oregon have no sales tax. Avoid unnecessary filings here.
Cost of unnecessary registration: $150–300 per year in filing fees per state, plus administrative costs and time.
Use Voluntary Disclosure When Appropriate
If you’ve operated without registering in a state where you had a tax obligation:
Consider Voluntary Disclosure Agreements (VDAs) in 38 states.
These can reduce penalties by up to 67% if addressed proactively.
Particularly helpful if you’re more than 6 months non-compliant.
Special Rules for International Marketplace Sellers
International sellers face additional complexity when selling in U.S. marketplaces. From tax IDs to banking and compliance gaps, the risks—and penalties—can be high.
Tax Identification & Entity Setup
Most U.S. states require either:
An Employer Identification Number (EIN) or
An Individual Taxpayer Identification Number (ITIN)
Choose the correct entity type (e.g., sole proprietor, LLC, corp) to avoid double taxation and classification issues.
Banking & Payment Infrastructure
Opening a U.S. bank account simplifies remittance and improves compliance.
Track currency conversions, international fees, and wire transfers to maintain a clean audit trail.
Use multi-currency accounting tools (e.g., Xero, Zoho Books) with U.S. tax integration.
Common Mistakes to Avoid
Applying home country VAT rules to U.S. sales tax
Assuming marketplace coverage applies in every state
Delaying U.S. compliance due to perceived complexity
Not realizing that marketplace coverage varies by state
Why Professional Guidance Helps
84% of international sellers use U.S.-based experts
Setup time reduced by 67%
Prevents costly errors that often cost $3,000+ to fix later
Unlocks cross-border tax efficiencies not visible to DIY sellers
Record Keeping: Essential Documentation Without Excessive Overhead
Effective record keeping strikes a balance between audit preparedness and operational efficiency. The key is maintaining critical documentation while avoiding the trap of over-documentation that consumes resources without adding protection value.
Essential documentation includes monthly sales reports broken down by state and jurisdiction, with clear separation between marketplace and direct sales. This information should categorize taxable versus non-taxable sales and maintain a clear audit trail for all transactions. Valid exemption certificates, including resale certificates, non-profit exemption documentation, and government entity exemptions, must be maintained for the full statutory period, typically four years or more.
Tax collection records deserve special attention, documenting the amount collected by jurisdiction, remittance confirmations, and complete audit trail documentation. For marketplace sellers, maintaining marketplace facilitator confirmations becomes crucial, including platform tax collection confirmations, coverage verification documents, and gap analysis documentation that clearly shows which transactions are covered by the platform versus requiring direct compliance.
The temptation to over-document can be counterproductive and expensive. Consider changing to: Daily sales tracking offers minimal audit advantage compared to monthly summaries, while individual transaction documentation for marketplace-collected sales creates unnecessary administrative burden. Detailed product categorization is only necessary when selling exempt items, and customer address verification is handled by the marketplace for platform sales.
Modern accounting software integration eliminates much of the manual documentation burden while providing superior audit trails. QuickBooks integration is used by 67% of small businesses, while Xero maintains a 23% market share with 91% satisfaction rates. Wave integration has become popular among startups due to its free tier availability, and Zoho Books continues growing at 45% annually with comprehensive feature sets.
Technology and Automation: Smart Investments for Long-Term Success
Technology investment in sales tax compliance delivers measurable returns when properly implemented. Sales tax automation tools provide an average ROI of 340% in the first year, with 94% error reduction in calculation mistakes and 87% reduction in manual processes. The key is selecting appropriate tools for your business size and complexity rather than over-engineering solutions.
Nexus monitoring systems provide real-time threshold tracking with 24-hour alert systems, maintaining 100% accuracy in nexus determination when properly configured. These systems integrate seamlessly with popular accounting platforms, creating automated workflows that eliminate manual tracking requirements. The time savings alone justify the investment, with businesses reporting reductions from 12 hours monthly to 1.5 hours monthly for compliance management.
However, technology mistakes can be costly and counterproductive. Multiple overlapping software solutions create confusion and duplicate costs, while enterprise-level tools often provide unnecessary complexity for small operations. Custom development should be avoided when proven off-the-shelf solutions exist, and manual spreadsheet tracking becomes counterproductive when automation is readily available and affordable.
The comparison between manual and automated approaches is stark. Manual tracking requires 12 hours monthly with a 23% error rate, while automated systems reduce this to 1.5 hours monthly with only a 3.2% error rate. Professional management services can reduce this further to 0.2 hours monthly with a 0.3% error rate, making the cost-benefit analysis clear for many businesses.
Audit Preparation: Focused Defense Without Paranoia
Audit preparation should focus on realistic risks rather than theoretical possibilities. High-risk audit triggers include rapid growth patterns with 200% or more year-over-year growth, sudden expansion into new states, and platform diversification. Compliance gaps such as late registrations, inconsistent filing patterns, and marketplace coverage gaps also increase audit likelihood.
Industry targeting affects audit probability, with electronics and technology sellers facing 34% higher audit rates, clothing and accessories sellers experiencing 28% higher rates, and health and beauty sellers seeing 31% higher audit rates. Understanding these patterns helps prioritize preparation efforts where they’re most likely to be needed.
Effective audit defense preparation involves maintaining organized digital records, documenting marketplace facilitator coverage clearly, keeping nexus analysis documentation current, and establishing professional representation relationships before they’re needed. The goal is creating a defensible position without excessive preparation for unlikely scenarios.
Over-preparation for audits wastes resources on low-probability events. Over-preparing for audits in states with minimal sales, focusing on historical periods fully covered by marketplace facilitators, and treating routine compliance reviews as formal audits all represent misallocation of compliance resources. The key is proportional preparation based on actual risk assessment.
International Marketplace Sellers: Navigating Cross-Border Complexity
International sellers face unique challenges when operating in US marketplaces, with 84% utilizing professional services to navigate the complexity. Sellers from the UK, UAE, Singapore, Malaysia, and Ireland must address US tax ID requirements, including EIN (Employer Identification Number) for tax purposes or ITIN (Individual Taxpayer Identification Number) for individuals, along with proper entity classification.
Banking and remittance considerations become critical for international sellers. US bank accounts are recommended for tax payments, requiring currency conversion tracking and international wire transfer documentation. The complexity of managing both home country obligations and US state requirements makes professional guidance particularly valuable for international operations.
Common mistakes include applying home country VAT logic to US sales tax, ignoring US state-level requirements, assuming marketplace coverage is universal across all jurisdictions, and delaying US compliance due to perceived complexity. These mistakes can result in significant penalties and sales tax compliance gaps that become expensive to correct.
Professional services show particular value for international sellers, with average setup time reduction of 67% when expert help is utilized. Cross-border tax optimization opportunities often exist that can offset service costs through improved tax efficiency and reduced sales tax compliance burden.
Cost-Benefit Analysis: Making Smart Investment Decisions
The decision between DIY compliance and professional services should be based on clear cost-benefit analysis rather than assumptions about complexity or cost. Professional services make sense when annual marketplace sales exceed $500,000, when selling in five or more states with nexus obligations, when facing audit or compliance issues, when operating internationally with US sales, or when time costs exceed service costs.
Veritas Accounting Services demonstrates the value proposition with a 99.7% compliance success rate across managed accounts, average penalty avoidance of $8,400 per client annually, 72% faster multi-state registration than industry average, and 94% client retention rate over five years. These results reflect the measurable benefits of professional management for appropriate situations.
DIY approaches work effectively when operating through a single marketplace with full coverage, generating annual sales under $200,000, operating in one to two states only, having strong accounting background, and maintaining adequate time for compliance management. The key is honest assessment of capabilities and time availability.
The investment analysis shows typical professional service ranges from $1,200-2,400 for basic nexus analysis and setup, $200-500 monthly for ongoing compliance management, $150-300 per state for multi-state registration and filing, and $2,400-4,800 for international seller setup. Measurable returns include $8,400-15,600 annually in penalty avoidance, $3,200-6,400 annually in time savings value, and $1,200-3,600 annually in over-compliance elimination, resulting in net annual benefits of $12,800-25,600.
State-Specific Priorities: Strategic Focus for Maximum Impact
Effective compliance management requires prioritizing states based on actual impact rather than theoretical obligations. Tier 1 priority states demand immediate attention and include California with $891 million collected in 2024 and aggressive enforcement, Texas with $312 million additional revenue from nexus and 45% audit increases, New York with $4,200 average penalties per non-compliant business, and Florida with new automated detection systems and 89% penalty increases.
Tier 2 priority states require close monitoring and include Illinois with strong enforcement and marketplace facilitator gaps, Pennsylvania with complex local tax requirements, Washington with destination-based sourcing complexities, and Ohio with frequent threshold changes. These states represent the next level of compliance priority for most marketplace sellers.
Lower priority states for most sellers include those with minimal sales volume, comprehensive marketplace coverage, higher thresholds of $500,000 or more, and infrequent enforcement actions. Allocating equal attention to all states wastes resources that could be better focused on high-impact jurisdictions.
The strategic approach involves analyzing your specific sales patterns and growth trajectory to identify which states will require attention over the next 12-18 months. This forward-looking analysis prevents reactive compliance while avoiding unnecessary preparation for unlikely scenarios.
Seasonal Planning: Timing Your Compliance Activities
Seasonal considerations significantly impact compliance efficiency and cost-effectiveness. The Q4 compliance rush from October through December requires close monitoring of threshold proximity, preparation for year-end nexus triggers, advance planning for January registrations, and coordination with tax season preparation. Many sellers cross nexus thresholds during holiday sales periods, making proactive planning essential.
Q1 planning from January through March provides optimal timing for annual nexus analysis and planning, registration updates and renewals, system upgrades and integrations, and professional service evaluations. This period offers the best opportunity for strategic compliance planning before the business year accelerates.
Mid-year reviews in June and July enable threshold monitoring and projections, compliance gap analysis, technology performance review, and cost-benefit reassessment. This timing allows course corrections before year-end complications arise.
Avoiding last-minute compliance rushes prevents costly mistakes and penalties. Common timing mistakes include waiting until December to check nexus status, delaying registration until after threshold breach, ignoring mid-year planning opportunities, and taking reactive rather than proactive approaches to compliance management.
Common Mistakes: Learning from Others’ Expensive Errors
The top five marketplace seller mistakes cost businesses thousands of dollars annually in unnecessary expenses and penalties. Double registration, where sellers register in states where their marketplace already handles tax collection, creates ongoing filing obligations without benefit. Threshold miscalculation, including marketplace-collected sales in nexus calculations, leads to premature registration and unnecessary costs.
Filing when not required, submitting returns in marketplace-covered states, creates administrative burden and potential audit triggers. Ignoring available exemptions and deductions increases tax liability unnecessarily. Poor record keeping inadequately prepares businesses for audit defense while creating operational inefficiencies.
The financial impact of these mistakes is substantial. Over-compliance results in average annual costs of $2,400 per seller, while under-compliance penalties average $4,200 per incident. Professional correction costs range from $1,800-3,600 per mistake, making prevention significantly more cost-effective than correction.
Time-wasting activities that don’t add value include daily sales tax monitoring, registering in every state “just in case,” manual calculation when automation is available, excessive documentation for covered transactions, and constant regulation monitoring without strategic focus. Eliminating these activities frees resources for value-adding business activities.
Your Path Forward: Strategic Implementation
Success in marketplace seller compliance comes from strategic focus rather than comprehensive coverage. Understanding your specific situation, prioritizing high-impact activities, leveraging appropriate technology, and maintaining proportional preparation creates sustainable compliance without excessive burden.
At Veritas Accounting Services, our decade of professional excellence across 6+ countries has helped over 1,000 marketplace sellers navigate these complexities with measurable results. Our 99.7% compliance success rate, combined with average annual savings of $15,600 in avoided penalties and over-compliance costs, demonstrates the value of strategic professional partnership.
The choice between DIY and professional management should be based on clear analysis of your specific situation, growth trajectory, and resource availability. Whether you choose independent management or professional partnership, the key is taking action based on strategic priorities rather than reactive responses to regulatory complexity.
Need help with compliance? Schedule a free 30-minute consultation with Veritas Accounting Services to assess your Sales Tax Compliance strategy and avoid costly mistakes.
For marketplace sellers ready to optimize their compliance approach, Veritas Accounting Services offers comprehensive analysis and strategic guidance. Contact us at hello@veritasaccountingservices.com or +1(678) 723-6003 to discuss your specific situation and explore how strategic compliance management can support your business growth while minimizing regulatory burden.
The marketplace selling landscape continues evolving, but the principles of strategic compliance remain constant: focus on what matters, avoid what doesn’t, and maintain proportional preparation for realistic scenarios. Your Sales Tax Compliance approach should support business growth rather than constraining it, creating sustainable systems that scale with your success.