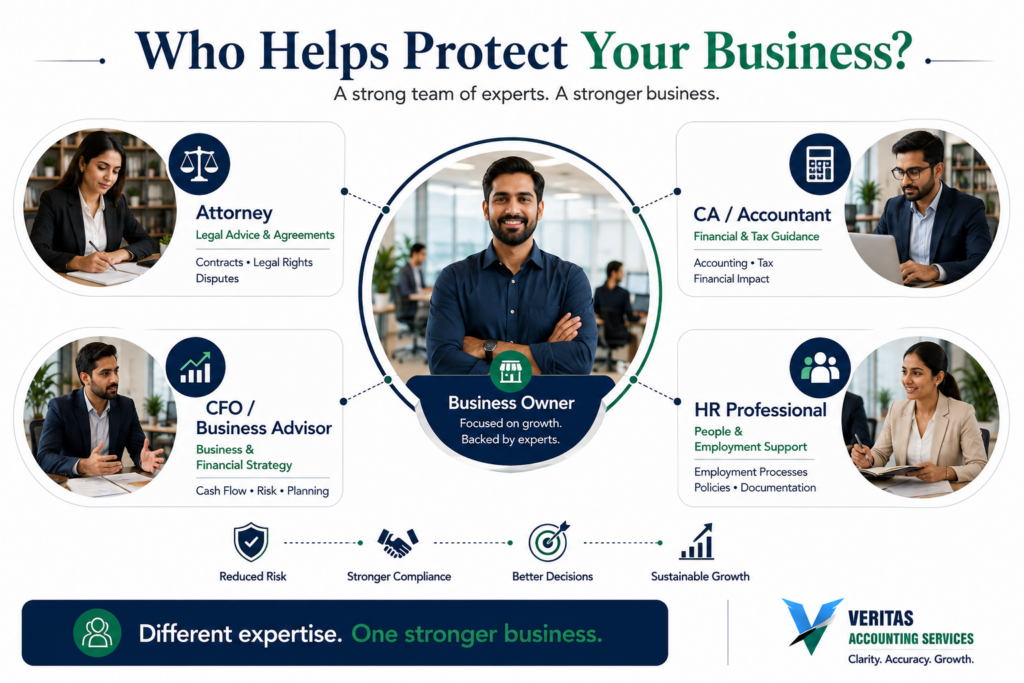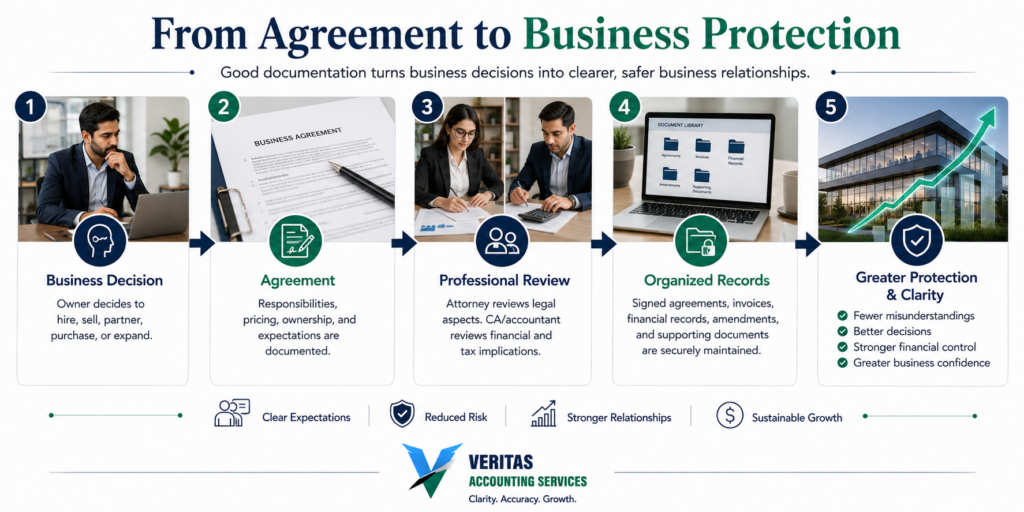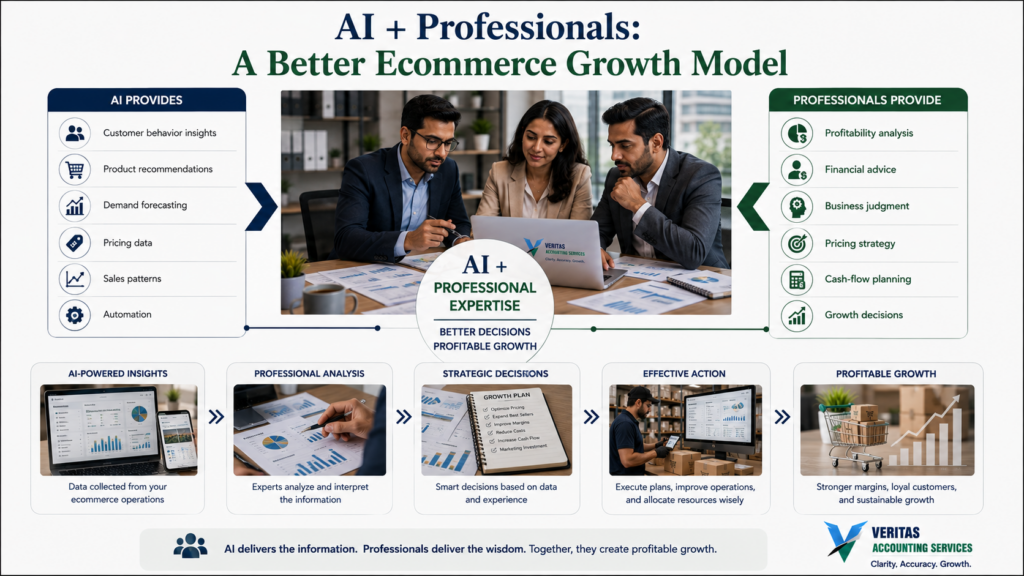
📩 Get A Quote : hello@veritasaccountingservices.com
Leadership

The Difference Between Leadership and Management: Why Businesses Need Both

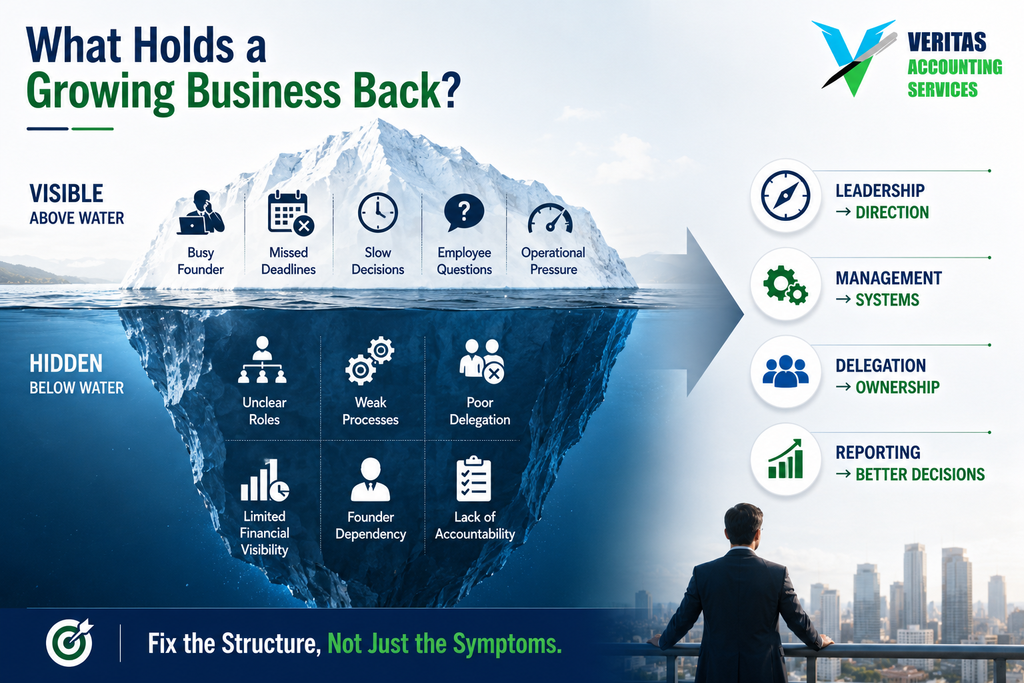
A business can have talented employees, strong products and healthy revenue—and still struggle to grow.

One common reason is the gap between leadership and management.

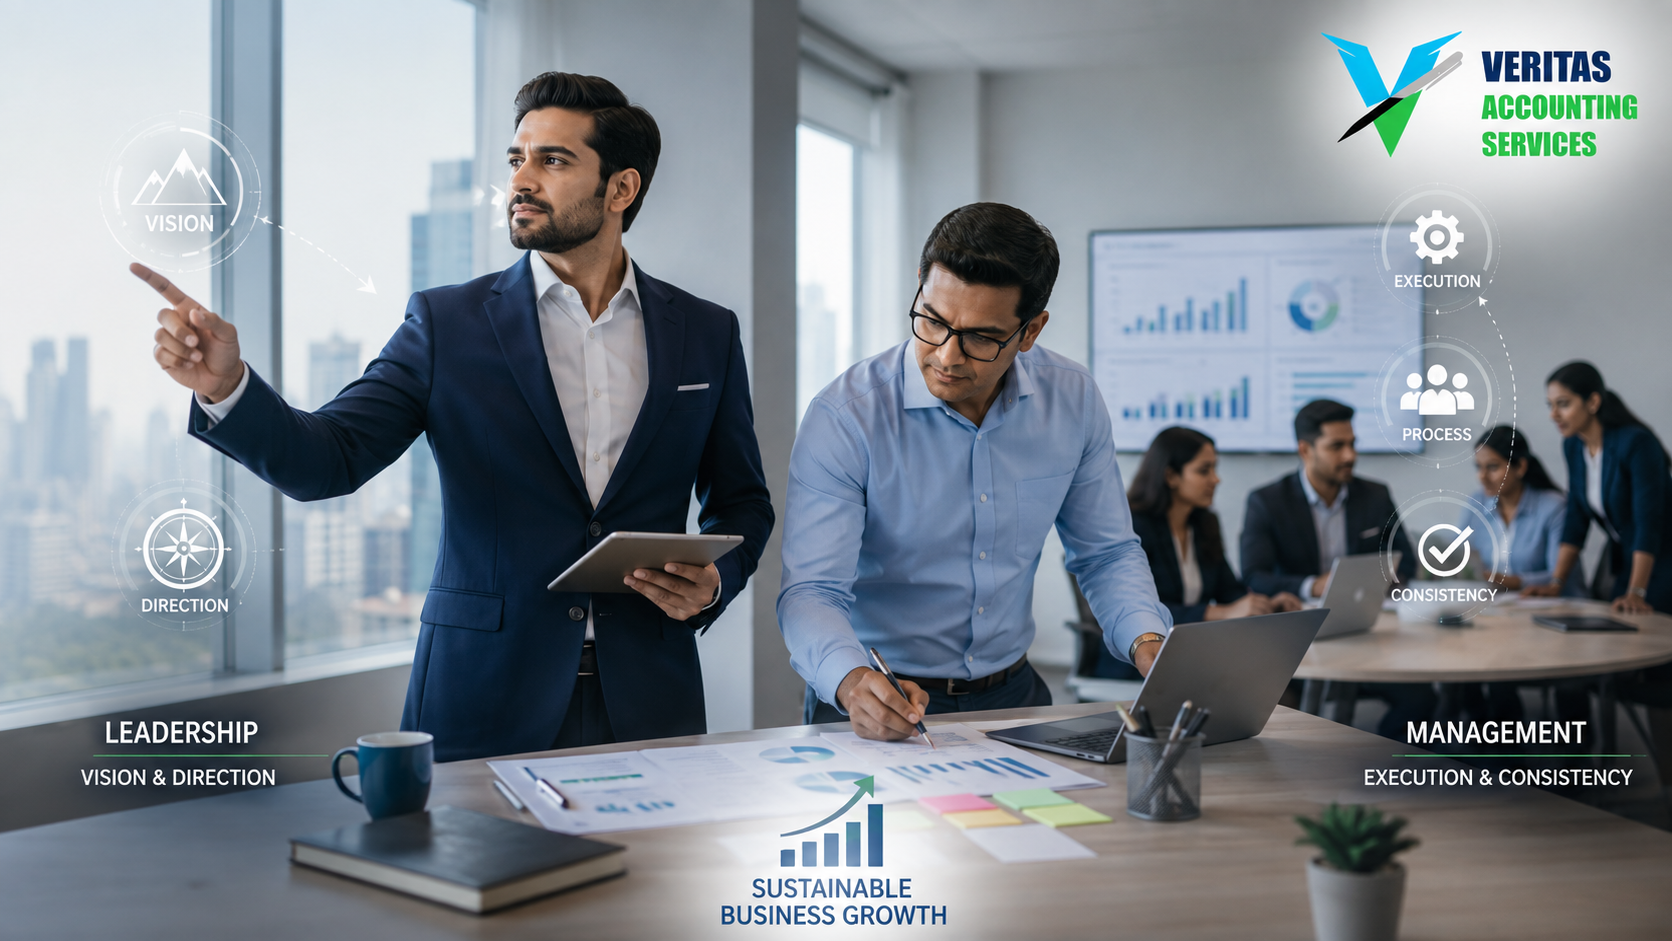
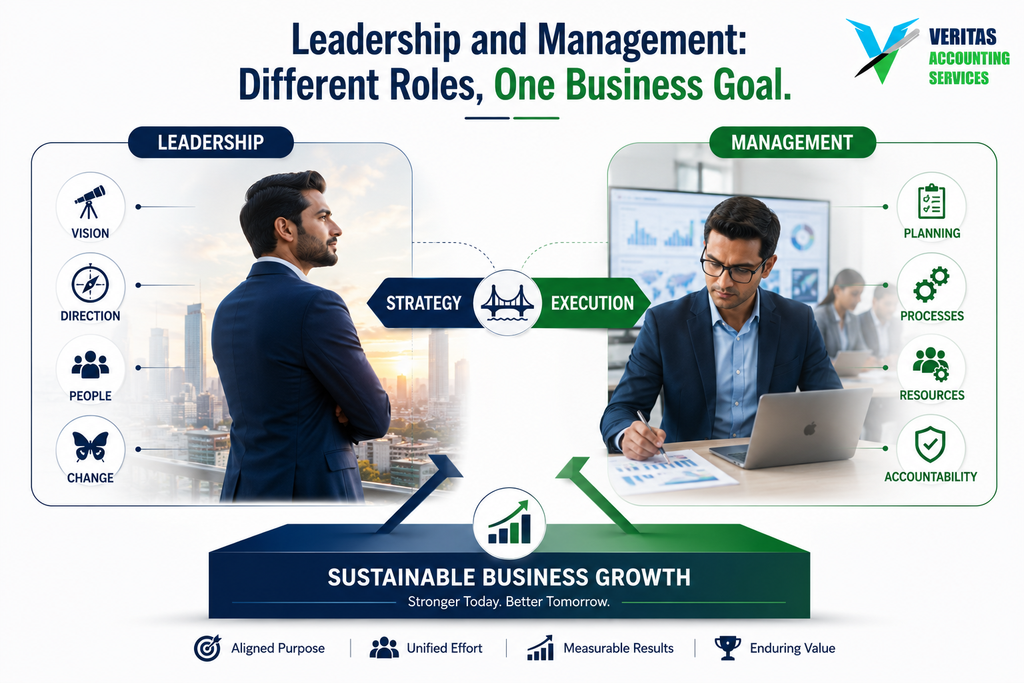
The two terms are often used interchangeably, but they represent different responsibilities. Leadership is largely about direction, purpose and people. Management is about execution, systems, resources and accountability.

A growing business needs both.

A company with strong leadership but weak management may have an inspiring vision but struggle with deadlines, processes and consistency. A company with strong management but weak leadership may run efficiently but lack innovation, direction or the ability to adapt.

The challenge for business owners is learning when to lead, when to manage, and when to build systems that allow others to take responsibility.

Table of Contents

  1. What Is Leadership?
  2. What Is Management?
  3. Leadership vs. Management: The Core Difference
  4. Why Businesses Need Both
  5. Leadership Creates Direction
  6. Management Turns Plans Into Results
  7. Where Business Owners Often Struggle
  8. Delegation: The Bridge Between Leadership and Management
  9. Financial Information Supports Better Management
  10. How Outsourced Professionals Can Support Leaders
  11. Building a Business That Does Not Depend on One Person
  12. Practical Questions for Business Owners
  13. FAQ
  14. Conclusion

What Is Leadership?

Leadership is about influencing people toward a shared objective.

A leader answers questions such as:

  • Where are we going?
  • Why does the business exist?
  • What do we want to achieve?
  • What values should guide our decisions?
  • What kind of organization are we building?

Leadership requires communication, judgment and the ability to make decisions when the future is uncertain.

For a founder, leadership might mean deciding which market to enter, which customers to serve, what type of culture to build, or when the business needs to change direction.

Leadership is not necessarily connected to a job title.

A department head, project leader or experienced employee can demonstrate leadership even without being the business owner.

What Is Management?

Management focuses on turning objectives into organized action.

Managers are responsible for areas such as:

  • Planning
  • Budgeting
  • Scheduling
  • Resource allocation
  • Performance monitoring
  • Process management
  • Delegation
  • Accountability
  • Problem resolution

If leadership determines where the organization should go, management helps determine how it will get there.

Consider a company that wants to expand into a new market.

Leadership may establish the objective and communicate why the expansion matters.

Management must then coordinate budgets, employees, timelines, technology, marketing, operations and reporting to make the plan achievable.

Neither function is sufficient on its own.
Leadership vs. Management: The Core Difference

The difference becomes clearer when we compare their primary focus.

LeadershipManagement
Creates directionOrganizes execution
Builds a visionBuilds processes
Inspires peopleCoordinates people
Encourages changeCreates consistency
Focuses on the futureFocuses on current performance
Makes strategic choicesImplements plans
Builds commitmentCreates accountability

These are not competing responsibilities.

They are complementary.

A strong business leader should understand management, and an effective manager should understand the broader direction of the organization.

The most successful companies create an environment where vision and execution reinforce each other.

Why Businesses Need Both

A business needs leadership to determine its destination and management to make the journey sustainable.

Imagine a company with an ambitious five-year growth target.

Leadership might establish the target, define the strategic priorities and communicate the vision to the team.

Management then needs to answer practical questions:

  • How much investment is required?
  • How many employees are needed?
  • What processes need to change?
  • Which performance indicators should be monitored?
  • What is the monthly budget?
  • How will customer service capacity increase?
  • What risks need to be controlled?

Without leadership, the organization may lack direction.

Without management, the strategy may never become reality.

This is why leadership and management should be developed together rather than treated as completely separate disciplines.

Leadership Creates Direction

One of the most important responsibilities of a business leader is deciding what not to pursue.

Growing companies constantly encounter new opportunities.

A new customer may request a different service. An employee may suggest a new product. A competitor may enter a new market.

Leadership requires evaluating these opportunities against the company’s long-term strategy.

For example, a professional services firm may receive an opportunity to offer ten different services.

The leadership question is not simply:

“Can we do this?”

It is:

“Should this be part of our strategic direction?”

Good leaders create focus.

They communicate priorities clearly so that employees understand what deserves attention and what does not.

Management Turns Plans Into Results

Once direction has been established, management becomes critical.

A strategy is only valuable when it can be executed.

Suppose management has decided to improve profitability by 10%.

That objective needs to become measurable actions.

The management team may need to:

  1. Analyze current margins.
  2. Identify high-cost areas.
  3. Review pricing.
  4. Monitor employee productivity.
  5. Reduce unnecessary expenses.
  6. Improve billing and collections.
  7. Establish monthly performance targets.

This is where effective management creates structure.

Without processes and accountability, even a strong strategy can remain an attractive presentation rather than a measurable business outcome.

Where Business Owners Often Struggle

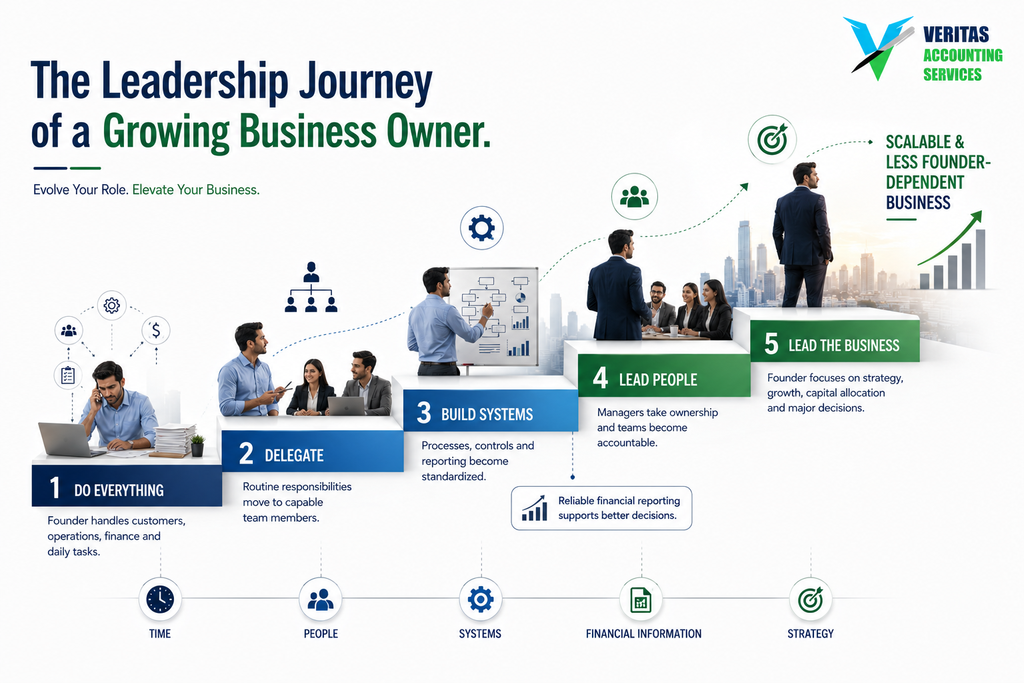
Many founders begin as both the leader and the manager.

They sell to customers, approve payments, supervise employees, review bookkeeping, solve operational problems and make strategic decisions.

That may work in the early stages.

The problem arises when the business grows but the owner’s role does not change.

A founder who continues to personally approve every small decision can become the organization’s biggest bottleneck.

This is often a sign that management systems have not evolved with the business.

Business owners should gradually move away from being the person who solves every problem and toward becoming the person who builds the people, processes and systems that solve problems consistently.

That transition is an important part of leadership development.

Delegation: The Bridge Between Leadership and Management

Delegation is not simply assigning tasks to employees.

Effective delegation involves transferring responsibility and authority while maintaining appropriate accountability.

A business owner should be clear about:

  • What needs to be completed
  • Who owns the responsibility
  • What standard is expected
  • When it must be completed
  • How performance will be measured
  • When the issue should be escalated

Poor delegation sounds like:

“Please take care of this.”

Effective delegation sounds more like:

“You own this process. Here is the expected outcome, deadline and reporting requirement. Let me know if an issue exceeds these defined limits.”

This allows the owner to spend more time on strategic decisions while managers and employees handle operational responsibilities.
Financial Information Supports Better Management

Leadership decisions become stronger when they are supported by reliable financial information.

Revenue alone does not tell a business owner whether the company is performing well.

Management should understand:

  • Gross margins
  • Operating expenses
  • Cash flow
  • Accounts receivable
  • Accounts payable
  • Customer profitability
  • Budget versus actual results
  • Revenue trends
  • Key performance indicators

For example, a business may report strong sales growth while cash flow deteriorates because customers are taking longer to pay.

Leadership needs to decide how the company should respond.

Management needs reliable reporting to identify the problem, monitor collections and measure whether corrective action is working.

This is one reason accounting should not be viewed only as a compliance function.

Accurate financial reporting provides information that supports better management decisions.

How Outsourced Professionals Can Support Leaders

As businesses grow, owners often discover that they need more expertise than they can build internally.

That does not necessarily mean hiring a full-time specialist for every function.

Outsourcing can provide access to experienced professionals in areas such as:

  • Bookkeeping
  • Accounting
  • Tax support
  • Financial reporting
  • Budgeting
  • Cash-flow forecasting
  • Payroll
  • CFO advisory

An external accounting team can take responsibility for recurring financial processes while giving management timely information for decision-making.

For example, instead of spending hours reviewing transactions, a business owner can receive organized monthly financial reports and focus on questions such as:

Why did gross margin change?

Which customers are most profitable?

Can we afford the next hire?

What will our cash position look like three months from now?

This is where professional accounting support can contribute to both management and leadership.

At Veritas Accounting Services, we support businesses and professional firms with bookkeeping, accounting, tax support, financial reporting, budgeting, forecasting and CFO-related services.

The objective is not simply to maintain records.

It is to help businesses maintain reliable financial information so owners and managers can spend more time making informed decisions.
Building a Business That Does Not Depend on One Person

A strong business should not stop functioning when its founder takes a week off.

If every customer relationship, approval, financial decision and operational process depends on one person, the business has a scalability problem.

Leaders should gradually build:

Clear Roles → Documented Processes → Delegated Authority → Reliable Reporting → Accountability

This creates organizational independence.

For example, instead of the owner personally reviewing every supplier invoice, the business can establish an approval process with defined limits.

Instead of the owner preparing every management report, the accounting team can produce standardized reports each month.

Instead of employees asking the founder about every operational issue, documented procedures can provide clear guidance.

These systems allow the leader to focus on growth while management keeps the organization running effectively.

Practical Questions for Business Owners

If you are evaluating your own organization, ask these questions:

1. Am I spending enough time on strategy?

If most of your week is consumed by operational tasks, your business may need better delegation or management systems.

2. Are responsibilities clearly assigned?

Every important recurring process should have an identifiable owner.

3. Do managers have enough authority?

Responsibility without authority creates frustration and slows decision-making.

4. Do I receive financial information on time?

Late or unreliable reports make both management and leadership decisions harder.

5. Can the business operate without me?

If the answer is no, identify the processes that depend on you and begin documenting and delegating them.

6. Are we measuring outcomes?

Employees should understand how their work contributes to business objectives.

7. Where do we need external expertise?

Some functions can be handled internally, while others may be more efficiently supported by specialized external professionals.

These questions can reveal whether the organization has a leadership problem, a management problem, or simply a systems problem.

FAQ

What is the main difference between leadership and management?

Leadership focuses primarily on direction, vision, people and strategic change, while management focuses on planning, execution, processes, resources and accountability.

Can someone be both a leader and a manager?

Yes. In many businesses, particularly smaller companies, the same person performs both roles. As organizations grow, these responsibilities may become distributed across different people.

Why do growing businesses need both leadership and management?

Leadership provides direction and purpose, while management creates the structure needed to execute the strategy consistently.

How does accounting support leadership and management?

Reliable accounting provides financial information about profitability, cash flow, expenses, margins and performance, helping leaders and managers make informed decisions.

Can outsourcing help improve management?

Yes. Outsourcing specialized functions such as bookkeeping, accounting and tax support can give businesses access to expertise while allowing internal managers to focus on core operations.

Conclusion

Leadership and management are not opposing approaches.

They are two sides of building a sustainable business.

Leadership establishes direction, creates purpose and helps people understand where the organization is going.

Management turns that direction into processes, responsibilities, budgets, measurements and results.

As a business grows, the owner’s role must evolve as well. Doing everything personally may help a company get started, but building systems, developing people and delegating responsibility are essential for sustainable growth.

Financial information plays an important role in that transition. Reliable bookkeeping, accounting and reporting allow owners to understand what is happening inside the business rather than relying solely on intuition.

At Veritas Accounting Services, we work with businesses and professional firms to provide bookkeeping, accounting, tax support and financial advisory services that help management operate with better information.

The goal is not simply to keep the numbers organized.

It is to give business leaders the information, structure and support they need to lead with confidence and manage with clarity.

GET IN TOUCH

Schedule a FREE Call
How Many Orders Does Your Business Need to Break Even?

A practical framing-shop example shows how to calculate the orders needed to cover costs and test a…

What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…
startup hiring generalists versus specialists

Startup Hiring: Generalists or Specialists? How to Make the Right Choice

Building a startup team is rarely about finding the most impressive person for every position. In the early stages, founders usually work with limited cash, changing priorities, and more responsibilities than the team can comfortably handle.

That makes startup hiring a strategic decision. A generalist may be able to manage several functions and adapt quickly. A specialist may bring the depth required to solve a complex problem that cannot be handled effectively by someone wearing several hats.

The right choice depends on what the business needs now, what it expects to need next, and whether the role requires broad adaptability or deep expertise.

For many founders, the answer may also involve a third option: outsourcing specialized functions until the business is ready for a full-time hire.

Table of Contents

  1. What Is a Generalist?
  2. What Is a Specialist?
  3. Generalists vs. Specialists: What Should Founders Consider?
  4. When a Startup Needs Generalists
  5. When a Specialist Makes More Sense
  6. The Cost Factor
  7. Consider Outsourcing Before Hiring Full-Time
  8. Accounting and Tax as a Practical Example
  9. Hire, Outsource, Automate or Delegate?
  10. How the Right Mix Changes as You Grow
  11. Common Hiring Mistakes
  12. A Practical Decision Framework
  13. FAQ
  14. Conclusion

What Is a Generalist?

A generalist is someone who can contribute across multiple areas rather than being narrowly focused on one technical discipline.

In a startup, that might mean an operations employee who can coordinate vendors, support customers, prepare reports, and help improve internal processes.

Generalists are particularly valuable when priorities change frequently. They can move between responsibilities without requiring a separate hire for every new requirement.

This flexibility can be important when the business is still testing its market, refining its business model, or building its internal processes.

However, flexibility has a limit. A generalist may be capable of handling many tasks but may not have the depth required for highly technical, regulated, or specialized work.

What Is a Specialist?

A specialist brings deep knowledge to a particular function.

Examples include a tax professional, software engineer, cybersecurity expert, financial controller, legal professional, or performance marketing specialist.

Specialists become increasingly valuable when a business reaches a point where mistakes are expensive, complexity is increasing, or a function requires expertise that cannot be developed quickly internally.

The trade-off is cost and flexibility. A specialist may be highly effective in one area but may have less value when priorities change or the workload is inconsistent.

For founders, startup hiring is therefore not simply about choosing between two types of employees. It is about matching capability with the business problem.

Generalists vs. Specialists: What Should Founders Consider?

There is no universal formula, but several factors can guide the decision.

1. Business Stage

An early-stage startup often benefits from people who can wear multiple hats.

A later-stage company may need specialists as departments become more complex.

2. Nature of the Work

If the work involves changing priorities, coordination, and problem-solving across departments, a generalist may be effective.

If it involves technical knowledge, regulatory requirements, or high-risk decisions, a specialist may be more appropriate.

3. Frequency of the Work

A role that requires expertise every day may justify a full-time specialist.

A specialized task needed only a few hours a month may not.

4. Cost of Mistakes

Some errors are inconvenient. Others can result in tax penalties, compliance issues, security problems, lost customers, or financial losses.

The higher the potential cost of an error, the more important appropriate expertise becomes.

When a Startup Needs Generalists

Generalists can be especially useful during the early stages of a company.

They can help founders build processes while learning what the business actually needs.

A strong generalist may:

  • Take ownership of multiple operational tasks
  • Adapt to changing priorities
  • Work across departments
  • Identify process improvements
  • Communicate with different stakeholders
  • Help founders reduce operational bottlenecks

For example, an operations generalist might coordinate customer onboarding, maintain internal documentation, assist with vendor management, and prepare basic management reports.

The value is not that the employee does everything.

The value is that the startup does not need to create a separate position for every responsibility.

This makes startup hiring particularly important during the early stage because founders are often buying flexibility, not just labor.

When a Specialist Makes More Sense

As a startup grows, some functions become too important or complex to manage through broad generalist skills alone.

Consider areas such as:

  • Tax compliance
  • Cybersecurity
  • Software architecture
  • Legal matters
  • Financial controls
  • Regulatory compliance
  • Advanced digital marketing
  • Complex financial reporting

In these areas, experience can prevent expensive mistakes and improve the quality of decisions.

A specialist is particularly valuable when the business has reached sufficient scale to keep the person productive.

That last point is important.

Hiring a specialist simply because the function is important does not necessarily make financial sense. The company must also have enough recurring work to justify the cost.

A startup may need expert knowledge without needing an expert sitting on its payroll eight hours a day.

The Cost Factor

Founders often compare salaries when evaluating a hire.

That is only part of the calculation.

The actual cost of an employee can include:

  • Salary
  • Payroll taxes
  • Benefits
  • Recruitment costs
  • Training
  • Software
  • Equipment
  • Office costs
  • Management time
  • Paid leave

A full-time specialist can therefore represent a substantial fixed commitment.

This does not mean specialists are too expensive. It means the business should compare the expected value of the role with the total cost of maintaining it.

Cash flow is particularly important for startups. A business can be profitable on paper and still struggle if it commits too much cash to fixed costs before revenue becomes predictable.

A disciplined startup hiring strategy should therefore consider total employment cost, not just the advertised salary.

Consider Outsourcing Before Hiring Full-Time

One option that founders sometimes overlook is outsourcing.

Not every business function needs to be performed by an internal employee.

Outsourcing can make sense when a function requires specialized expertise but does not require full-time attention.

Common examples include:

  • Bookkeeping
  • Tax preparation and support
  • Payroll processing
  • Financial reporting
  • IT support
  • Legal services
  • HR administration
  • Digital marketing

The advantage is access to expertise without immediately creating another full-time position.

This can give a startup greater flexibility while it validates demand and builds predictable revenue.

However, outsourcing works best when the external provider has clear responsibilities, defined deliverables, reliable communication, and appropriate controls.

The cheapest provider is not necessarily the best choice.

For functions involving financial records, tax compliance, or sensitive business information, experience, security, responsiveness, and quality should be part of the evaluation.

This is why startup hiring should not be viewed as an automatic answer to every capability gap.

Sometimes the smarter decision is to buy expertise as a service.

Accounting and Tax as a Practical Example

Accounting is a good example of why the generalist-versus-specialist decision needs careful thought.

A founder may be able to record basic transactions or manage simple bookkeeping during the earliest stage.

But as the company grows, financial requirements usually become more complex.

The business may need:

  • Monthly closing procedures
  • Bank and credit card reconciliations
  • Accounts receivable and payable management
  • Cash-flow forecasting
  • Management reporting
  • Budgeting
  • Tax coordination
  • Payroll support
  • Financial controls

At that point, the question is not simply whether to hire an accountant.

The founder should ask what level of financial support is actually required.

A startup may not need a full-time controller or CFO immediately. It may benefit more from an experienced outsourced accounting team that manages the recurring work and provides financial insight as needed.

For example, Veritas Accounting Services can support bookkeeping, accounting, financial reporting, tax support, budgeting, forecasting, and CFO-related requirements without requiring the startup to build an entire finance department internally.

That can allow founders to access experienced professionals while keeping their internal structure lean.

For a founder, the result can be better financial visibility without adding unnecessary fixed overhead.

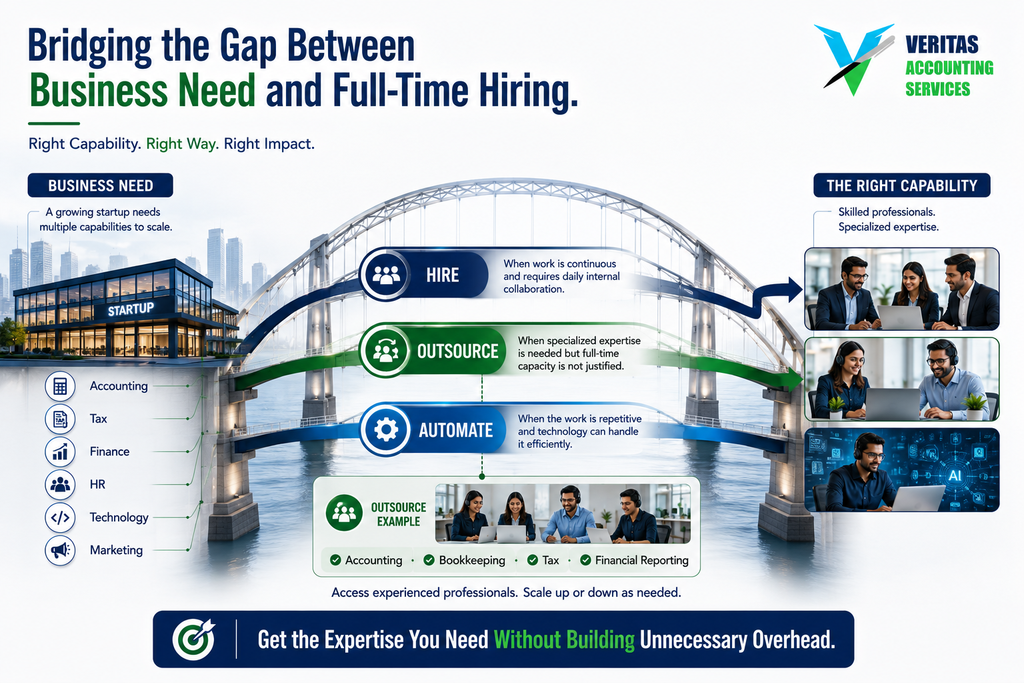
Hire, Outsource, Automate or Delegate?

A useful approach is to evaluate every recurring function through four options.

Hire

Hire internally when the workload is substantial, continuous, strategically important, and requires close daily collaboration.

Outsource

Outsource when specialized expertise is needed but a full-time position is not yet justified.

Automate

Automate repetitive, rule-based processes where technology can deliver reliable results.

Delegate

Delegate tasks that are important but do not require the founder’s direct involvement.

These options are not permanent decisions.

A function can move from outsource to hire as the company grows. Similarly, a manual task can become automated after the process becomes standardized.

This flexible approach makes startup hiring more closely aligned with actual business needs rather than assumptions about what a “proper” company should look like.

How the Right Mix Changes as You Grow

The ideal team structure at $500,000 of annual revenue may look very different from the structure needed at $5 million.

Early-stage businesses often need adaptable people who can work across functions.

As revenue, customers, employees, and operational complexity increase, specialization usually becomes more valuable.

A common progression might look like this:

Early Stage → Generalists + Outsourced Specialists

Growth Stage → Core Internal Team + Functional Specialists

Scaling Stage → Dedicated Departments + Specialized Leadership

This is not a fixed formula.

Some startups will specialize earlier because their industry requires it. Others may remain lean for longer because their operating model is highly standardized.

The important point is to avoid building organizational complexity faster than the business can support.

A good startup hiring plan should evolve with revenue, workload, risk, and management capacity.

Common Hiring Mistakes

Hiring for a Title Instead of a Problem

Do not start with:

“We need a CFO.”

Start with:

“What problem are we trying to solve?”

The second question produces a much better hiring decision.

Hiring Too Early

A position can be strategically important without requiring a full-time employee today.

If the workload is inconsistent, outsourcing may be more practical.

Choosing Only on Salary

The lowest-cost candidate may create higher costs through errors, rework, supervision, or turnover.

Look at the total value of the role.

Expecting One Person to Do Everything

Generalists are valuable, but expecting one employee to perform accounting, tax, HR, technology, sales, and operations at a professional level is unrealistic.

Ignoring Scalability

A role should be evaluated not only for today’s needs but also for how it fits the company’s expected growth.

A Practical Decision Framework

Before making a hiring decision, founders can ask seven questions:

  1. How frequently is this work required?
  2. How specialized is the knowledge?
  3. What happens if the work is done incorrectly?
  4. Can the responsibility be automated?
  5. Can an existing employee handle it with training?
  6. Would outsourcing provide better expertise at the current stage?
  7. At what workload would a full-time hire become financially justified?

The answers can make the decision much clearer.

For example, if a task is highly specialized, performed occasionally, and carries significant risk, outsourcing may be more sensible than hiring.

If the work is continuous, central to operations, and requires daily collaboration, an internal hire may be the better long-term choice.

The strongest startup hiring decisions are usually based on workload, risk, economics, and business strategy rather than simply following what other startups are doing.

FAQ

Should startups hire generalists or specialists first?

There is no single answer. Early-stage companies often benefit from adaptable generalists, while specialized expertise can be brought in through targeted hiring or outsourcing when the need arises.

When should a startup hire a specialist?

A specialist becomes more attractive when the workload is recurring, the function is business-critical, mistakes are costly, and the company can support the role financially.

Is outsourcing better than hiring?

Neither is automatically better. Outsourcing can be effective when a startup needs expertise without enough full-time workload to justify an internal employee.

Should startups outsource accounting?

Many startups can benefit from outsourcing accounting and bookkeeping, particularly when they need reliable financial records, reporting, tax coordination, and cash-flow visibility but do not yet need a full internal finance department.

How should founders decide whom to hire?

Start with the business problem, determine the capability required, estimate the workload and risk, and compare hiring, outsourcing, automation, and delegation before deciding.

Conclusion

Startup hiring should not be driven by titles or trends.

The better question is:

What capability does the business need right now, and what is the most effective way to obtain it?

Generalists can provide flexibility when priorities are changing. Specialists can provide depth when complexity and risk increase. Outsourcing can bridge the gap when a startup needs expertise without enough workload to justify a full-time position.

The smartest approach is often a combination.

Keep critical, high-frequency work close to the business. Use specialists where expertise genuinely matters. Outsource functions that require professional knowledge but do not justify full-time capacity. Automate repetitive work wherever practical.

For finance and accounting, this approach can be particularly valuable. A reliable external team can maintain the books, prepare management reports, support tax requirements, and provide financial insight while founders remain focused on customers, products, and growth.

At Veritas Accounting Services, we help businesses and professional firms access bookkeeping, accounting, tax support, financial reporting, budgeting, forecasting, and CFO-related expertise without automatically building a large internal finance function.

The right team is not necessarily the biggest team.

It is the team with the right capabilities, at the right time, in the right structure.

GET IN TOUCH

Schedule a FREE Call
How Many Orders Does Your Business Need to Break Even?

A practical framing-shop example shows how to calculate the orders needed to cover costs and test a…

What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…
80/20 rule for business owners and resource allocation

The 80/20 Rule for Business Owners: How to Identify Your Most Valuable Customers, Tasks and Decisions

80/20 rule for business owners and resource allocation

Most business owners have the same problem: there is never enough time to do everything.

There are customers to serve, employees to manage, invoices to review, emails to answer, suppliers to negotiate with, financial reports to understand, and decisions waiting for attention.

Yet not every activity contributes equally to business growth.

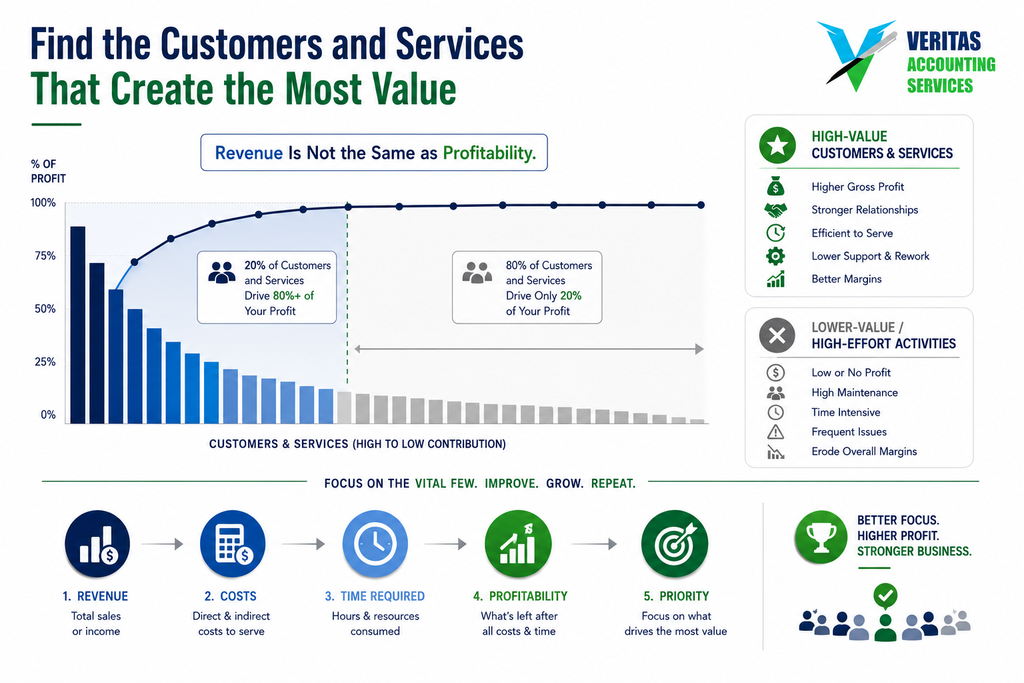
Some customers generate significantly more profit than others. Some services create stronger margins. Some meetings produce important decisions, while others consume time without moving the business forward. Some employees spend their time on activities that have a much greater impact than others.

This is where the 80/20 rule becomes useful.

The principle suggests that a relatively small portion of inputs can often generate a disproportionately large portion of results. The exact ratio does not need to be 80/20 in every business. The important idea is to identify where the greatest value is being created and allocate resources accordingly.

For business owners, this is not simply a productivity technique.

It is a way of thinking about customers, profitability, time, people, cash flow and strategic decisions.

Table of Contents

  1. What Is the 80/20 Rule?
  2. Why It Matters to Business Owners
  3. Find Your Most Valuable Customers
  4. Identify Your Most Profitable Products and Services
  5. Look at Where Your Time Goes
  6. Identify High-Value Business Activities
  7. Use Financial Data to Find the Vital Few
  8. Apply the Principle to Employees and Teams
  9. Focus on Cash Flow and Financial Resources
  10. Avoid the Wrong Use of the 80/20 Rule
  11. How Accounting Professionals Can Helpfgbfgb
  12. A Practical 80/20 Exercise
  13. FAQ
  14. Conclusion

What Is the20 Rule?

The 80/20 rule is commonly associated with economist Vilfredo Pareto, who observed an unequal distribution of wealth and ownership in nineteenth-century Italy.

Over time, the idea became widely used in business and management.

The principle is simple:

A relatively small number of factors may account for a disproportionately large share of results.

For example, a company might discover that:

  • 20% of customers generate 75% of gross profit
  • 15% of products generate 70% of sales
  • 10% of activities consume 60% of management time
  • A small number of recurring problems create most customer complaints

The numbers will differ from business to business.

The value comes from asking a better question:

Which activities, customers, products and decisions create the greatest impact?

Why It Matters to Business Owners

Many businesses try to improve everything at once.

They introduce more products, take on more customers, hold more meetings, add more processes and hire more people.

Growth, however, is not always about doing more.

Sometimes it is about doing more of what works and less of what does not.

The 80/20 rule encourages business owners to look beyond total revenue and examine where the underlying value actually comes from.

A business with $5 million in revenue is not necessarily healthier than one with $3 million.

The more useful questions are:

  • Which customers generate the best margins?
  • Which services are most profitable?
  • Which activities create measurable results?
  • Where is management spending its time?
  • Which expenses produce meaningful returns?
  • Which problems repeatedly consume resources?

The answers can reveal opportunities that are invisible in a traditional top-line revenue report.

Find Your Most Valuable Customers

Revenue alone does not tell you which customers are most valuable.

A customer generating $100,000 in annual revenue may require extensive support, frequent revisions, urgent service, and significant management attention.

Another customer generating $60,000 may be highly profitable, predictable and easy to serve.

That distinction matters.

Use the 80/20 rule to analyze your customer base by:

  • Revenue
  • Gross profit
  • Net contribution
  • Service hours
  • Payment reliability
  • Customer acquisition cost
  • Support requirements
  • Growth potential

Create a customer profitability report and rank customers from highest to lowest contribution.

You may discover that a relatively small group accounts for most of your profitable business.

That information can influence pricing, service levels, account management and future sales strategy.

It may also reveal customers who generate significant revenue but very little actual profit.

Identify Your Most Profitable Products and Services

The same analysis should be applied to what you sell.

Business owners sometimes continue offering products or services simply because customers have historically purchased them.

But revenue does not automatically equal value.

Analyze each offering based on:

Revenue → Direct Cost → Gross Profit → Delivery Time → Management Effort

Suppose a professional services firm offers five services.

One service produces 30% of total revenue but requires extensive customization and employee hours.

Another produces only 15% of revenue but generates much higher margins with a standardized process.

The second service may deserve more attention.

The 80/20 rule can help management identify which offerings deserve investment and which may need repricing, redesign, automation or discontinuation.

Look at Where Your Time Goes

Time is one of the most valuable resources a business owner has.

Yet it is often the least measured.

For two weeks, track how you spend your working hours.

Divide activities into categories such as:

  • Sales
  • Customer meetings
  • Strategy
  • Finance
  • Administration
  • Employee management
  • Problem solving
  • Email
  • Operations
  • Business development

Then ask:

Which activities actually create value?

You may discover that a large portion of your week is consumed by activities that could be delegated, automated or outsourced.

At the same time, the activities that could generate the greatest future growth may receive very little attention.

This is one of the most practical applications of the 80/20 rule.

The objective is not to work fewer hours simply for the sake of working fewer hours.

It is to spend more of those hours on activities where your involvement creates the greatest difference.

Identify High-Value Business Activities

Not every task deserves the same level of attention.

Consider a business owner who spends three hours every Monday reviewing routine bookkeeping transactions but only thirty minutes reviewing monthly profitability.

The time allocation may be backwards.

Routine accounting work is important, but it does not necessarily require the owner’s direct involvement.

A management report showing declining margins, increasing customer acquisition costs or deteriorating cash flow may require much more strategic attention.

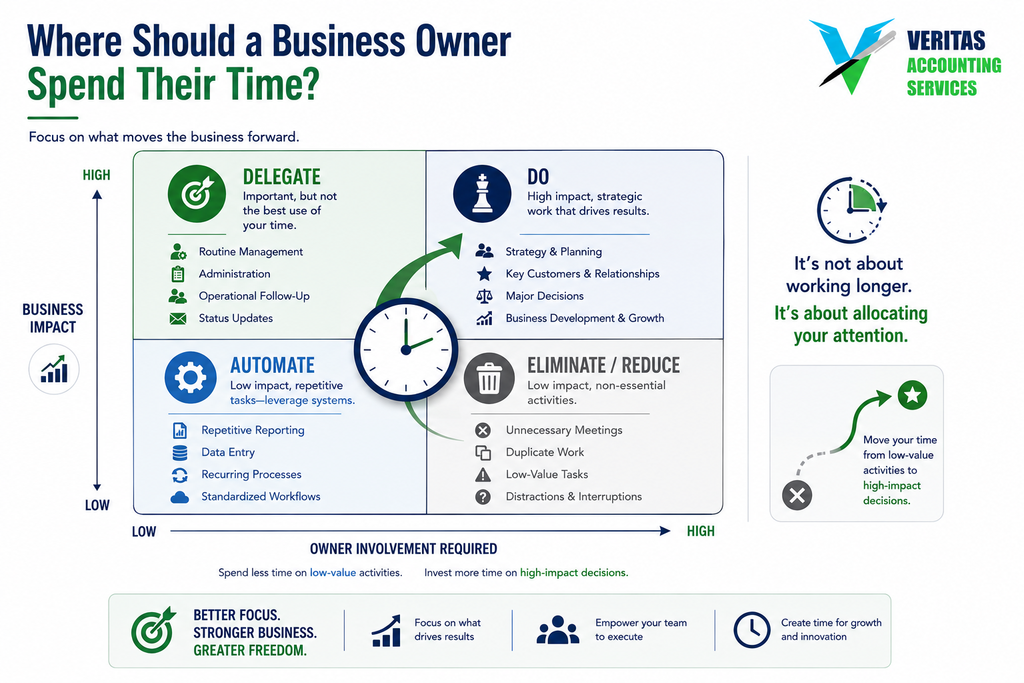
Business owners should therefore separate activities into four categories:

Do

Activities where the owner’s involvement creates significant value.

Delegate

Important work that someone else can perform effectively.

Automate

Repetitive activities that can be handled through technology and established processes.

Eliminate

Activities that add little or no meaningful value.

This simple framework can significantly improve management capacity.

Use Financial Data to Find the Vital Few

Good decisions require good information.

Accounting records are not only useful for tax compliance. They can help management identify where money, time and resources are producing results.

Useful reports include:

  • Customer profitability
  • Product or service profitability
  • Gross margin analysis
  • Expense trends
  • Accounts receivable aging
  • Cash-flow reports
  • Budget versus actual
  • Department performance
  • Revenue by channel
  • Customer concentration

The 80/20 rule becomes far more useful when it is supported by reliable financial data.

For example, a business owner may believe that its largest customer is its most valuable customer.

A profitability analysis may tell a different story.

The customer with the highest revenue may also have the highest service costs, lowest margin and slowest payment cycle.

Without proper financial analysis, management may optimize the wrong thing.

Apply the Principle to Employees and Teams

The goal is not to label certain employees as “valuable” and others as “less valuable.”

Instead, examine where the team’s effort produces the greatest business impact.

Some employees may spend considerable time handling repetitive administrative work.

Others may be involved in customer relationships, process improvement, sales, technical delivery or leadership activities that directly influence growth.

Management should ask:

  • Which responsibilities have the greatest impact?
  • Where are employees spending most of their time?
  • Which activities can be standardized?
  • Where do employees need additional training?
  • Which processes create unnecessary rework?
  • Where could technology or outsourcing free employees for higher-value work?

The objective is to improve the productivity of the entire organization, not simply increase everyone’s workload.

Focus on Cash Flow and Financial Resources

Money should also be allocated according to impact.

Businesses frequently have limited capital and must decide where to invest it.

Possible uses include:

  • Marketing
  • Hiring
  • Technology
  • Equipment
  • Inventory
  • Training
  • Product development
  • Customer acquisition

Instead of spreading resources evenly, compare the expected return from each investment.

For example, if one marketing channel consistently produces profitable customers while another produces large volumes of low-value leads, the company should investigate why.

Likewise, if a particular software system reduces hours of repetitive work every month, its value may be greater than an apparently cheaper alternative.

Financial discipline means understanding not only how much you spend, but what the spending produces.

Avoid the Wrong Use of the 80/20 Rule

The 80/20 rule is a framework for analysis, not a mathematical law that every business must follow exactly.

Do not force every situation into an 80/20 pattern.

There are also activities that may not generate immediate financial returns but remain essential.

Examples include:

  • Compliance
  • Internal controls
  • Cybersecurity
  • Employee development
  • Financial reporting
  • Quality assurance
  • Risk management

A task may represent a small percentage of total activity but still be extremely important.

The right question is therefore not:

“Can we eliminate the other 80%?”

It is:

“Which activities deserve more attention, and which can be handled more efficiently?”

That distinction is critical.

How Accounting Professionals Can Help

Business owners cannot make effective 80/20 decisions if their financial information is incomplete or unreliable.

This is where an experienced accounting team can become more than a bookkeeping provider.

A professional team can help transform accounting data into management information.

For example, an outsourced accounting or CFO team can help prepare:

  • Customer profitability reports
  • Service-line margin analysis
  • Cash-flow forecasts
  • Budget versus actual reports
  • Expense analysis
  • Accounts receivable reports
  • Management dashboards
  • Key performance indicators

This allows business owners to see where resources are actually being consumed and where value is being created.

At Veritas Accounting Services, we support businesses and professional firms with bookkeeping, accounting, financial reporting, tax support, financial projections and CFO-related services.

Our role is not simply to record transactions.

The objective is to provide organized financial information that helps management make better decisions.

For example, if a business owner wants to determine which customers deserve greater attention, the analysis should go beyond revenue.

We can help management consider profitability, collection patterns, service requirements and other relevant financial indicators.

Likewise, when evaluating expenses, management should understand whether spending is supporting growth, protecting the business or simply continuing because it has always existed.

Reliable accounting data gives the 80/20 rule a stronger foundation.

A Practical 80/20 Exercise for Business Owners

Set aside two hours this month and perform a simple analysis.

Step 1: Rank Your Customers

List your top customers by revenue and then by gross profit.

Compare the two rankings.

Step 2: Rank Your Services

Identify which products or services generate the highest margins.

Step 3: Track Your Time

Record your activities for two weeks.

Highlight tasks that require your involvement but could be delegated or outsourced.

Step 4: Review Your Expenses

Identify the largest recurring expenses and determine what business outcome each expense supports.

Step 5: Review Your Decisions

Look at the major decisions made during the last six months.

Which decisions produced measurable results?

Step 6: Take Action

Choose three areas where you can shift more time, money or attention toward activities producing stronger results.

The exercise does not need to produce a perfect 80/20 ratio.

Its purpose is to make the business owner more conscious of where resources are actually creating value.

FAQ

What is the 80/20 rule in business?

The 80/20 rule is the idea that a relatively small proportion of customers, activities, products or resources may generate a disproportionately large share of business results.

How can business owners use the 80/20 rule?

Owners can analyze customers, services, time, employees, expenses and investments to identify where the greatest value is being created and then allocate resources accordingly.

Does the 80/20 rule always mean exactly 80% and 20%?

No. The ratio is a useful principle rather than a fixed mathematical requirement. The actual distribution may be 70/30, 90/10 or another pattern.

Can accounting data help identify the most valuable customers?

Yes. Revenue, gross margin, service costs, payment behavior and customer-level profitability can provide a much clearer picture of customer value than revenue alone.

How can an outsourced accounting team support this approach?

An experienced accounting team can organize financial data and prepare profitability reports, management reports, cash-flow forecasts and other analysis that helps business owners identify where resources are creating the greatest impact.

Conclusion

Business growth does not always require doing more.

Sometimes it requires identifying what matters most and allocating resources accordingly.

The 80/20 rule gives business owners a practical framework for examining customers, services, time, employees, expenses and investments.

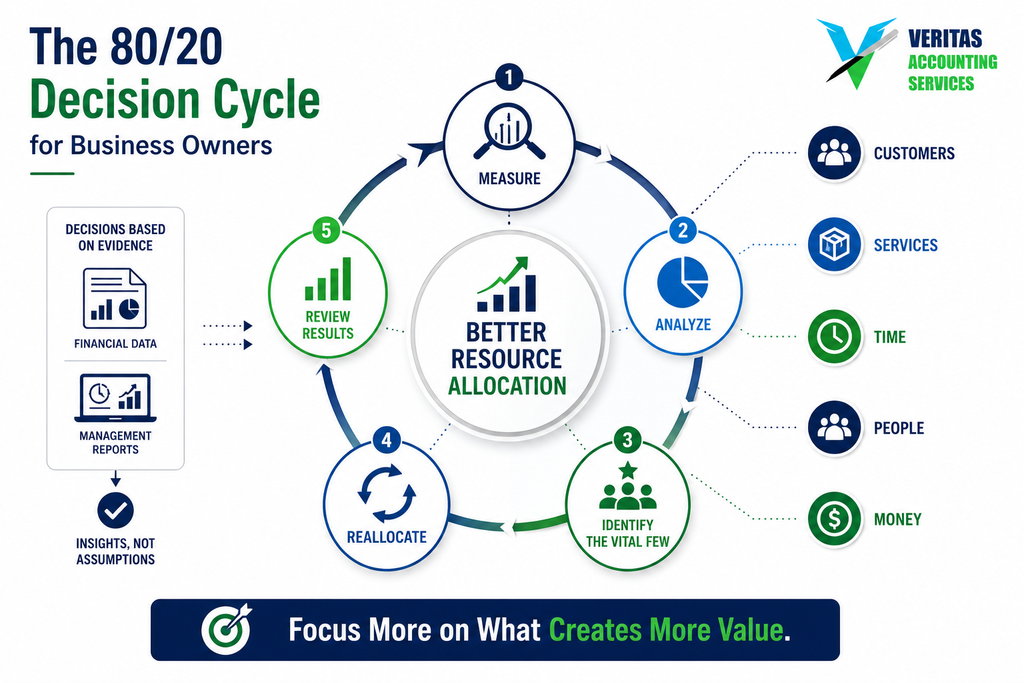
The most important step is to move from assumptions to evidence.

Instead of assuming that the biggest customer is the most profitable, measure profitability.

Instead of assuming that a busy employee is productive, examine outcomes.

Instead of reviewing every expense equally, understand which investments contribute to growth, efficiency or risk reduction.

And instead of spending management time on every operational detail, identify the decisions where leadership involvement creates the greatest value.

At Veritas Accounting Services, we believe accounting should provide more than historical numbers. Well-organized financial information can help business owners understand profitability, cash flow, resource allocation and business performance.

The goal is simple: focus more of your time, money and attention on the activities that genuinely move your business forward.

That is where the real value of the 80/20 rule lies.

GET IN TOUCH

Schedule a FREE Call
How Many Orders Does Your Business Need to Break Even?

A practical framing-shop example shows how to calculate the orders needed to cover costs and test a…

What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Connect on our Socials!

compliance calendar

Business Compliance Calendar: How to Organize Your Tax, Payroll and Filing Deadlines

Running a business involves more than generating revenue and managing customers. Every company has recurring obligations that must be completed on time—tax filings, payroll reports, sales tax returns, annual registrations, licenses, information returns, and other regulatory requirements.

The challenge is that these obligations rarely follow one simple schedule.

Some are monthly. Others are quarterly or annual. Certain requirements depend on the state where the business operates, the type of entity, the number of employees, or the nature of its transactions.

A well-designed compliance calendar turns these scattered obligations into a structured management process. Instead of relying on memory or reacting to approaching deadlines, business leaders can see what needs to be done, who is responsible, and when each task must be completed.

For growing businesses, this is particularly important. As operations expand across states, entities, employees, and tax jurisdictions, compliance becomes more complex.

The goal is not simply to remember deadlines. It is to create a system that makes compliance predictable, accountable, and manageable.

Table of Contents

  1. Why Every Business Needs a Compliance Calendar
  2. What Should Be Included?
  3. Organizing Tax Deadlines
  4. Managing Payroll and Employment Tax Obligations
  5. Tracking Sales Tax and Other Indirect Taxes
  6. Annual Reports, Licenses and Registrations
  7. Organizing Information Returns
  8. Assigning Responsibility for Every Deadline
  9. Building an Effective Reminder System
  10. Common Compliance Calendar Mistakes
  11. How Accounting Professionals Can Help
  12. FAQ
  13. Conclusion

Why Every Business Needs a Compliance Calendar

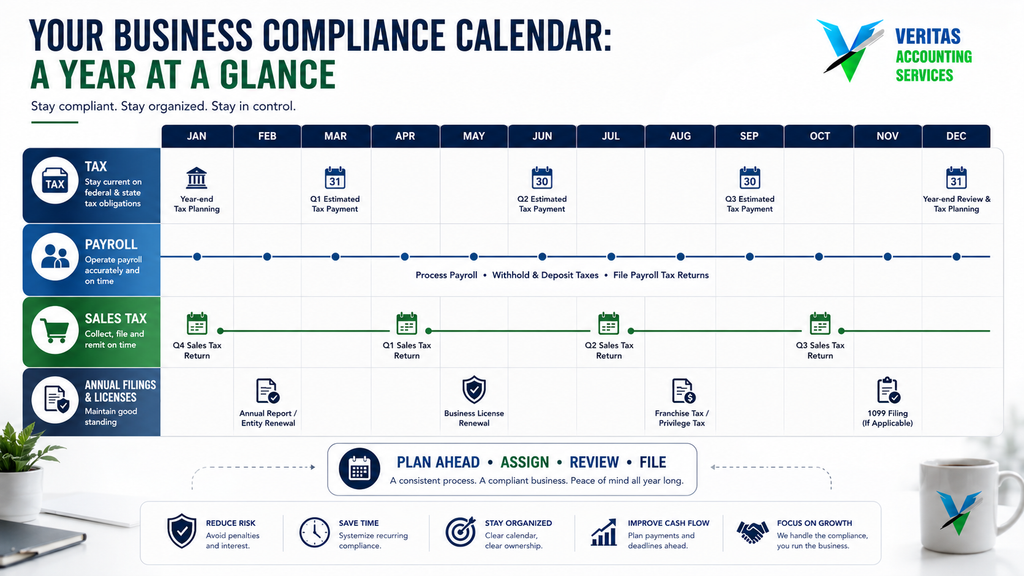
A compliance calendar is essentially a central schedule containing the recurring filings, payments, renewals, reports, and other obligations applicable to a business.

Without one, businesses often manage deadlines through disconnected emails, spreadsheets, accounting software reminders, and individual employees’ calendars.

That approach can work when a company is very small.

It becomes risky as the business grows.

A structured compliance calendar helps management answer five basic questions:

  • What needs to be filed or paid?
  • When is it due?
  • Who is responsible?
  • Which documents or information are required?
  • Has the obligation been completed and reviewed?

This creates accountability.

It also reduces the risk of a common problem: everyone assumes someone else is handling the filing.

What Should Be Included?

A good compliance calendar should be customized to the company’s actual obligations.

For a U.S. business, this may include federal, state, and local requirements.

Depending on the business, consider including:

  • Federal income tax filings
  • Estimated tax payments
  • State income or franchise tax filings
  • Payroll tax filings
  • Sales and use tax returns
  • Annual reports
  • Business license renewals
  • Information returns
  • Property tax obligations
  • Foreign-related information reporting
  • Registered-agent requirements
  • Insurance renewals
  • Employee-related filings
  • Financial reporting deadlines

Not every business will have every obligation.

The objective is to identify the requirements that actually apply and place them into one controlled system.

A compliance calendar should also record the frequency of each obligation. Categorizing tasks as monthly, quarterly, annual, or event-based makes the schedule easier to manage.

Organizing Tax Deadlines

Tax obligations are usually among the most important items on the schedule.

However, businesses should avoid treating “tax filing” as one single category.

Depending on the entity and circumstances, the calendar may need to distinguish between:

  • Federal income tax
  • State income or franchise taxes
  • Estimated tax payments
  • Sales and use taxes
  • Payroll taxes
  • Excise taxes
  • Information reporting
  • Local taxes

A business operating in multiple states may have several different filing calendars.

For example, a company could have employees in one state, customers creating sales tax obligations in another, and an entity registration in a third.

That means the finance team should maintain a jurisdiction-by-jurisdiction view rather than relying on one generic tax deadline list.

The calendar should also identify whether each obligation requires a return, payment, or both.

This distinction matters because filing and payment requirements do not always operate in exactly the same way.

Managing Payroll and Employment Tax Obligations

Payroll compliance deserves its own section because payroll mistakes can affect both the business and its employees.

Depending on the business and jurisdiction, responsibilities may include:

  • Federal payroll tax deposits
  • Federal payroll tax returns
  • State payroll tax filings
  • State unemployment filings
  • Local payroll requirements
  • Employee wage reporting
  • Year-end employee forms
  • New-hire reporting

The appropriate frequency can depend on factors such as payroll size, tax liability, jurisdiction, and employer status.

A compliance calendar should therefore identify the exact requirement rather than simply creating a generic “payroll filing” reminder.

It is also useful to schedule internal deadlines before the official due date.

For example, if a filing is due on a particular date, the business might require payroll information to be reviewed several business days earlier.

That buffer gives the accounting team time to identify missing information or resolve discrepancies.

Tracking Sales Tax and Other Indirect Taxes

Sales tax can become complicated quickly when a business sells across multiple jurisdictions.

Requirements can depend on factors such as:

  • Location of customers
  • Nexus
  • Product or service type
  • Registration status
  • Filing frequency
  • State and local requirements

A growing e-commerce business, for example, may have customers across many states while using several sales channels.

Its compliance calendar should identify the jurisdictions where registration and filing obligations exist and track each requirement separately.

The same principle applies to other indirect taxes.

Instead of one row labeled “sales tax,” create a clear record showing the jurisdiction, filing frequency, responsible person, filing requirement, payment requirement, and completion status.

Annual Reports, Licenses and Registrations

Tax filings are not the only deadlines businesses need to manage.

Companies may also have annual or periodic requirements involving:

  • Secretary of State filings
  • Business registrations
  • Professional licenses
  • Local business licenses
  • Registered-agent information
  • Foreign qualifications
  • Industry-specific registrations

These deadlines are particularly easy to overlook because they may occur only once a year.

A compliance calendar should therefore include annual renewals well in advance.

The business should also record the consequences of missing a requirement.

Some missed filings may result in penalties or late fees. Others can affect a company’s good standing or ability to operate.

Organizing Information Returns

Information reporting is another area that should be considered separately.

Depending on the business, information returns may relate to:

  • Payments to independent contractors
  • Payments to certain vendors
  • Interest
  • Dividends
  • Foreign transactions
  • Employee compensation
  • Other reportable payments

The finance team should identify which forms apply to the business and establish internal deadlines for collecting the necessary information.

This is where organized bookkeeping becomes extremely valuable.

If vendor information, payment classifications, and supporting documentation are incomplete throughout the year, preparing information returns at the last minute becomes much more difficult.

compliance calendar for business tax payroll and filing deadlines

Assigning Responsibility for Every Deadline

Creating a compliance calendar is only the first step.

Someone must own each task.

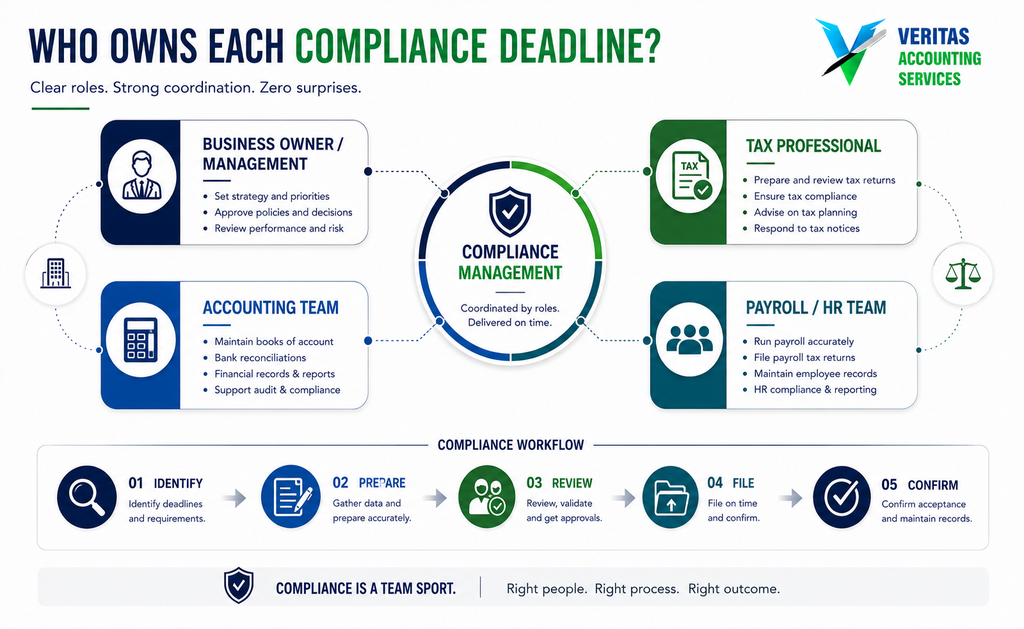
For every obligation, identify:

Task → Jurisdiction → Due Date → Responsible Person → Reviewer → Status

For example:

Compliance ItemFrequencyOwnerReviewerStatus
Payroll filingMonthly/QuarterlyPayroll TeamFinance ManagerPending
Sales taxMonthly/QuarterlyAccounting TeamSenior AccountantComplete
Annual reportAnnualCorporate AdminManagementUpcoming
Income taxAnnual/EstimatedTax ProfessionalManagementPending

The exact responsibilities will vary by business.

The important principle is that every deadline should have a clearly identified owner.

A backup person should also be identified for critical obligations.

This prevents compliance from becoming dependent on one employee.

Building an Effective Reminder System

A good compliance calendar should not simply show due dates.

It should create a workflow.

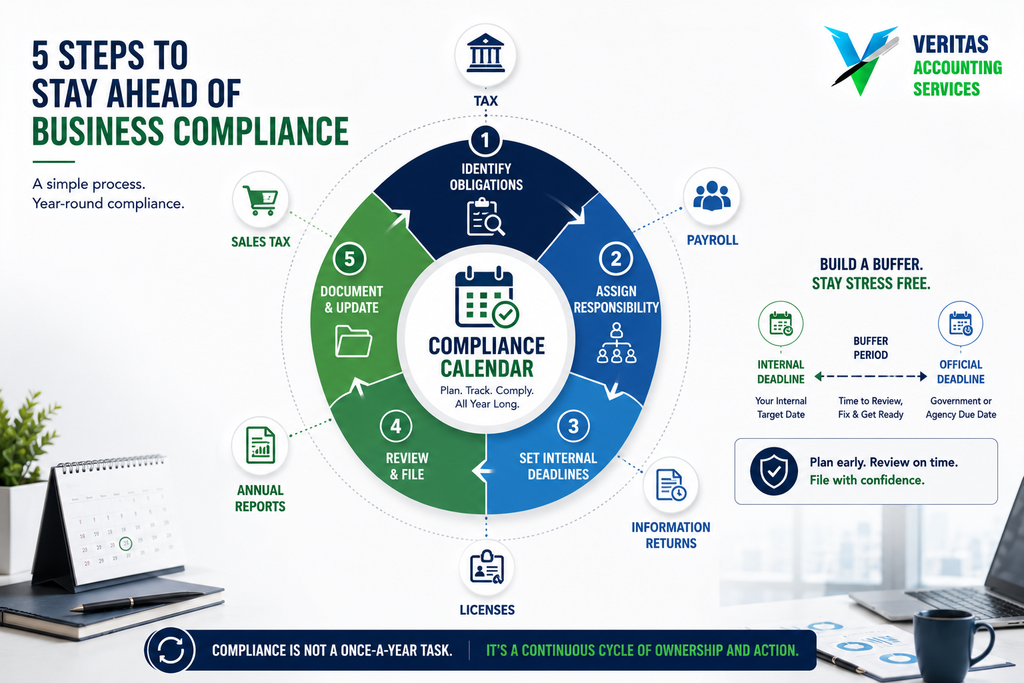
For each task, consider having reminders at several stages:

30 Days Before

Confirm that the requirement still applies and identify the documents needed.

15 Days Before

Collect supporting information and begin preparation.

5–7 Days Before

Complete review and resolve outstanding questions.

Due Date

Confirm filing and payment.

After Filing

Save confirmation, payment evidence, and final documents.

This approach creates an audit trail and makes it easier to prove that the obligation was completed.

Digital calendar tools, accounting software, workflow systems, and shared spreadsheets can all be used. The technology matters less than having a consistent process.

Common Compliance Calendar Mistakes

Even businesses that maintain a calendar can make mistakes.

Mistake 1: Using a Generic Deadline List

A generic tax calendar does not automatically reflect the company’s actual obligations.

The calendar should be customized by entity, jurisdiction, tax type, and business activity.

Mistake 2: Tracking Filing but Not Payment

A business may submit a return but forget that a separate payment is required.

Track both.

Mistake 3: No Internal Deadline

Using the government deadline as the team’s internal deadline leaves little room for correction.

Build a buffer.

Mistake 4: No Review Process

A preparer should not necessarily be the only person responsible for reviewing important filings.

Define appropriate review procedures.

Mistake 5: Not Updating the Calendar

Business circumstances change.

New employees, additional states, new entities, acquisitions, new products, or changes in business structure can create new obligations.

The calendar should be reviewed whenever the business changes materially.

How Accounting Professionals Can Help

Managing compliance becomes more difficult when business owners are responsible for both running the company and monitoring every financial obligation.

This is where experienced accounting and tax professionals can provide significant value.

A professional team can help businesses:

  • Identify recurring accounting requirements
  • Organize financial records
  • Track filing deadlines
  • Prepare supporting schedules
  • Coordinate tax filings
  • Reconcile accounts before filing
  • Maintain documentation
  • Monitor outstanding obligations
  • Prepare management reports
  • Coordinate with tax professionals
  • Maintain a centralized compliance calendar

For international businesses and companies operating across multiple jurisdictions, professional support can be particularly useful because requirements may vary between federal, state, and local authorities.

Outsourcing does not mean giving up management control.

A well-structured arrangement can actually improve control because responsibilities, deadlines, documentation, and review procedures are clearly defined.

For example, an outsourced accounting team can maintain the bookkeeping and supporting records while the company’s tax professional reviews and files the appropriate returns.

This creates a clear division of responsibility.

compliance calendar for business tax payroll and filing deadlines

FAQ

What is a compliance calendar?

A compliance calendar is a centralized schedule that tracks a business’s tax, payroll, regulatory, licensing, reporting, and other recurring obligations.

How often should a compliance calendar be reviewed?

It should be reviewed regularly and whenever the business experiences significant changes, such as entering a new state, hiring employees, forming an entity, or changing its operations.

Should payroll deadlines be included?

Yes. Payroll tax deposits, payroll returns, unemployment filings, employee reporting, and year-end payroll forms should be included when applicable.

Should a small business have a compliance calendar?

Yes. A smaller business may have fewer obligations, but missed deadlines can still result in penalties, additional costs, or administrative problems. Starting with a simple calendar makes it easier to scale the process.

Can an outsourced accounting firm maintain a compliance calendar?

Yes. An experienced accounting team can maintain deadlines, collect supporting information, prepare accounting records, coordinate with tax professionals, and track completion while management retains oversight.

Conclusion

Compliance should not be managed as a collection of isolated deadlines.

It should be treated as a business process.

A well-maintained compliance calendar gives business leaders visibility into upcoming obligations, assigns responsibility, creates internal review points, and reduces dependence on memory.

The process becomes even more important as a business expands into new states, hires employees, adds entities, or increases transaction volume.

The most effective approach is to identify every applicable obligation, assign an owner, establish internal deadlines, maintain supporting documentation, and review the schedule regularly.

Professional accounting and tax teams can also play an important role by maintaining organized financial records, coordinating recurring requirements, and helping management stay ahead of upcoming obligations.

At Veritas Accounting Services, we support businesses and professional firms with bookkeeping, accounting, tax support, financial reporting, and CFO-related services. Our role is not simply to record transactions. We help clients build organized financial processes that give management better visibility and control.

A missed deadline can create unnecessary cost and stress.

A well-managed compliance calendar turns those deadlines into a predictable process.

Know what is due. Know when it is due. Know who owns it. And review it before the deadline—not after it.

GET IN TOUCH

Schedule a FREE Call
How Many Orders Does Your Business Need to Break Even?

A practical framing-shop example shows how to calculate the orders needed to cover costs and test a…

What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Connect on our Socials!

disaster recovery plan

Disaster Recovery for Businesses: How to Prepare for the Unexpected

A disaster does not have to destroy a building to disrupt a business. A cyberattack, ransomware incident, prolonged power outage, critical software failure, severe weather event, supplier disruption, or sudden loss of key personnel can interrupt operations just as effectively.

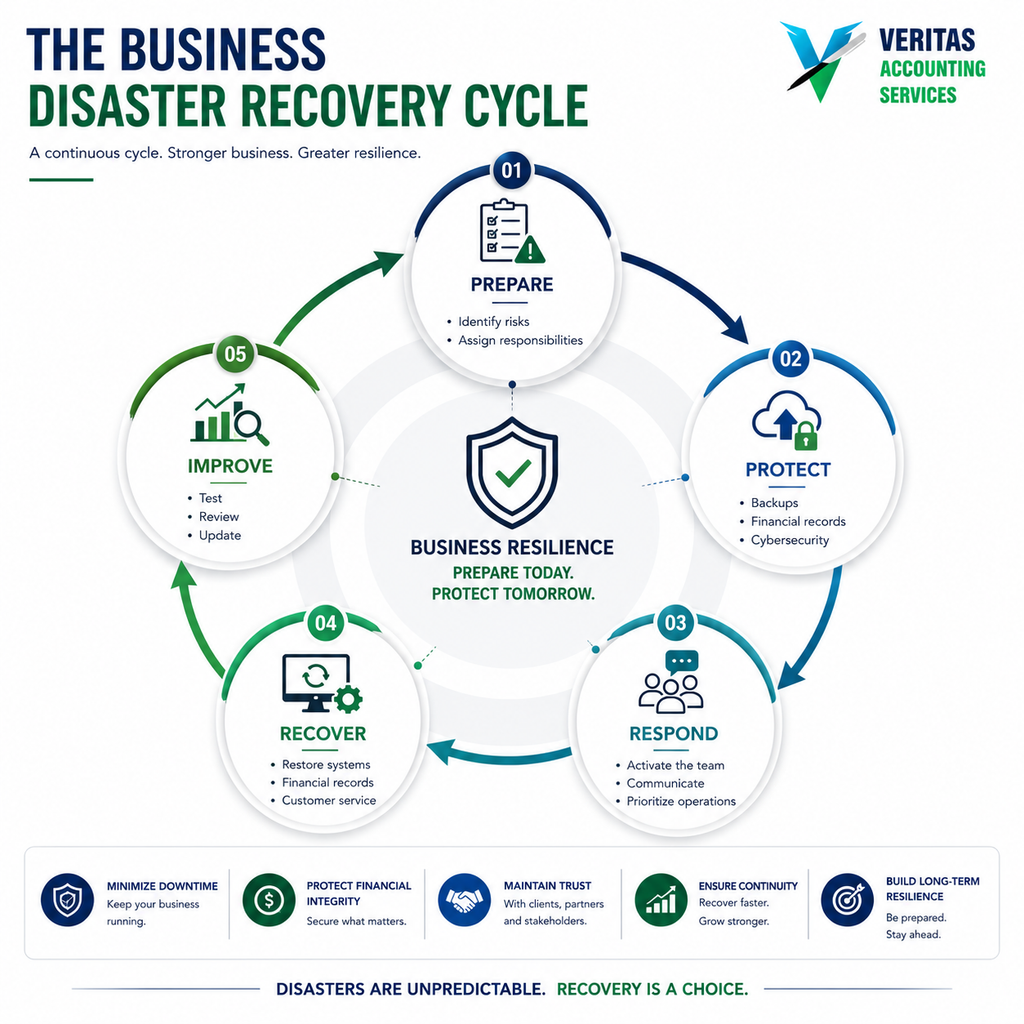
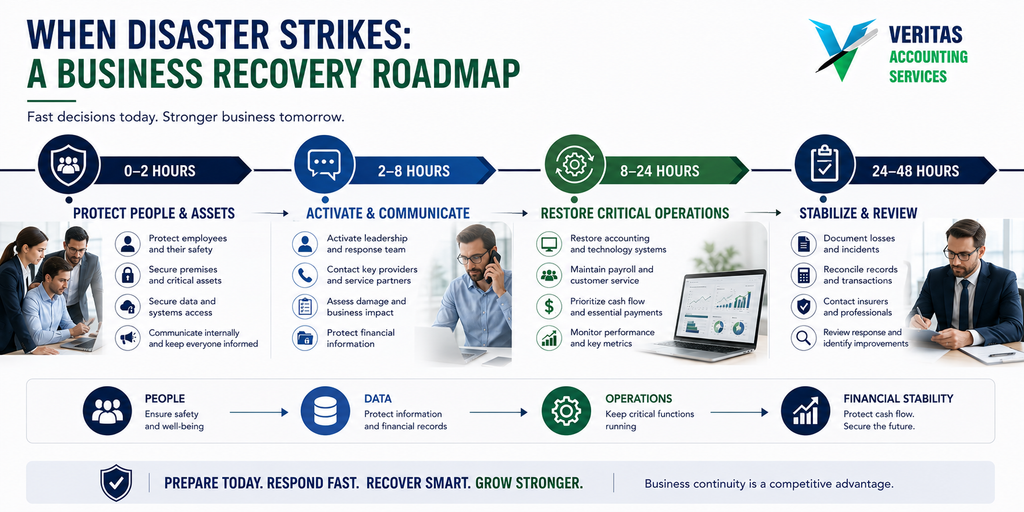
A well-designed disaster recovery plan helps a business determine what happens when normal operations are no longer possible. It identifies critical systems, protects important information, establishes responsibilities, and provides a practical path toward restoring operations.

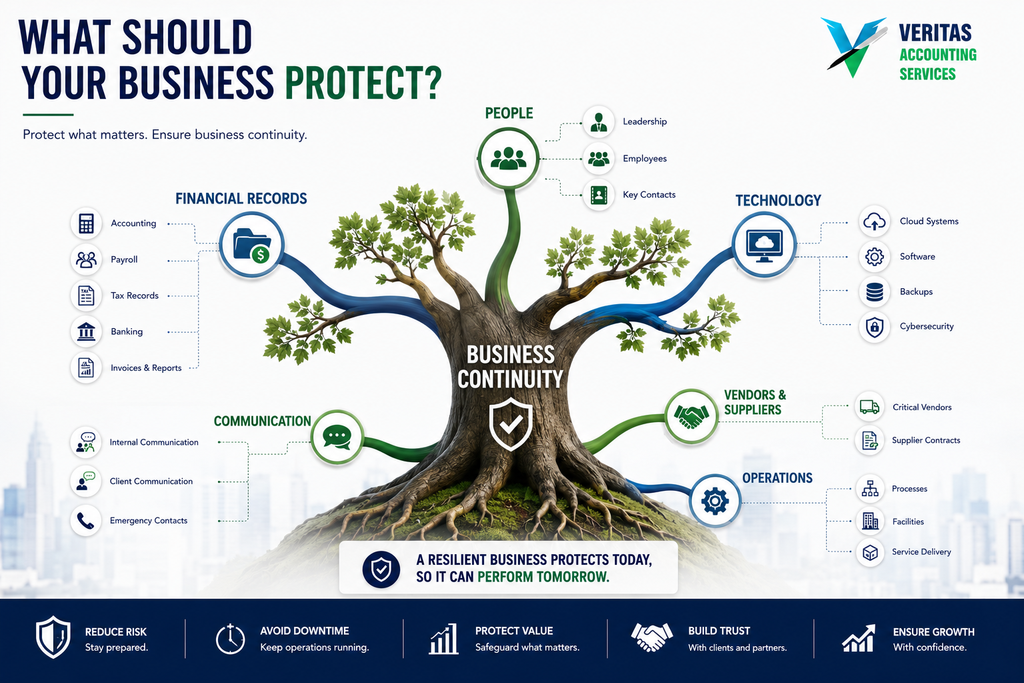
For business leaders, preparation is not simply an IT responsibility. Financial records, payroll information, customer data, tax documents, bank access, accounting systems, invoices, contracts, and management reports are all part of the business’s ability to recover.

The objective is not to predict every possible disaster. It is to make sure the company can continue functioning when something unexpected happens.

Table of Contents

  1. What Is a Disaster Recovery Plan?
  2. Why Businesses Should Prepare Before a Crisis
  3. Identify the Risks That Matter Most
  4. Protect Financial and Business Records
  5. Build a Reliable Backup Strategy
  6. Protect Accounting and Tax Information
  7. Plan for People and Communication
  8. Prepare for Cybersecurity Incidents
  9. Consider Vendors and Third Parties
  10. Establish Financial Continuity
  11. Test and Update the Plan
  12. How Professional Accounting Teams Can Help
  13. FAQ
  14. Conclusion

What Is a Disaster Recovery Plan?

A disaster recovery plan is a documented framework explaining how a business will respond to a serious disruption and restore critical operations.

It should answer practical questions such as:

  • What are our most important business processes?
  • Which systems must be restored first?
  • Where are our critical records stored?
  • Who is responsible for each recovery activity?
  • How will employees communicate during an emergency?
  • How will customers and suppliers be informed?
  • How will we access cash and banking services?
  • How will accounting and payroll continue?
  • What happens if our primary office or technology becomes unavailable?

A disaster recovery plan should be practical rather than theoretical. Employees should be able to understand it and use it under pressure.

The U.S. Small Business Administration recommends that businesses assess their risks, create a tailored response plan, and practice the plan with employees.

Why Businesses Should Prepare Before a Crisis

The worst time to decide how your business will recover is after the disruption has already occurred.

A disaster recovery plan gives management the opportunity to make important decisions while there is still time to think clearly.

Without preparation, different people may make different assumptions about what should happen. Employees may not know who has authority to approve emergency payments. Management may not know where backup records are stored. Customers may receive conflicting information.

Preparation creates structure.

The IRS specifically encourages businesses to safeguard financial and tax records, back up computer data systems, establish communication procedures, and review emergency plans regularly.

Preparation also protects management time. Instead of inventing a response during a crisis, leadership can follow a framework that has already been discussed and tested.

Identify the Risks That Matter Most

Not every business faces the same threats.

A retailer may be highly exposed to physical property damage and supply-chain interruptions. A professional services firm may be more dependent on cloud systems, internet access, and employee availability. An e-commerce company may face significant risks if its payment platform, website, or fulfillment partner becomes unavailable.

Start by identifying the events that could materially interrupt operations.

Consider:

  • Natural disasters
  • Fire or building damage
  • Cyberattacks and ransomware
  • Extended power or internet outages
  • Cloud or software failures
  • Loss of critical employees
  • Supplier failure
  • Banking or payment disruptions
  • Theft or physical loss of records
  • Major equipment failure

The goal is not to create a hundred-page document covering every theoretical scenario.

Focus on realistic risks and the consequences they could create.

Protect Financial and Business Records

Financial information is one of the most important assets to protect.

A business may need access to:

  • Bank statements
  • Accounting records
  • Invoices
  • Customer balances
  • Vendor records
  • Payroll information
  • Tax returns
  • Sales tax records
  • Contracts
  • Insurance documents
  • Fixed-asset records
  • Financial statements
  • Budgets and forecasts

A disaster recovery plan should identify where these records are maintained, who can access them, and how they can be recovered if the primary system becomes unavailable.

The IRS recommends paperless recordkeeping, electronic backups, and storing duplicate records in a separate location.

This is particularly important for businesses that depend heavily on accounting software and cloud-based applications.

Cloud software can reduce certain risks, but simply using cloud software does not mean every recovery risk has disappeared. Businesses still need appropriate access controls, backups, authentication procedures, and documented recovery processes.

Build a Reliable Backup Strategy

A backup is useful only if the business can actually restore the information when required.

Companies should identify their critical data and establish a regular backup process.

Consider:

What needs to be backed up?

Identify essential accounting, customer, operational, HR, tax, and management information.

How frequently should it be backed up?

Critical information may require more frequent protection than less important records.

Where should backups be stored?

Avoid relying entirely on a single physical location or device.

Who can restore the information?

The recovery process should not depend on one employee who may be unavailable.

Has the backup actually been tested?

A backup that has never been restored is an assumption, not a proven recovery solution.

Testing should be part of the disaster recovery plan because recovery procedures can fail even when backups exist.

Protect Accounting and Tax Information

Accounting and tax records deserve special attention because losing them can affect more than day-to-day operations.

A business may need historical financial information for:

  • Tax filings
  • Insurance claims
  • Financing
  • Audit support
  • Customer or vendor disputes
  • Government requirements
  • Management analysis
  • Reconstructing financial records after a loss

The IRS notes that businesses may need to reconstruct records after a disaster to support tax purposes, insurance reimbursement, or applications for assistance.

A disaster recovery plan should therefore include a financial records section.

That section can identify where accounting files are maintained, how bank records are accessed, who has administrative permissions, how payroll information is recovered, and who is responsible for communicating with accountants and tax professionals.

Plan for People and Communication

Technology is only one part of recovery.

People need to know what to do.

Employees should understand:

  • Who makes emergency decisions
  • Who communicates with customers
  • Who communicates with suppliers
  • Who handles payroll
  • Who contacts banks and insurers
  • Who manages technology recovery
  • Where emergency procedures are stored
  • How employees will receive updates

A communication tree can be useful.

For example:

Leadership → Department Managers → Employees → Customers/Suppliers

The business should also identify alternative communication methods if its primary email, phone, office, or internet connection becomes unavailable.

A disaster recovery plan should be accessible when normal systems are unavailable. Keeping the only copy of the plan inside the system that may be affected by the disaster defeats the purpose.

Prepare for Cybersecurity Incidents

Cyber incidents deserve specific attention because the business may have no physical warning before losing access to systems or data.

A ransomware attack, compromised account, phishing incident, or stolen credentials can interrupt operations quickly.

Businesses should consider:

  • Multi-factor authentication
  • Strong password management
  • Restricted administrative access
  • Employee security training
  • Regular software updates
  • Endpoint protection
  • Secure backups
  • Incident-response procedures
  • Vendor access controls

The recovery process should also identify who has authority to isolate systems, contact technology providers, communicate with employees, and involve appropriate legal or cybersecurity professionals.

The purpose of a disaster recovery plan is not to replace cybersecurity. It is to ensure the organization has a structured response when preventive controls are unsuccessful.

Consider Vendors and Third Parties

Many businesses cannot operate without external providers.

A company may depend on:

  • Banks
  • Payment processors
  • Payroll providers
  • Cloud accounting platforms
  • Shipping companies
  • IT providers
  • Tax professionals
  • Suppliers
  • Outsourced accounting teams
  • Customer relationship platforms

What happens if one of these providers becomes unavailable?

Businesses should identify critical vendors and understand alternative arrangements where practical.

For example, if payroll is processed externally, management should know how payroll information can be accessed and what happens if the provider experiences an outage.

Supplier concentration should also be reviewed.

If one supplier provides a critical product or service, consider whether an alternative supplier exists and how quickly the relationship could be activated.

Establish Financial Continuity

A business can survive many operational disruptions if it maintains sufficient financial flexibility.

Cash flow therefore belongs in the recovery conversation.

Management should understand:

  • Available cash
  • Bank relationships
  • Credit facilities
  • Upcoming payroll
  • Major vendor obligations
  • Customer receivables
  • Insurance coverage
  • Recurring expenses
  • Emergency spending authority

A disaster recovery plan should identify who can approve emergency payments and how the company will continue accessing banking services if normal office operations are disrupted.

Financial forecasting can also help management understand how long the business can continue operating under different disruption scenarios.

For example, leadership could model what happens if revenue falls by 30% for three months or if a major facility becomes unavailable for six weeks.

The objective is not to predict the future precisely.

It is to understand the company’s financial resilience.

Test and Update the Plan

A document sitting in a folder is not enough.

The business needs to test whether its procedures actually work.

The SBA recommends practicing preparedness plans with staff, while the IRS advises businesses to review emergency plans regularly and update them as circumstances change.

Testing can include simple exercises:

Scenario: The accounting system is unavailable.

Ask:

  • Who contacts the provider?
  • Where are recent financial reports stored?
  • How will invoices be issued?
  • How will payments be approved?
  • How will payroll be processed?
  • Who communicates with customers?

Another scenario could involve the loss of the company office.

Ask:

  • Where will employees work?
  • How will they access systems?
  • How will management communicate?
  • Where will physical records be retrieved?
  • Who has authority to activate alternative arrangements?

After every test, document what worked and what failed.

That feedback should be incorporated into the next version of the plan.

How Professional Accounting Teams Can Help

Financial continuity is often overlooked when businesses create emergency plans.

This is where an experienced accounting team can provide practical support.

An outsourced accounting partner can help maintain organized financial records, establish consistent bookkeeping procedures, perform regular reconciliations, prepare financial reports, and ensure that important information is not dependent on one individual.

For businesses using an outsourced accounting model, the external team can also provide continuity when an internal employee is unavailable.

Services may include:

  • Bookkeeping
  • Bank reconciliation
  • Accounts payable
  • Accounts receivable
  • Month-end closing
  • Financial reporting
  • Tax support
  • Cash-flow forecasting
  • Management reporting
  • Financial record cleanup

At Veritas Accounting Services, we work with businesses and professional firms to provide outsourced accounting, bookkeeping, tax support, financial reporting, and CFO-related services. A structured external team can become one part of a broader business continuity strategy by helping maintain reliable financial information before, during, and after a disruption.

The key is to establish responsibilities in advance.

A disaster recovery plan should clearly identify who maintains financial records, who has access to important information, who communicates with the external accounting team, and how financial reporting will continue during an interruption.

A Practical Recovery Checklist

Business leaders can use the following checklist as a starting point:

Before a Disaster

  • Identify critical business processes
  • Assess major risks
  • Back up important records
  • Protect financial and tax documents
  • Document key contacts
  • Establish communication procedures
  • Review insurance coverage
  • Define emergency spending authority
  • Identify alternative suppliers
  • Test recovery procedures

During a Disaster

  • Protect employees first
  • Activate the recovery team
  • Establish reliable communication
  • Protect financial information
  • Prioritize critical operations
  • Contact key vendors and service providers
  • Monitor cash flow
  • Document losses and expenses

After a Disaster

  • Restore critical systems
  • Reconcile financial records
  • Reconstruct missing documents
  • Document business losses
  • Communicate with customers
  • Review insurance and assistance options
  • Identify weaknesses in the recovery process
  • Update the plan based on lessons learned

FAQ

What is the purpose of a disaster recovery plan?

The purpose is to help a business respond to a disruption, protect critical information, restore important operations, and reduce the financial and operational impact of an unexpected event.

How often should a disaster recovery plan be updated?

Businesses should review it regularly and whenever there are significant changes to employees, technology, locations, vendors, systems, or business operations. The IRS specifically recommends reviewing emergency plans annually.

Should financial records be included?

Absolutely. Accounting, payroll, tax, banking, customer, vendor, and financial reporting information can be critical to continuing operations and documenting losses.

Can an outsourced accounting firm help with recovery?

Yes. An experienced accounting team can help maintain organized financial records, reporting processes, reconciliations, and access to important financial information, making the recovery process more manageable.

Is a disaster recovery plan only for large businesses?

No. Smaller businesses may be particularly vulnerable because they often depend on a small number of employees, systems, suppliers, and customers. A practical plan can be scaled according to the size and complexity of the business.

Conclusion

Unexpected events are part of doing business. The difference between a temporary disruption and a prolonged crisis often depends on how prepared the organization was before the event occurred.

A disaster recovery plan does not need to be complicated. It needs to be realistic, accessible, tested, and connected to the way the business actually operates.

Business leaders should think beyond physical emergencies. Cybersecurity incidents, technology failures, employee loss, supplier disruptions, and financial-system interruptions can all affect business continuity.

Financial information deserves particular attention. If management cannot access accounting records, banking information, payroll data, invoices, tax documents, or financial reports, recovering operations can become considerably more difficult.

The IRS recommends safeguarding financial and tax records, maintaining backups, and planning for continuity of operations.

A strong disaster recovery plan gives management something valuable during an uncertain situation: clarity.

Know what matters. Protect it. Assign responsibility. Test the process. Review it regularly.

And do not wait for a disaster to discover that an important process depended on one person, one computer, one supplier, or one undocumented procedure.

At Veritas Accounting Services, we help businesses maintain organized bookkeeping, accounting, tax support, financial reporting, and CFO-related processes so that financial information remains structured and accessible when management needs it most.

Business continuity is not simply about recovering technology.

It is about recovering the business.

GET IN TOUCH

Schedule a FREE Call
How Many Orders Does Your Business Need to Break Even?

A practical framing-shop example shows how to calculate the orders needed to cover costs and test a…

What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Connect on our Socials!

business outsourcing strategy for growing businesses

Build In-House or Outsource? How to Choose the Right Business Model

As a business grows, management eventually faces an important question: should a particular function be handled by an internal employee or entrusted to an experienced external team?

The answer is rarely as simple as comparing an employee’s salary with an outsourcing fee.

A better decision considers expertise, total cost, flexibility, quality, management time, scalability, risk, and the strategic importance of the function.

This is why business outsourcing has become an important consideration for growing companies. Businesses can access experienced professionals without necessarily building a complete department internally.

But outsourcing everything is not the answer either.

The real question is:

What should remain in-house, what should be outsourced, and which responsibilities require professional expertise?

For accounting, bookkeeping, tax, financial reporting, and CFO support, working with an experienced professional team can allow business owners to maintain better financial control while focusing their time on customers, operations, and growth.

Table of Contents

  1. In-House vs. Outsourcing: What Is the Difference?
  2. Pros and Cons of Hiring In-House
  3. Pros and Cons of Outsourcing
  4. When Should a Business Consider Outsourcing?
  5. Why Accounting and Bookkeeping Are Strong Candidates
  6. Why Tax Services Require Professional Expertise
  7. Other Functions Businesses Can Outsource
  8. How Outsourcing Can Improve Productivity
  9. The Importance of Choosing the Right Partner
  10. The Hybrid Model
  11. A Practical Decision Framework
  12. FAQ
  13. Conclusion

In-House vs. Outsourcing: What Is the Difference?

Hiring in-house means the company employs and manages its own people to perform a function.

Business outsourcing means engaging an external professional or organization to perform defined responsibilities on behalf of the company.

Both models have legitimate advantages.

An internal employee may have deeper day-to-day knowledge of the company, while an external team may provide broader technical expertise and access to multiple professionals.

The right model depends on the nature of the work.

For example, a business may want its sales leadership and customer relationships managed internally while using business outsourcing for bookkeeping, tax preparation support, payroll administration, or financial reporting.

The decision should therefore be made function by function, not as an all-or-nothing strategy.

business outsourcing

Pros and Cons of Hiring In-House

Advantages of an In-House Team

An internal team can provide:

  • Direct supervision
  • Immediate communication
  • Strong company-specific knowledge
  • Greater control over daily activities
  • Closer integration with other departments
  • Stronger understanding of internal culture
  • Dedicated attention to the company’s priorities

For highly strategic functions that require constant collaboration, an internal employee may be the right choice.

For example, a company developing proprietary technology may prefer to keep its core development team in-house.

Disadvantages of Hiring In-House

However, hiring internally also creates responsibilities for the business.

Management needs to consider:

  • Recruitment costs
  • Salaries and benefits
  • Training
  • Software and technology
  • Employee turnover
  • Leave and backup coverage
  • Performance management
  • Office infrastructure
  • Professional development
  • Management time

There is also a specialization problem.

A small business may need the expertise of a senior accountant, tax professional, financial analyst, and CFO—but may not have enough workload to justify hiring four separate specialists.

That is one situation where business outsourcing can provide an alternative.

Pros and Cons of Outsourcing

Advantages of Outsourcing

A well-managed outsourcing arrangement can provide:

  • Access to specialized professionals
  • Flexible capacity
  • Lower fixed staffing requirements
  • Established processes
  • Multiple levels of review
  • Faster access to expertise
  • Reduced recruitment burden
  • Better scalability
  • Access to technology and accounting systems
  • More time for management to focus on strategic work

One major advantage is that the business may gain access to a team rather than one employee.

For example, an outsourced accounting arrangement could include a bookkeeper, accountant, senior reviewer, and manager.

This structure can provide continuity if one team member is unavailable.

Disadvantages of Outsourcing

Outsourcing is not automatically successful.

Potential challenges include:

  • Communication gaps
  • Poor-quality providers
  • Lack of business understanding
  • Data-security concerns
  • Inconsistent service
  • Unclear responsibilities
  • Overdependence on an external provider
  • Transition difficulties

Therefore, the quality of the outsourcing partner matters enormously.

A low-cost provider that creates errors and requires constant supervision may ultimately cost more than a competent professional team.

When Should a Business Consider Outsourcing?

Business outsourcing becomes particularly attractive when a company faces one or more of the following situations.

The Owner Is Doing Too Much Routine Work

If the owner spends several hours every week reviewing transactions, chasing documents, preparing reports, or solving recurring administrative problems, there is an opportunity cost.

That time could instead be spent on customers, strategy, pricing, partnerships, and growth.

Specialized Expertise Is Difficult to Hire

Some businesses need specialist knowledge without needing a full-time specialist.

A growing company may need financial forecasting every month but may not need a full-time CFO.

It may need experienced tax support during filing periods without needing a permanent tax department.

Business outsourcing can provide access to this expertise when it is required.

Workload Changes Throughout the Year

Tax, accounting, payroll, financial reporting, and compliance workloads can fluctuate.

Maintaining a large permanent team during low-volume periods may not be efficient.

External professionals can provide additional capacity when the workload increases.

The Business Is Growing Faster Than Its Internal Team

Hiring takes time.

Recruiting, interviewing, onboarding, training, and developing employees can delay the expansion of a department.

A qualified external team can sometimes provide additional capacity much faster.

Why Accounting and Bookkeeping Are Strong Candidates

Accounting and bookkeeping are often excellent areas for business outsourcing because they require technical knowledge, consistent processes, attention to detail, and regular execution.

These functions are essential to the business, but that does not necessarily mean every task needs to be performed internally.

A professional accounting team can support:

  • Daily bookkeeping
  • Bank reconciliation
  • Credit-card reconciliation
  • Accounts payable
  • Accounts receivable
  • Transaction classification
  • Month-end closing
  • Financial statement preparation
  • Management reports
  • Bookkeeping cleanup
  • Financial analysis
  • Cash-flow reporting

The biggest advantage is not simply saving the cost of an employee.

It is gaining access to a structured process and professional review.

Consider a company with one internal bookkeeper.

If that person leaves, the business may suddenly face delays in reconciliations, reporting, and month-end closing.

A properly structured external team can provide greater continuity because responsibilities can be distributed among multiple professionals.

For international businesses, business outsourcing can also provide access to professionals experienced with different accounting platforms, reporting requirements, currencies, and business models.

Why Tax Services Require Professional Expertise

Tax is another area where businesses should be careful about choosing between internal hiring and business outsourcing.

Tax rules can be complex, and requirements can vary based on business structure, location, transactions, employees, and jurisdictions.

The objective should not simply be to find the lowest-cost tax preparer.

A professional tax team should understand the client’s financial information, identify relevant compliance requirements, maintain appropriate documentation, and communicate issues clearly.

Tax-related outsourcing may include:

  • Tax return preparation support
  • Tax document organization
  • Tax compliance coordination
  • Sales tax support
  • Payroll tax support
  • Tax notice assistance
  • Tax planning support, where appropriately qualified

Businesses operating in multiple jurisdictions may have an even stronger need for professional assistance.

The important point is to clearly define who is responsible for preparation, review, filing, communication, and final approval.

Other Functions Businesses Can Outsource

Accounting and tax are not the only areas where external expertise can help.

CFO and Financial Advisory

A growing company may require:

  • Budgeting
  • Financial projections
  • Cash-flow forecasting
  • KPI dashboards
  • Profitability analysis
  • Scenario planning
  • Management reporting

An outsourced CFO can provide senior financial guidance without the cost of employing a full-time executive.

Human Resources

Recruitment coordination, payroll administration, employee documentation, and selected HR functions can often be handled externally.

Information Technology

Businesses may outsource IT support, cybersecurity, software administration, infrastructure, and technical assistance.

Digital Marketing

SEO, advertising, social media management, content development, and analytics are specialist areas that may be more efficient when managed by experienced external professionals.

Administrative Functions

Data entry, document management, scheduling, research, and other repetitive tasks can also be outsourced.

The principle is simple:

Keep strategic ownership where it matters and use specialists where they can deliver better value.

How Outsourcing Can Improve Productivity

The value of business outsourcing should not be measured only by the monthly invoice.

Consider a business owner who spends eight hours every week managing routine accounting issues.

That represents more than 400 hours a year.

What could the owner accomplish with those hours?

Perhaps:

  • Develop new customers
  • Improve pricing
  • Review profitability
  • Build strategic partnerships
  • Improve operations
  • Develop employees
  • Plan expansion
  • Strengthen customer relationships

This is where business outsourcing can become a productivity strategy.

The business is not simply purchasing labor.

It is gaining capacity, expertise, processes, and management time.

However, productivity improvements only happen when the outsourced team is capable of performing the work with limited supervision.

A poor provider can create additional work.

An experienced team should reduce the owner’s workload rather than transfer the workload into another form.

The Importance of Choosing the Right Outsourcing Partner

Choosing the right provider is one of the most important decisions in business outsourcing.

Price should be considered, but it should never be the only criterion.

1. Relevant Experience

Does the team understand your industry, accounting software, business model, and geographic requirements?

2. Professional Expertise

Who performs the work?

Who reviews it?

What qualifications and experience do they have?

3. Team Structure

Does the relationship depend entirely on one individual?

A structured team with backup and review procedures can provide greater continuity.

4. Quality Control

Ask how the provider reviews work before delivering it.

For accounting and tax-related services, review procedures are particularly important.

5. Communication

Agree on:

  • Response times
  • Reporting deadlines
  • Meeting frequency
  • Escalation procedures
  • Primary contacts

6. Data Security

Financial and tax information is highly sensitive.

Understand how documents are transferred, stored, accessed, and protected.

7. Scalability

Ask whether the provider can support additional transactions, entities, employees, or reporting requirements as the company grows.

8. Transparent Scope

A professional provider should clearly define:

  • Deliverables
  • Fees
  • Responsibilities
  • Turnaround times
  • Review procedures
  • Exclusions

Choosing the right partner makes business outsourcing significantly more effective.

The Hybrid Model: Often the Best of Both Worlds

Companies do not have to choose between completely internal and completely external operations.

A hybrid structure can often provide the best balance.

For example, a business might have an internal Finance Manager who maintains management control while outsourcing:

  • Bookkeeping
  • Reconciliations
  • Accounts payable
  • Accounts receivable
  • Month-end preparation
  • Tax support
  • Financial reporting

The internal manager maintains oversight while the external team handles recurring execution.

This creates a combination of control, flexibility, expertise, and scalability.

For many growing companies, this can be more practical than building a large finance department immediately.

A Practical Decision Framework

Before deciding whether to hire internally or outsource a function, ask these questions:

Is It Core to Our Competitive Advantage?

If the function directly creates competitive differentiation, keeping ownership internally may make sense.

Do We Need Specialized Expertise?

If expertise is expensive or difficult to recruit, an external professional team may be more practical.

Is the Workload Consistent?

If demand changes significantly throughout the year, flexible external capacity can be valuable.

Does the Function Require Daily Internal Collaboration?

If constant interaction is essential, an internal role may be preferable.

What Is the Total Cost?

Do not compare only salary against an outsourcing fee.

Include:

  • Recruitment
  • Benefits
  • Training
  • Software
  • Management time
  • Infrastructure
  • Employee turnover
  • Professional development
  • Opportunity cost

Then compare the total cost with the external solution.

This creates a more realistic decision.

FAQ

Is business outsourcing always cheaper than hiring in-house?

No. The objective should not simply be to find the cheapest option. Businesses should compare total cost, expertise, flexibility, quality, management time, and expected outcomes.

Should accounting and bookkeeping be outsourced?

For many growing companies, outsourcing accounting and bookkeeping can provide access to experienced professionals and structured processes without building a complete internal accounting department.

Can tax services be outsourced?

Yes. Many tax-related functions can be handled by appropriately qualified professionals. Businesses should verify experience, qualifications, responsibilities, review procedures, and compliance scope.

How do I choose the right outsourcing company?

Evaluate experience, qualifications, team structure, quality control, communication, technology, data security, scalability, transparency, and references or relevant track record.

Can outsourcing work together with an internal finance team?

Absolutely. A hybrid model can combine internal management oversight with external execution, particularly for bookkeeping, accounting operations, tax support, and financial reporting.

Is outsourced CFO support suitable for small businesses?

It can be. A growing business may need forecasting, budgeting, cash-flow planning, profitability analysis, and strategic financial advice without requiring a full-time CFO.

Conclusion

The decision to outsource or hire in-house should not be based solely on cost.

The better question is:

Which structure gives your business the right combination of expertise, control, flexibility, quality, and productivity?

Some functions are better kept internally. Others can be handled more efficiently by experienced specialists.

Accounting, bookkeeping, tax support, financial reporting, and selected CFO functions are often strong candidates for business outsourcing because they require technical expertise, consistent processes, and reliable execution.

But outsourcing successfully depends on choosing the right partner.

The right provider should not simply complete assigned tasks. It should understand your business, communicate clearly, maintain quality controls, protect confidential information, and scale with you.

At Veritas Accounting Services, we support businesses and professional firms with outsourced bookkeeping, accounting, tax support, financial reporting, financial projections, and CFO-related services. Our objective is to work as an extension of your team while allowing business leaders to focus on customers, strategy, and growth.

The goal is not to outsource everything.

The goal is to build the right team around your business.

Keep strategic responsibilities where they belong. Delegate specialized work to experienced professionals. And choose outsourcing partners based on expertise, reliability, processes, security, and long-term value—not simply price.

When approached strategically, business outsourcing is not merely a staffing decision.

It can become a competitive advantage.

GET IN TOUCH

Schedule a FREE Call
How Many Orders Does Your Business Need to Break Even?

A practical framing-shop example shows how to calculate the orders needed to cover costs and test a…

What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Connect on our Socials!

business productivity

The Difference Between Being Busy and Being Productive: What Business Leaders Need to Know

Running a business can create a dangerous illusion: a full calendar looks like progress. Business productivity starts with asking what the activity achieves. Meetings are attended, emails answered, invoices chased, and problems solved. Yet the week ends with one question: what actually moved the business forward?

That is the difference between activity and business productivity. Understanding business productivity is essential when leadership wants growth without adding unnecessary complexity.

Business productivity is not about making people work longer hours. It is about directing time, money, people, and technology toward outcomes that improve revenue, profitability, cash flow, customer experience, and long-term value.

For business leaders, this distinction becomes more important as the company grows. A founder can personally solve problems in a small business. At scale, the same approach creates bottlenecks, delays decisions, and keeps senior management trapped in routine work.

Table of Contents

  1. What Does It Mean to Be Busy?
  2. What Does It Mean to Be Productive?
  3. Busy vs. Productive: The Key Difference
  4. Why Business Leaders Fall Into the Busy Trap
  5. How Financial Information Supports Business Productivity
  6. 7 Ways to Move From Busy to Productive
  7. How a CA or CFO Can Improve Business Productivity
  8. Questions Business Leaders Should Ask
  9. FAQ
  10. Conclusion

What Does It Mean to Be Busy?

Being busy usually means responding to whatever demands attention. A business owner may spend a day answering emails, approving expenses, checking bank balances, attending meetings, following up with customers, reviewing spreadsheets, and solving employee questions.

Those activities may be necessary. The problem is that necessity does not create value.

A business can have employees working hard while receivables remain overdue, monthly accounts stay late, or margins fall. Effort is not the issue.

What Does It Mean to Be Productive?

Productive work creates a measurable outcome. A productive finance team does not simply enter transactions; it closes the books accurately and on time. A productive sales team does not simply make calls; it generates qualified opportunities and revenue. A productive management meeting does not simply consume an hour; it produces decisions, owners, and deadlines.

This is the foundation of business productivity: connect activity to outcomes. Strong business productivity comes from choosing work that produces a measurable result.

For example, instead of asking an employee to “work on receivables,” management can define the outcome as reducing overdue invoices. For accounting, the objective can be accurate month-end financials by an agreed date.

Busy vs. Productive: The Key Difference

The difference becomes clearer when management looks at results rather than hours.

Busy businesses often:

  • React to every request immediately
  • Keep the owner involved in routine decisions
  • Measure effort rather than outcomes
  • Rely heavily on spreadsheets and manual processes
  • Discover financial problems after they become urgent
  • Hold meetings without clear decisions
  • Repeatedly solve the same operational problems

Productive businesses tend to:

  • Prioritize high-value work
  • Delegate responsibility with accountability
  • Use measurable KPIs
  • Standardize recurring processes
  • Review financial information regularly
  • Automate repetitive tasks
  • Focus leadership attention on decisions that require judgment

A strong business does not eliminate activity. It makes activity purposeful. That is what sustainable business productivity looks like in practice.

Why Business Leaders Fall Into the Busy Trap

Owner Dependency

Many growing businesses depend heavily on the founder. The owner approves payments, answers customer questions, reviews every expense, resolves staff issues, and makes operational decisions.

This may work initially, but it becomes a constraint as the company grows.

If every decision has to reach the owner, employees wait, customers wait, and strategic work gets postponed. Improving business productivity often begins with identifying decisions that can be delegated. That creates room for leadership to focus on strategy.

Manual Processes

Manual work is another major source of wasted capacity.

Consider a business where employees download bank statements, enter transactions into spreadsheets, match payments manually, collect receipts by email, and prepare management reports from multiple files.

Each individual task may appear small. Together, they can consume hundreds of hours every year.

The solution is not always more employees. Better workflow design, accounting software, automation, and clear responsibilities can remove unnecessary work.

For businesses that are spending too much management time on routine bookkeeping, outsourcing can be an effective option. Veritas provides virtual bookkeeping services designed to help businesses maintain organized and accurate financial records while allowing management to focus on higher-value activities.

Delayed Financial Information

A business leader cannot make productive decisions without reliable financial information.

If management receives financial statements months after the period ends, the information has limited value for immediate decision-making. Timely bookkeeping and month-end reporting can reveal changes in revenue, gross margin, expenses, receivables, payables, and cash flow while there is still time to respond.

How Financial Information Supports Business Productivity

Financial reporting is not simply a compliance exercise. It is a management system.

The U.S. Small Business Administration notes that accounting for revenue and expenses can help a business operate smoothly, while a balance sheet provides a snapshot of financial position and supports financial management. Business owners can also refer to the SBA financial management guidance for additional information.

The IRS likewise explains that good business records help owners monitor progress, prepare financial statements, identify income sources, track expenses, and prepare tax returns. The IRS recordkeeping guidance provides additional detail.

This matters because leaders need more than a bank balance. They need to understand what the numbers are saying.

Useful measures may include:

  • Revenue growth
  • Gross profit margin
  • Operating expense ratio
  • Accounts receivable days
  • Cash conversion cycle
  • Revenue per employee
  • Customer or product profitability
  • Actual results versus budget
  • Forecast versus actual cash flow

For example, revenue may increase while receivables rise sharply and gross margin declines. The company may be growing without improving its financial position.

Better business productivity comes from understanding these relationships. Financial visibility helps leaders measure whether effort is creating value.

7 Ways to Move From Busy to Productive

1. Define Outcomes Before Activities

Before adding a task to the calendar, ask what outcome it is expected to create.

Instead of “review expenses,” the goal might be “identify and remove recurring costs that do not support business priorities.”

Instead of “check cash,” the goal might be “maintain sufficient liquidity for the next 90 days.”

The question should always be:

What business result will this activity create?

2. Delegate Ownership, Not Just Tasks

Effective delegation means transferring responsibility for a result.

For example, an accounts receivable manager should not merely send reminder emails. The person should own the process of monitoring aging, following up with customers, identifying disputes, and escalating collection risks.

Clear ownership improves accountability and supports business productivity. It also reduces the number of routine decisions that return to the owner.

3. Create Repeatable Processes

If the same issue appears every month, do not rely on another reminder.

Build a process.

Document who performs the task, what information is needed, when it must be completed, what review is required, and what happens when something goes wrong.

Standard operating procedures reduce dependence on memory and make it easier to train new employees.

4. Close the Books on a Regular Schedule

A disciplined month-end close gives management a reliable view of performance.

A useful monthly close can include:

  • Bank and credit-card reconciliations
  • Accounts receivable review
  • Accounts payable review
  • Accruals and prepaid expenses
  • Payroll review
  • Fixed-asset updates
  • Revenue reconciliation
  • Management reporting

Accurate books make business productivity measurable because management can compare actual performance with targets. This makes financial reviews more useful.

5. Automate Repetitive Work

Technology should remove repetitive administration where practical.

Businesses can often automate or streamline:

  • Bank feeds
  • Invoice creation
  • Payment reminders
  • Receipt collection
  • Recurring transactions
  • Payroll workflows
  • Management reports
  • Data synchronization between platforms

Automation should not replace professional judgment. It should create more time for analysis and decision-making.

6. Use a Management Dashboard

A dashboard should answer the questions leadership actually cares about.

Depending on the business, it might include:

  • How much did we sell?
  • How profitable were those sales?
  • How much cash do we have?
  • What customers owe us?
  • What bills are due?
  • Which costs increased?
  • Are we on budget?
  • What is expected over the next three to six months?

A focused dashboard can improve business productivity by reducing the time required to locate and interpret information.

7. Review Performance and Take Action

Reporting has little value if no one acts on it.

A monthly management review should answer four questions:

What happened?

Why?

What happens next?

What action should we take?

This turns accounting information into action.

How a CA or CFO Can Improve Business Productivity

Business leaders do not need to perform every financial task themselves.

An experienced CA, accountant, controller, or outsourced CFO can build the financial infrastructure that supports better decisions.

A professional accounting partner can help with:

  • Bookkeeping and transaction classification
  • Bank and credit-card reconciliation
  • Accounts payable and receivable
  • Month-end closing
  • Financial statement preparation
  • Budgeting and forecasting
  • Cash-flow planning
  • KPI and ratio analysis
  • Profitability analysis
  • Tax compliance coordination
  • Management reporting
  • Financial projections

The value is not completing tasks. The goal is to create business productivity through reliable financial information.

The professional should help management understand what the numbers mean and what action is appropriate.

For example, if operating expenses increase, the right question is not simply, “Which expense increased?”

Management should also ask:

  • Why did it increase?
  • Is the increase temporary or recurring?
  • Did it generate additional revenue?
  • Is the return sufficient?
  • Can the process be redesigned?
  • Does the business need to change its budget or forecast?

That is where accounting becomes advisory rather than purely administrative.

For businesses working across borders, outsourced accounting can also create consistency across entities, currencies, accounting systems, and reporting requirements. A centralized finance process gives leadership a clearer view without requiring the owner to coordinate every transaction.

Businesses that need flexible financial support can also consider remote bookkeeping services as part of a broader outsourced accounting structure.

Questions Business Leaders Should Ask

To assess your current level of business productivity, ask:

  • How much of my week is routine operational work?
  • Which decisions still require my approval?
  • Are our books closed on time?
  • Can I see profitability by customer or service?
  • Do I have a current cash-flow forecast?
  • How quickly can I identify unusual expenses?
  • Which processes still depend on spreadsheets?
  • What recurring problems keep returning?
  • Are employees measured by activity or outcomes?
  • If revenue doubled, would our systems handle it?

If several answers concern you, the issue may not be a lack of effort. It may be a lack of systems. Improving business productivity often requires redesigning how information and decisions move through the company.

FAQ

What is the difference between being busy and being productive?

Being busy means completing many activities, while being productive means directing time and resources toward measurable outcomes that support business goals.

How does accounting support business productivity?

Accurate accounting provides timely information about revenue, expenses, margins, receivables, payables, cash flow, and profitability. This helps management make informed decisions.

Can an outsourced accountant improve business productivity?

Yes. An outsourced accountant can take responsibility for recurring financial processes, allowing business owners and internal teams to focus on customers, operations, strategy, and growth.

What financial metrics should business leaders monitor?

Common measures include revenue growth, gross margin, operating expenses, receivable days, cash flow, revenue per employee, customer profitability, and budget-to-actual performance.

When should a company consider CFO advisory services?

CFO advisory support can be useful when a company needs stronger forecasting, cash-flow planning, profitability analysis, budgeting, financial strategy, or management reporting without hiring a full-time CFO.

Conclusion

Being busy can feel productive because activity is visible. Business performance, however, is determined by outcomes.

A productive business creates systems, financial visibility, and accountability so work contributes to objectives.

For leaders, the first step is often financial clarity. When you understand where revenue comes from, where cash is going, which activities create value, and where inefficiencies exist, you can make better decisions.

This is where professional accounting and CFO support can make a meaningful difference.

Veritas Accounting Services helps business owners, CPA firms, and tax professionals with outsourced bookkeeping, accounting, financial reporting, CFO support, cash-flow management, financial projections, and related finance functions. Our goal is to help clients spend less time managing routine financial work and more time managing the business.

If your company is constantly busy but still struggling to achieve the results you expect, it may be time to examine the systems behind the work.

Build better processes. Measure meaningful outcomes. Protect business productivity by reviewing what actually creates value. Use your financial data. And make productivity a business strategy, not simply a personal goal.

GET IN TOUCH

Schedule a FREE Call
How Many Orders Does Your Business Need to Break Even?

A practical framing-shop example shows how to calculate the orders needed to cover costs and test a…

What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Connect on our Socials!

financial literacy

Why Financial Literacy Is the New Business Superpower

Running a business requires making decisions every day. Should you hire another employee? Can you afford new equipment? Is it time to expand? Should you increase prices? Can you take on more debt?

These decisions may look operational on the surface, but many of them are actually financial decisions.

That is why financial literacy has become such an important business skill.

Financial literacy does not mean becoming an accountant. It means understanding the numbers well enough to know what is happening inside your business, why it is happening, and what you should consider doing next.

For business owners, that understanding can turn financial information into better decisions.


What Is Financial Literacy in Business?

Financial literacy is the ability to understand and use financial information when making business decisions.

A financially literate business owner should be comfortable discussing areas such as:

  • Revenue
  • Expenses
  • Profit
  • Cash flow
  • Assets
  • Liabilities
  • Working capital
  • Debt
  • Margins
  • Taxes
  • Financial forecasts

You do not need to prepare every journal entry yourself.

You do need to understand what the numbers are telling you.

That difference is important.

A business owner who understands the numbers can ask better questions, challenge assumptions, identify risks, and work more effectively with accountants, CAs, CFOs, and other professionals.


Why Financial Literacy Matters for Business Owners

A business can have strong sales and still experience financial problems.

It can show accounting profit while struggling with cash.

It can have growing revenue but declining margins.

It can have plenty of customers but not enough working capital.

Financial literacy helps business owners see beyond one number.

1. It Improves Decision-Making

Every important business decision has a financial consequence.

Hiring an employee increases payroll.

Opening another location increases fixed costs.

Buying equipment requires capital.

Reducing prices affects margins.

Taking a loan creates repayment obligations.

Understanding these effects helps owners evaluate decisions before committing resources.

Instead of asking only, “Can we do this?”, financially informed owners can ask:

“What will this decision do to our cash flow, profitability, and financial position?”

That is a much stronger question.


Profit Is Not the Same as Cash

One of the most important concepts business owners should understand is the difference between profit and cash flow.

A company can report a profit but still experience cash shortages.

For example, imagine a business makes $100,000 in sales during a month but customers have 60-day payment terms.

The business may record revenue according to applicable accounting rules, but the cash may not arrive immediately.

Meanwhile, the company still has to pay:

  • Employees
  • Vendors
  • Rent
  • Utilities
  • Taxes
  • Loan payments

Understanding this difference helps owners manage working capital more effectively.

Financial literacy gives business leaders the ability to recognize that a profitable business still needs healthy cash management.


Understanding the Profit and Loss Statement

The profit and loss statement is one of the most useful reports for a business owner.

It helps answer questions such as:

  • How much revenue did we generate?
  • What did it cost to generate that revenue?
  • What are our operating expenses?
  • What is our gross profit?
  • What is our net profit?
  • Are margins improving or declining?

But simply receiving a monthly report is not enough.

Business owners should look for trends.

For example:

If revenue increases by 20% but profit increases by only 5%, what happened?

Perhaps:

  • Costs increased
  • Prices were too low
  • Payroll increased
  • Marketing became less efficient
  • Gross margins declined

This is where understanding financial information becomes a management advantage.


Understanding the Balance Sheet

Many business owners pay more attention to the profit and loss statement than the balance sheet.

That can be a mistake.

The balance sheet provides information about:

  • Assets
  • Liabilities
  • Equity
  • Cash
  • Accounts receivable
  • Inventory
  • Loans
  • Other obligations

It can help answer an important question:

What is the financial position of the business today?

A business may be profitable while carrying significant debt or having too much money tied up in inventory and receivables.

Understanding the balance sheet helps owners recognize these issues.


Financial Literacy Helps With Pricing

Pricing decisions should not be based only on what competitors charge.

Business owners should understand:

  • Direct costs
  • Labor costs
  • Overhead
  • Gross margin
  • Customer acquisition costs
  • Desired profit
  • Market conditions

For example, increasing sales volume does not necessarily improve profitability if every additional sale generates very little margin.

A financially informed owner can evaluate whether a product, service, or customer is actually contributing enough to the business.


It Helps Business Owners Control Expenses

Not every expense is bad.

The real question is whether an expense creates sufficient value.

Financial literacy helps owners distinguish between:

Essential costs

Costs required to operate the business.

Growth investments

Spending intended to generate future revenue or efficiency.

Unnecessary spending

Expenses that provide little measurable business value.

Reviewing expenses regularly can reveal opportunities to improve profitability without simply cutting costs across the board.


It Makes Cash Flow Planning Easier

Cash flow problems can develop before a business owner realizes there is a problem.

A company may have:

  • Increasing sales
  • Growing receivables
  • Large inventory purchases
  • Higher payroll
  • New equipment payments

All of these can increase the amount of cash required to operate.

Financial literacy helps owners understand how these moving parts interact.

A cash flow forecast can then help answer:

  • How much cash will we need next month?
  • When will major payments become due?
  • Can we afford the planned investment?
  • Will customer collections cover upcoming expenses?
  • Do we need additional working capital?

These questions are critical for growing businesses.


Financial Literacy Supports Smarter Growth

Growth sounds positive, but growth also consumes resources.

A company that doubles its sales may need:

  • More employees
  • More inventory
  • Larger premises
  • More technology
  • More working capital
  • Additional financing

Without understanding the financial requirements of growth, a business can expand faster than its cash resources allow.

Financial literacy helps owners evaluate whether growth is not only possible but financially sustainable.


Understanding Debt Before Taking It

Borrowing can help a business grow, but debt creates future obligations.

Before taking a loan, business owners should understand:

  • Interest costs
  • Repayment schedules
  • Total borrowing costs
  • Collateral requirements
  • Cash flow impact
  • Debt-to-equity considerations

The important question is not simply:

“How much can the bank lend us?”

It is:

“How much debt can our business comfortably manage?”

Financial literacy helps owners evaluate borrowing decisions more responsibly.


It Helps Identify Problems Earlier

Financial problems rarely appear overnight.

There are often warning signs.

These may include:

  • Declining gross margins
  • Increasing receivables
  • Falling cash balances
  • Rising debt
  • Increasing overhead
  • Slower customer payments
  • Inventory building up
  • Declining profitability

Business owners who understand their financial information are more likely to notice these changes early.

Early identification gives management more time to respond.

financial literacy

Financial Literacy Makes Professional Advice More Valuable

Working with a CA, accountant, CFO, or financial advisor does not mean the business owner should stop understanding the numbers.

In fact, the opposite is true.

When owners understand the basics, professional conversations become more productive.

Instead of simply asking:

“Is the business doing well?”

they can ask:

  • Why did gross margin change?
  • Why is cash flow lower than profit?
  • Which expenses increased?
  • How much working capital do we need?
  • What happens if revenue falls by 10%?
  • Can we afford another employee?
  • Which services generate the strongest margins?

Better questions lead to better discussions and better decisions.


How a CA Can Help Improve Financial Understanding

A CA can play an important role in helping business owners turn financial reports into practical business information.

Financial Reporting

A CA can help ensure that financial statements are properly prepared and useful for management.

Financial Analysis

Historical results can be analyzed to identify trends in revenue, expenses, margins, and profitability.

Cash Flow Forecasting

A CA can help prepare forecasts that show expected cash inflows and outflows.

Budgeting

Budgets provide a financial roadmap and allow actual results to be compared with expectations.

Tax Planning

Understanding expected tax obligations can help owners avoid unexpected cash requirements.

Business Advisory

A CA can help owners evaluate the financial impact of hiring, expansion, pricing, financing, and other major decisions.

The goal is not simply to provide reports.

The goal is to help the owner understand what those reports mean.


Financial Literacy Is Not About Doing Everything Yourself

There is a common misconception that financially literate business owners should handle their own bookkeeping, accounting, tax preparation, and financial analysis.

That is not the objective.

A business owner should know enough to:

  • Understand key reports
  • Ask relevant questions
  • Recognize warning signs
  • Evaluate major decisions
  • Communicate effectively with professionals
  • Understand financial consequences

Professional support can then handle the technical work.

Think of it this way:

You do not need to be a mechanic to understand your car’s dashboard.

You need to know what the warning lights mean and when to call a professional.

Business finances work in a similar way.


Simple Financial Habits Every Business Owner Can Build

Improving financial knowledge does not have to happen overnight.

Start with a few practical habits.

Review Financial Statements Monthly

Do not wait until tax season to look at your numbers.

Compare Actual Results With Budget

Understand where the business is performing above or below expectations.

Monitor Cash Flow

Know how much cash is available and what major payments are coming.

Track Key Metrics

Depending on the business, monitor:

  • Gross margin
  • Net margin
  • Accounts receivable
  • Accounts payable
  • Customer acquisition cost
  • Revenue growth
  • Operating expenses

Ask Why, Not Just What

Do not stop at “revenue decreased.”

Ask why revenue decreased and what management can do about it.

Discuss Results With Your CA

Use regular financial reviews to turn reports into action.

financial literacy

Financial Literacy Creates Better Leadership

Leadership is ultimately about making decisions under uncertainty.

Financial information reduces some of that uncertainty.

A financially informed business owner can evaluate opportunities more objectively, recognize risks earlier, and understand the consequences of major decisions.

This can create a stronger relationship between financial data and business strategy.

Instead of finance being something reviewed after decisions are made, it becomes part of the decision-making process itself.


The Future of Business Requires Financial Understanding

Technology is making financial information more accessible than ever.

Cloud accounting platforms, dashboards, automated reporting, forecasting tools, and artificial intelligence can help businesses analyze information faster.

But technology does not automatically create understanding.

Someone still needs to interpret the information, question unusual results, consider business context, and decide what action makes sense.

That is why financial literacy remains valuable even as technology becomes more powerful.

The future is not about business owners replacing financial professionals.

It is about business owners and financial professionals working together more effectively.


The Bottom Line

Financial literacy is becoming one of the most valuable skills a business owner can develop.

You do not need to become an accountant.

You need to understand enough about your numbers to recognize what is happening, ask better questions, evaluate opportunities, and identify risks before they become serious problems.

Profitability, cash flow, pricing, debt, expenses, taxes, and growth are all connected.

A CA or financial professional can provide the technical expertise, analysis, forecasting, and advice needed to turn financial information into practical decisions.

But the more financially informed the business owner is, the more value that professional relationship can create.

Financial literacy is not about knowing every number in your business. It is about knowing which numbers matter, what they are telling you, and what you should do next.

That is what makes financial literacy a true business superpower.


Frequently Asked Questions

What does financial literacy mean for a business owner?

It means understanding key financial concepts and reports well enough to make informed decisions about profitability, cash flow, expenses, debt, pricing, and growth.

Does a business owner need to know accounting?

A business owner does not need to become an accountant, but understanding basic financial reports and concepts can significantly improve decision-making.

Why is cash flow important if a business is profitable?

Profit and cash flow are different. A profitable company can still experience cash shortages when customers pay later, inventory consumes cash, or large expenses become due.

How can a CA help a business owner?

A CA can help with financial reporting, analysis, budgeting, forecasting, tax planning, profitability analysis, and strategic financial decisions.

What financial reports should business owners review?

The profit and loss statement, balance sheet, and cash flow information are among the most important reports for understanding business performance and financial position.

How can business owners improve their financial knowledge?

Start by reviewing financial reports regularly, understanding key metrics, comparing actual results with budgets, monitoring cash flow, and discussing financial performance with a qualified professional.

GET IN TOUCH

Schedule a FREE Call
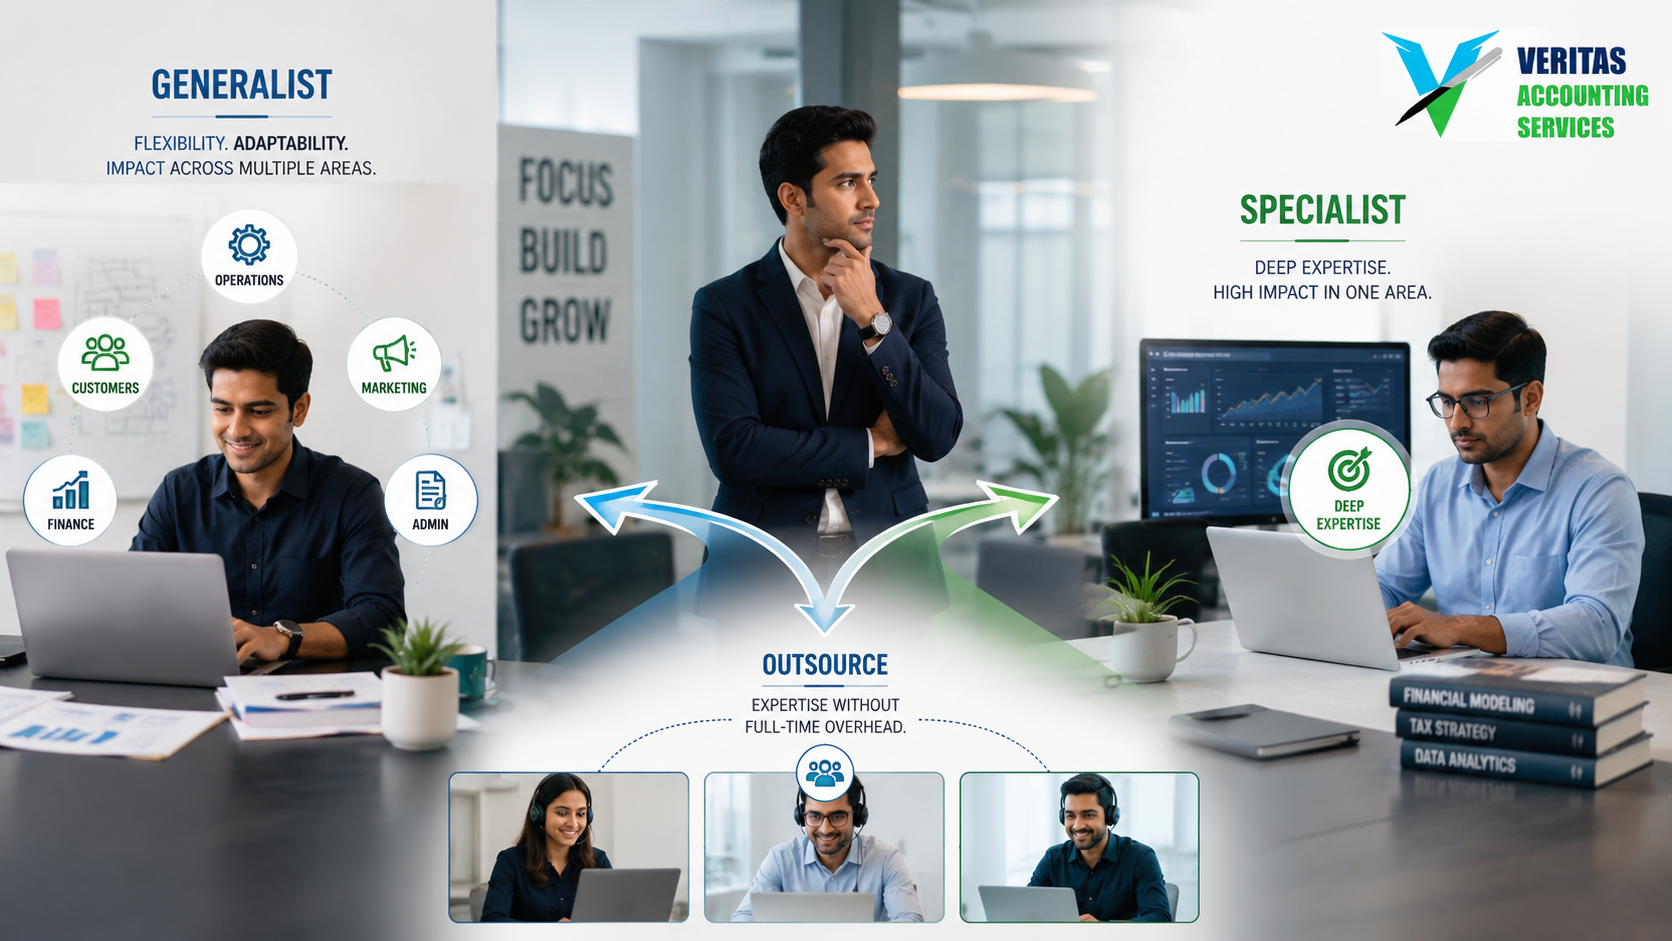
How Many Orders Does Your Business Need to Break Even?

A practical framing-shop example shows how to calculate the orders needed to cover costs and test a…

What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Connect on our Socials!

legal documents

Why Legal Documents Matter for Small Businesses

Running a small business is about more than generating revenue. Owners also need to protect the company, define relationships, manage financial obligations, and prepare for unexpected situations.

One of the most practical ways to create that foundation is by using appropriate legal documents.

Many businesses begin with informal arrangements. A customer agrees to work through email, business partners rely on verbal conversations, or an owner downloads a generic agreement from the internet. These approaches may work temporarily, but they can create uncertainty as the business grows.

Well-prepared legal documents establish clear expectations around ownership, responsibilities, payments, confidentiality, services, and other important business relationships.

They also help attorneys, CAs, accountants, advisors, and management work from the same information.


What Are Legal Documents?

Legal documents are formal records and agreements that establish or support important aspects of a company’s legal and business relationships.

Depending on the company, these may include:

  • Business formation records
  • Operating agreements
  • Partnership agreements
  • Customer contracts
  • Vendor agreements
  • Employment agreements
  • Contractor agreements
  • Non-disclosure agreements
  • Lease agreements
  • Privacy policies
  • Terms and conditions
  • Intellectual property agreements
  • Insurance records
  • Tax and financial documentation

Not every business requires the same documents.

The appropriate documentation depends on the business structure, industry, location, employees, customers, assets, and activities of the company.

Legal Documents Every Small Business Should Consider

Why Legal Documents Matter for Small Businesses

The purpose of legal documents goes beyond protecting a business during a dispute.

They can improve clarity, establish accountability, reduce misunderstandings, and support better financial and operational management.

1. They Clarify Ownership

Businesses with multiple owners should clearly document their ownership arrangements.

Important areas may include:

  • Ownership percentages
  • Capital contributions
  • Profit distributions
  • Voting rights
  • Management responsibilities
  • Owner compensation
  • Transfer of ownership
  • Withdrawal of an owner
  • Business dissolution

Without written documentation, different owners may have completely different expectations.

An operating or partnership agreement can provide a common reference point.


2. They Define Responsibilities

Every business relationship has expectations.

A customer needs to know what will be delivered.

A vendor needs to understand its obligations.

An employee needs to understand their role.

A business partner needs to understand their responsibilities.

Written legal documents can establish these expectations before work begins.

This reduces the risk of disagreements based on different interpretations of verbal conversations.


3. They Reduce Business Disputes

A significant number of business disagreements arise from unclear expectations.

For example, a customer may believe additional work is included in a fixed fee. A supplier may expect payment earlier than anticipated. A partner may believe they have authority to make a decision that another owner believes requires approval.

Clear legal documents can provide evidence of what the parties agreed to.

They cannot prevent every disagreement, but they can create greater clarity when questions arise.


Important Legal Documents Every Small Business Should Consider

The documents a company needs will vary, but several categories are commonly important.

1. Business Formation Documents

When a company is established as an LLC, corporation, partnership, or another structure, formation records establish important information about the business.

Depending on the structure, these may include:

  • Articles of incorporation
  • Articles of organization
  • Partnership agreements
  • Operating agreements
  • Ownership records

A CA can help explain accounting and tax considerations associated with a structure, while an attorney can advise on legal requirements.


2. Operating and Partnership Agreements

Multiple-owner businesses should carefully document how the company will operate.

These legal documents may address:

  • Ownership percentages
  • Capital contributions
  • Profit and loss allocation
  • Voting rights
  • Management responsibilities
  • Owner compensation
  • Transfer restrictions
  • Withdrawal procedures
  • Dispute resolution
  • Dissolution

Putting these matters in writing can prevent serious confusion later.


3. Customer Contracts

Customer contracts are particularly important for service businesses.

A customer agreement may define:

  • Scope of work
  • Services provided
  • Pricing
  • Payment terms
  • Deadlines
  • Deliverables
  • Customer responsibilities
  • Cancellation conditions
  • Confidentiality
  • Other applicable terms

A written agreement allows both parties to understand what they are accepting before work begins.


4. Vendor and Supplier Agreements

Businesses should also document important relationships with suppliers and service providers.

Vendor legal documents may establish:

  • Pricing
  • Payment schedules
  • Delivery requirements
  • Quality expectations
  • Responsibilities
  • Confidentiality
  • Termination provisions

These arrangements can directly affect operating costs and cash flow.

A CA or financial professional can help evaluate the financial impact of these commitments.


5. Employment and Contractor Agreements

Employees and independent contractors may require different documentation.

Depending on the relationship, agreements can address:

  • Compensation
  • Responsibilities
  • Working arrangements
  • Confidentiality
  • Intellectual property
  • Benefits
  • Termination
  • Company policies

Employment classification and related requirements can be complex, so businesses should seek appropriate professional advice.


6. Non-Disclosure Agreements

Companies frequently share confidential information with employees, contractors, vendors, partners, and potential investors.

This information could include:

  • Customer information
  • Pricing
  • Financial information
  • Business plans
  • Product designs
  • Marketing strategies
  • Proprietary processes

A non-disclosure agreement, commonly called an NDA, can establish expectations regarding confidential information.


7. Terms and Conditions

Businesses operating websites, ecommerce stores, or digital services may need appropriate terms and conditions.

These may cover:

  • Payments
  • Returns
  • Cancellations
  • Customer responsibilities
  • Service limitations
  • Website usage
  • Dispute procedures

The appropriate terms depend on the company’s activities and applicable laws.


8. Privacy and Data Protection Documents

Modern businesses often collect customer information through websites, ecommerce platforms, applications, and other systems.

Appropriate privacy documentation can explain how information is:

  • Collected
  • Used
  • Stored
  • Shared
  • Protected

Privacy requirements vary by location and industry, so professional legal advice may be appropriate.


9. Intellectual Property Documents

Businesses can own valuable intellectual property such as:

  • Trademarks
  • Copyrights
  • Designs
  • Software
  • Written content
  • Branding
  • Proprietary processes

Documentation can establish ownership and licensing arrangements.

This becomes especially important when contractors or outside agencies create designs, software, marketing materials, or other assets for the company.

Legal Documents Every Small Business Should Consider

How a CA Can Help With Legal Documents

A CA or accounting professional does not replace an attorney.

However, a CA can provide valuable financial and tax support when legal documents have accounting or financial consequences.

Understanding Financial Impact

Agreements can affect:

  • Revenue
  • Expenses
  • Cash flow
  • Liabilities
  • Profitability
  • Tax considerations

A CA can help business owners understand these consequences before entering into important arrangements.

For example, a long-term supplier agreement may appear commercially attractive but create significant recurring financial commitments.


Evaluating Business Structure

Business structure can have accounting and tax consequences.

A CA can help owners evaluate:

  • Tax treatment
  • Owner compensation
  • Profit distributions
  • Capital contributions
  • Financial reporting
  • Payroll implications

The legal aspects of establishing a structure should be addressed by an appropriate attorney.


Reviewing Financial Terms

Many important business agreements contain financial provisions that deserve careful attention.

A financial professional can help evaluate:

  • Payment schedules
  • Deposits
  • Retainers
  • Pricing
  • Revenue-sharing arrangements
  • Refund obligations
  • Late-payment terms
  • Financial commitments

The CA’s role is to assess financial and accounting implications rather than provide legal interpretation.


Maintaining Supporting Records

A signed agreement is only part of good business documentation.

Companies should also maintain:

  • Invoices
  • Receipts
  • Payment records
  • Bank records
  • Tax documents
  • Amendments
  • Financial schedules
  • Supporting correspondence

Accountants can help maintain organized financial records that support these relationships.


How Other Professionals Can Help

Small businesses often benefit from having several professionals contribute to different areas.

Attorney

An attorney can provide legal advice, prepare or review agreements, interpret legal obligations, and assist with disputes.

CA or Accountant

A CA can evaluate accounting, tax, financial, and recordkeeping implications.

CFO or Business Advisor

A CFO or advisor can evaluate financial commitments, risks, profitability, and strategic consequences.

HR Professional

An HR professional can support employment-related processes and documentation.

Insurance Professional

An insurance professional can help assess appropriate business coverage and risk-management requirements.

Each specialist provides a different layer of protection.


Legal Documents and Financial Management Work Together

Legal and financial matters are closely connected.

Consider a simple customer agreement:

Service → Price → Payment Terms → Delivery → Refund Conditions

These terms can eventually affect:

  • Revenue
  • Accounts receivable
  • Cash flow
  • Financial reporting
  • Tax calculations
  • Profitability

A vendor agreement can similarly influence expenses, working capital, and budgeting.

This is why financial professionals should understand the financial implications of important agreements.


Common Mistakes Small Businesses Make

Relying on Verbal Agreements

Important business arrangements should not depend entirely on conversations.

Using Generic Templates

An online template may not reflect the company’s specific circumstances or jurisdiction.

Ignoring Financial Terms

Owners may focus on legal wording while overlooking payment obligations and financial commitments.

Failing to Update Agreements

A document created several years ago may no longer reflect the current business.

Poor Document Organization

Important records should be stored securely and remain accessible to authorized people.

Waiting Until a Dispute Occurs

It is better to establish clear documentation before a problem develops.


Create a Business Document Management System

Small businesses do not need a complicated system.

A practical digital structure can organize records into categories such as:

Corporate Records

Formation records, ownership information, and company agreements.

Customer Records

Contracts, proposals, service agreements, and amendments.

Vendor Records

Supplier contracts and service agreements.

Employee Records

Employment agreements, policies, and relevant documentation.

Financial Records

Tax documents, invoices, financial statements, and supporting records.

Insurance Records

Policies, certificates, and claims information.

A secure document management system makes it easier to locate important information when management, accountants, auditors, or attorneys need it.

Legal Documents Every Small Business Should Consider

When Should Businesses Review Legal Documents?

Companies should review important legal documents periodically and whenever major changes occur.

Examples include:

  • A new owner joins
  • An owner leaves
  • Ownership percentages change
  • The company enters a new market
  • New employees are hired
  • New services are introduced
  • Major contracts are signed
  • The company expands geographically
  • Significant assets are acquired
  • Regulations change

Regular reviews help identify outdated, incomplete, or missing documentation.


Legal Protection Is Part of Business Planning

Business owners naturally focus on revenue, customers, marketing, and profitability.

However, protecting the business is equally important.

Effective legal documents can establish:

Clear ownership

Clear responsibilities

Clear payment expectations

Clear business relationships

Clear financial obligations

Clear processes

This creates a stronger foundation for sustainable growth.


Building the Right Professional Team

A business owner should not expect one professional to handle every aspect of the company.

Instead, different specialists can work together.

The attorney focuses on legal matters.

The CA focuses on accounting and taxation.

The financial advisor focuses on financial planning.

The HR professional focuses on employment processes.

The business advisor focuses on strategy and risk.

When these professionals collaborate, business owners can make better-informed decisions.


The Bottom Line

Legal documents are not simply paperwork stored in a folder.

They help define relationships, clarify responsibilities, establish financial expectations, protect business interests, and reduce uncertainty.

Every small business should identify the documentation appropriate for its structure, industry, location, and operations.

A CA can provide valuable support by explaining accounting and tax implications, reviewing financial terms, organizing supporting records, and identifying situations where additional professional guidance may be appropriate.

Legal advice and legal drafting, however, should be handled by a qualified attorney.

The strongest approach is collaboration.

Legal professionals protect the legal side. Financial professionals protect the financial side. Business leaders bring the information together to make better decisions.

A strong documentation foundation can help a small business operate with greater clarity, confidence, and resilience.


Frequently Asked Questions

Why are legal documents important for a small business?

They help establish ownership, responsibilities, payment terms, business relationships, confidentiality, and other important obligations.

What legal documents should a small business consider?

Depending on the company, these may include formation records, operating agreements, customer contracts, vendor agreements, employment agreements, NDAs, privacy documents, and intellectual property agreements.

Can a CA prepare legal documents?

A CA can provide accounting, tax, and financial guidance, but legal drafting and legal advice should generally be handled by a qualified attorney.

How can a CA help with business agreements?

A CA can review financial provisions and explain their potential accounting, tax, cash-flow, and profitability implications.

How often should business documentation be reviewed?

It should be reviewed periodically and whenever there are significant changes in ownership, operations, contracts, employees, markets, or applicable requirements.

Are online templates enough?

Templates can provide a starting point, but important agreements should be reviewed by an appropriate professional to ensure they fit the company’s circumstances.

GET IN TOUCH

Schedule a FREE Call
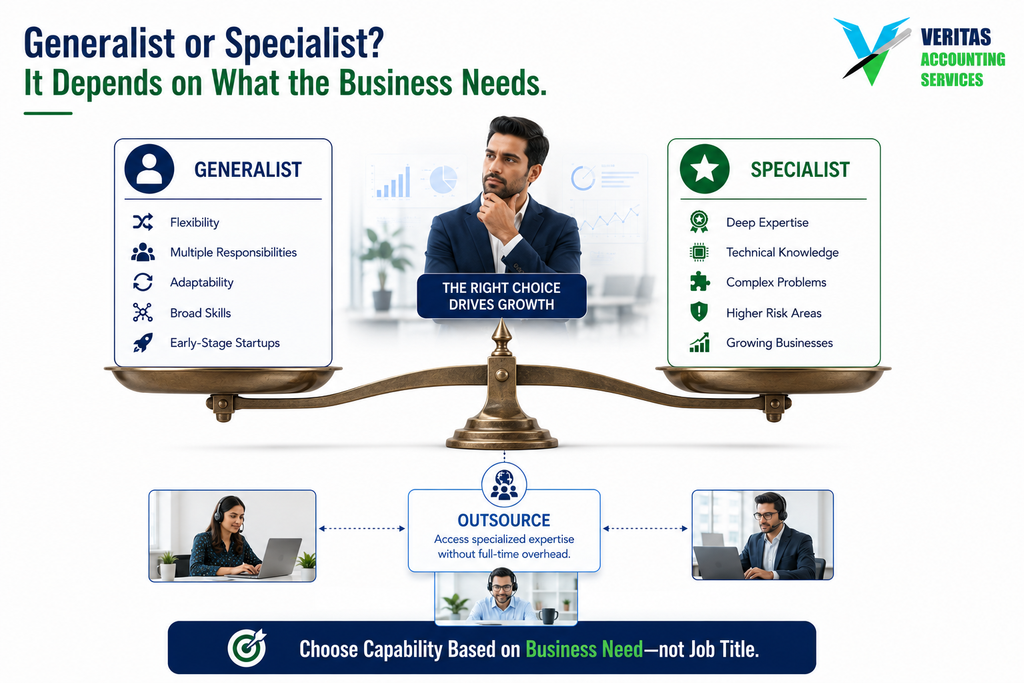
How Many Orders Does Your Business Need to Break Even?

A practical framing-shop example shows how to calculate the orders needed to cover costs and test a…

What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records

A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…

Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Connect on our Socials!

AI in ecommerce

How AI Is Reshaping Ecommerce—and Why Professionals Matter

Artificial intelligence is changing how people discover products, compare options, make purchases, and interact with online businesses. From personalized recommendations to automated customer support, technology is becoming an important part of modern ecommerce.

The growth of AI in ecommerce is not simply about adding new technology to an online store. The bigger opportunity is using technology to improve profitability, customer experience, operational efficiency, financial planning, and long-term business growth.

Understanding AI in ecommerce therefore requires more than understanding what AI can do. Businesses also need professionals who can determine where technology creates value, where it creates risk, and how it should be integrated into the broader business strategy.

How AI in Ecommerce Is Changing Online Shopping

Traditional online shopping required customers to search through categories, compare products, read descriptions, and make purchasing decisions largely on their own.

AI in ecommerce is changing this experience.

AI-powered platforms can analyze customer behavior and provide personalized product recommendations, smarter search results, automated assistance, and more relevant shopping experiences.

For example, a customer who frequently purchases office supplies may receive recommendations based on previous purchases, browsing behavior, and related products.

This can make shopping faster and more convenient.

However, businesses should not measure success simply by asking whether AI increased the number of recommendations.

They should ask whether AI in ecommerce is improving conversion rates, average order value, customer satisfaction, retention, and profitable revenue.

That is where professional analysis becomes valuable.

Personalization Can Increase Customer Value

One of the biggest opportunities created by AI in ecommerce is personalization.

Businesses can analyze information such as:

  • Previous purchases
  • Browsing behavior
  • Product preferences
  • Search activity
  • Customer interactions
  • Purchase frequency
  • Shopping patterns

This information can help businesses present products that are more relevant to individual customers.

For example, an ecommerce store selling electronics may recognize that a customer who purchased a laptop could also need a laptop bag, docking station, or accessories.

The opportunity is not simply to sell more.

It is to understand customer needs and provide a more useful shopping experience.

Professionals can help businesses determine whether personalization is actually increasing customer value or simply increasing marketing and technology costs.

AI Can Support Better Pricing Decisions

Pricing is another area where AI in ecommerce can influence business decisions.

Businesses can analyze demand, historical sales, competitor activity, customer behavior, and product performance to identify potential pricing opportunities.

However, businesses should be careful about changing prices simply because an algorithm recommends doing so.

A higher price may increase revenue per transaction but reduce sales volume.

A discount may increase order volume but reduce profit margins.

A financial professional can help management evaluate the complete impact.

The important question is not:

“Will this increase sales?”

The better question is:

“Will this improve profitable growth?”

This distinction becomes particularly important when businesses use AI in ecommerce for pricing and promotional decisions.

Better Demand Forecasting and Inventory Management

Inventory is one of the biggest challenges for ecommerce businesses.

Too much inventory can tie up working capital.

Too little inventory can create stockouts, missed sales, and disappointed customers.

AI in ecommerce can help analyze historical sales, seasonal trends, customer behavior, and other available information to improve demand forecasting.

But forecasting is not only an operational issue.

It is also a financial issue.

Finance professionals can help businesses understand how inventory decisions affect:

  • Cash flow
  • Working capital
  • Profit margins
  • Storage costs
  • Purchasing requirements
  • Financing needs

For example, a product may generate strong sales but require substantial working capital.

Another product may have lower sales but significantly higher margins.

AI can identify patterns, while professionals can help management understand what those patterns mean financially.

AI Can Improve Customer Service

Customer service is another area where AI in ecommerce can provide practical benefits.

AI-powered chatbots and virtual assistants can handle many routine customer questions.

They can assist with:

  • Product information
  • Order status
  • Shipping questions
  • Returns
  • Frequently asked questions
  • Basic troubleshooting

This can reduce repetitive work for customer service teams and provide faster responses to customers.

However, businesses should evaluate more than the number of inquiries handled by AI.

They should also measure:

  • Customer satisfaction
  • Resolution rates
  • Employee productivity
  • Cost savings
  • Customer retention
  • Revenue impact

Professionals can help determine whether AI in ecommerce is actually creating measurable business value.

Understanding Customer Behavior Through Data

Modern ecommerce businesses generate enormous amounts of data.

Information can come from:

  • Ecommerce platforms
  • Payment processors
  • Advertising platforms
  • Customer relationship systems
  • Websites
  • Email campaigns
  • Social media

AI in ecommerce can help identify patterns within this information.

For example, businesses may discover:

  • Which products perform best
  • Which customers purchase repeatedly
  • Which campaigns generate profitable sales
  • Which products are losing demand
  • Which customers may stop purchasing
  • Which channels produce better returns

But data alone does not create good decisions.

Professionals need to interpret the information and connect it with financial and strategic objectives.

How Professionals Contribute to AI-Driven Ecommerce Growth

Technology can process information quickly, but professionals bring context, experience, judgment, and accountability.

This combination is where AI in ecommerce becomes much more powerful.

Accountants Help Measure Profitability

An ecommerce business can generate impressive sales and still struggle to produce healthy profits.

Accountants help businesses understand:

  • Revenue
  • Cost of goods sold
  • Gross profit
  • Operating expenses
  • Marketplace fees
  • Advertising costs
  • Shipping expenses
  • Refunds
  • Returns
  • Cash flow

This becomes especially important when businesses invest in AI tools.

AI software may reduce labor costs, improve conversion rates, or increase sales, but the business still needs to know whether the overall financial result justifies the investment.

Accounting provides that visibility.

Financial Professionals Help Evaluate AI Investments

The implementation of AI in ecommerce may require investments in software, integration, employee training, consulting, and ongoing subscriptions.

A financial professional can help management evaluate:

  • Initial investment
  • Expected revenue improvement
  • Cost savings
  • Payback period
  • Return on investment
  • Cash flow requirements
  • Potential risks

For example, an AI solution might increase sales by 10%, but if implementation costs and operating expenses increase significantly, the actual financial benefit may be much smaller.

Professional financial analysis helps management look beyond headline revenue numbers.

Ecommerce Professionals Improve Commercial Performance

Ecommerce specialists understand the customer journey and commercial performance of an online store.

They can analyze:

  • Conversion rates
  • Average order value
  • Customer acquisition cost
  • Repeat purchases
  • Customer lifetime value
  • Cart abandonment
  • Product performance

AI in ecommerce can provide additional insights, but ecommerce professionals help determine which insights should influence the customer experience.

Their role is to connect technology with actual commercial objectives.

Marketing Professionals Turn AI Data Into Action

AI can analyze large amounts of marketing data quickly.

Marketing professionals can use these insights to improve:

  • Audience segmentation
  • Advertising campaigns
  • Email marketing
  • Content strategy
  • Product positioning
  • Promotions
  • Customer engagement

For businesses using AI in ecommerce, the professional’s role is to combine technological capabilities with market knowledge and brand strategy.

AI may identify that a particular customer segment responds strongly to a product.

A marketing professional can then determine how to communicate with that audience while protecting the company’s brand and profitability.

Operations Professionals Make AI Practical

AI implementation can fail when businesses focus on technology without redesigning their processes.

Operations professionals can help determine:

  • Which tasks should be automated
  • Which processes need human review
  • Where employees should use AI
  • How workflows should change
  • How quality should be monitored
  • How different systems should connect

The goal should not be to automate everything.

The goal should be to remove unnecessary manual work while maintaining quality and control.

This makes professional oversight an important part of successful AI in ecommerce implementation.

AI Should Support Judgment, Not Replace It

One of the biggest risks businesses face is assuming that an AI-generated recommendation must be correct.

AI depends heavily on the quality of the data and assumptions behind the analysis.

Poor data can produce poor recommendations.

Incomplete information can create misleading conclusions.

Professionals can challenge AI-generated results by asking:

  • Is the data reliable?
  • Are the assumptions reasonable?
  • What information is missing?
  • What risks have been overlooked?
  • What happens under a different scenario?
  • Does the recommendation make financial sense?

This human review remains important even as AI in ecommerce becomes more capable.

The Financial Side of AI Adoption

Before implementing AI in ecommerce, businesses should evaluate the complete financial picture.

Initial Costs

Consider software, implementation, integration, consulting, and employee training.

Ongoing Costs

Include subscriptions, maintenance, support, data storage, and system upgrades.

Productivity Gains

Measure how much employee time can actually be saved.

Revenue Opportunities

Evaluate potential improvements in conversion, average order value, repeat purchases, and customer retention.

Cost Reduction

Identify whether AI can reduce repetitive work, errors, or operating expenses.

Risk Reduction

Consider whether better forecasting, controls, and data analysis can reduce financial and operational risk.

A professional can help bring these factors together and determine whether the investment is justified.

AI in Ecommerce and Better Decision-Making

The strongest opportunity is not choosing between AI and professionals.

It is combining both.

Think of the relationship this way:

AI → Processes information

Professionals → Interpret information

Management → Makes decisions

Business → Takes action

AI can make analysis faster and more scalable.

Professionals can make that analysis more meaningful.

Management can then use the combined information to decide where to invest, what to change, and how to grow.

This is the real business opportunity behind AI in ecommerce.

Start With Business Problems, Not Technology

Businesses do not need to implement every AI solution available.

Instead, begin with specific business problems.

Ask:

  1. Where are we losing time?
  2. Where are customers experiencing friction?
  3. Which processes are repetitive?
  4. Where do we lack useful information?
  5. Which products generate the strongest margins?
  6. Where could better forecasting help?
  7. Which decisions require better financial analysis?

Then determine whether AI in ecommerce can provide a practical solution.

This prevents technology from becoming the objective.

The objective should always be better business performance.

The Future of Ecommerce Will Be More Intelligent

Online shopping will continue to become more personalized, automated, and data-driven.

Customers will expect:

  • Faster answers
  • Better recommendations
  • Easier purchasing
  • More personalized experiences
  • Faster service

Businesses will therefore need to adapt.

But successful adaptation does not mean adopting every new technology.

Companies need to understand profitability, processes, controls, customer behavior, and strategy before making major investments in AI in ecommerce.

That is why professional expertise continues to matter.

The Competitive Advantage of Combining AI and Expertise

AI can provide speed and scale.

Professionals provide experience and judgment.

Together, they can help ecommerce businesses:

  • Improve profitability
  • Understand customer value
  • Reduce unnecessary costs
  • Forecast demand
  • Improve cash flow
  • Make better pricing decisions
  • Strengthen operations
  • Evaluate investments
  • Identify new growth opportunities

When AI in ecommerce is combined with the right professional expertise, technology becomes more than an automation tool.

It becomes a business decision-support system.

Final Thoughts

AI is reshaping ecommerce, but technology alone does not create sustainable growth.

The real advantage comes from combining AI capabilities with professional expertise.

Accountants can measure profitability.

Financial professionals can evaluate investments and cash flow.

Ecommerce professionals can improve customer value and commercial performance.

Marketing professionals can turn data into stronger campaigns.

Operations professionals can create more efficient workflows.

Business advisors can connect these areas to strategic decisions.

AI in ecommerce can provide speed, scale, and information.

Professionals provide context, judgment, and accountability.

Together, they can help ecommerce businesses move from simply adopting AI to using it intelligently for profitable growth.

The future of ecommerce is not AI versus professionals.

It is AI working with professionals to make better business decisions.

Frequently Asked Questions

How is AI in ecommerce changing online shopping?

AI in ecommerce is changing product recommendations, search, customer service, pricing analysis, demand forecasting, and personalization.

Can AI in ecommerce improve profitability?

Yes. AI can help identify opportunities involving pricing, inventory, marketing, customer value, and operational efficiency. Professionals should evaluate whether those improvements actually increase profitability.

Why do ecommerce businesses need accountants?

Accountants help businesses understand revenue, costs, margins, marketplace fees, cash flow, and overall financial performance. This information is essential when evaluating AI investments.

Should every ecommerce business invest heavily in AI?

No. Businesses should first identify specific problems and determine whether an AI solution can provide enough value to justify its cost and complexity.

How can professionals work with AI?

Professionals can use AI to analyze information faster while applying human judgment to evaluate results, identify risks, and make practical business recommendations.

GET IN TOUCH

Schedule a FREE Call
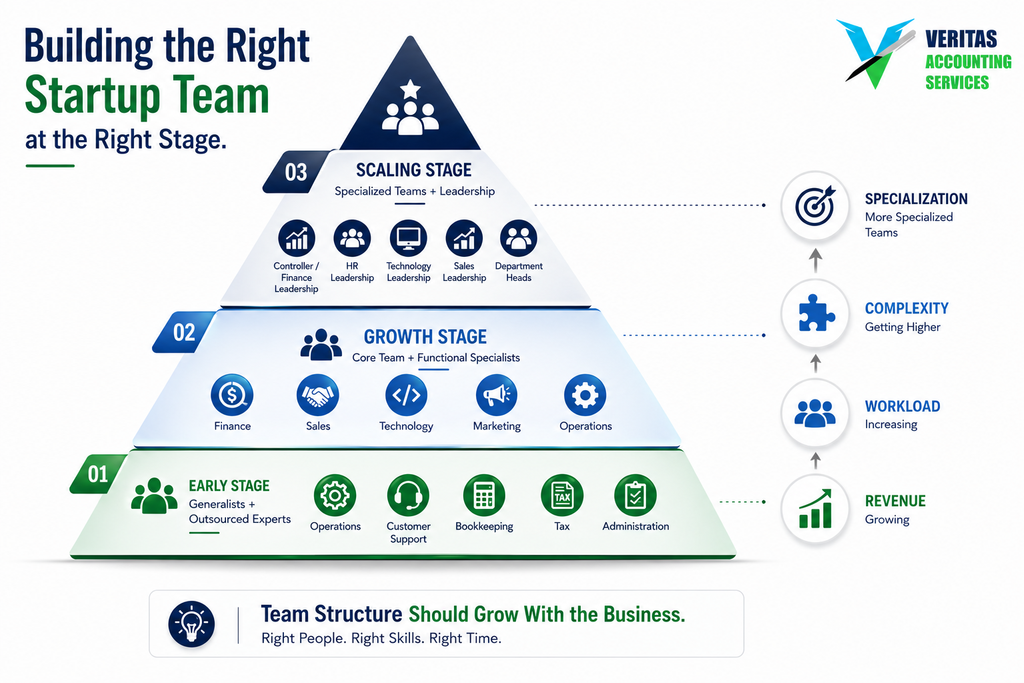
How Many Orders Does Your Business Need to Break Even?

A practical framing-shop example shows how to calculate the orders needed to cover costs and test a…

What to Do When You Pay for Business Expenses Personally

A practical guide to documenting business purchases you paid for personally, matching any repayment…

When the Bank Balance and Your Books Disagree

A practical month-end walkthrough for comparing your bank statement and books, with a worked example…

Vendor Bills and a Simple Routine for Better Cash Planning

A practical weekly routine for checking supplier bills, planning the payment batch and matching what…

Tax Bracket Mistakes: A Simple Guide to Better Planning

The November 5 IRS inflation update is a prompt to review your planning assumptions. Learn how…

Your Simple Guide to PTIN Renewal Mistakes and Better Records

The November 4 IRS reminder is a timely prompt to check 2027 preparer renewals, separate enrolled…

Inventory Tax Mistakes: A Simple Guide to Better Records

Stock purchases do not automatically equal a tax deduction. Review the inventory method, quantities…

Payroll Deposit Mistakes: A Simple Guide to Better Records
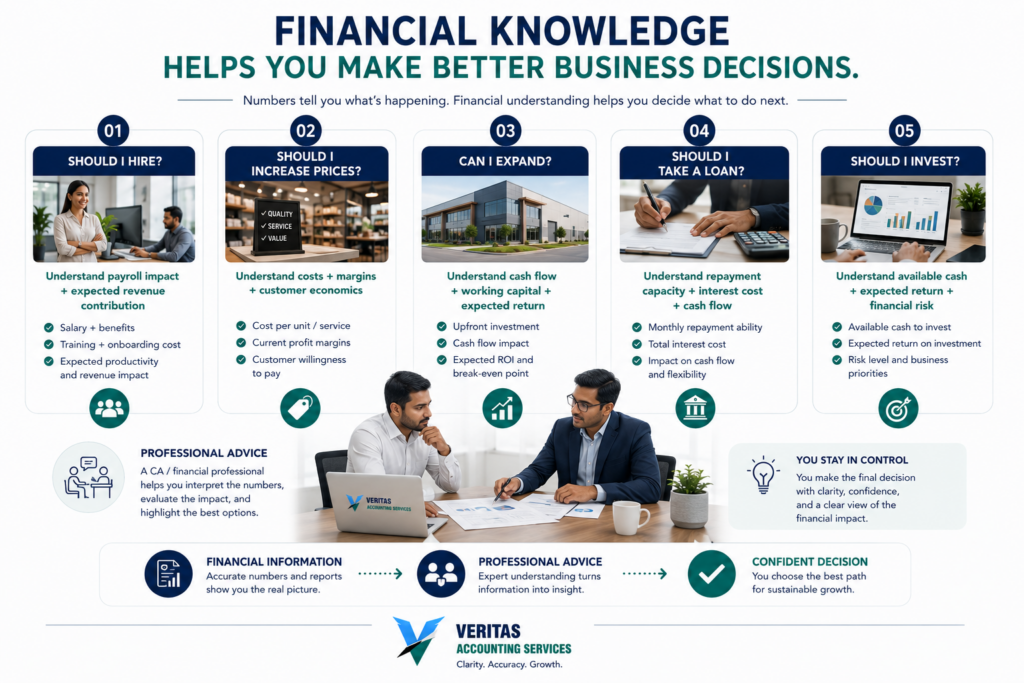
A quarterly payroll return does not set every tax deposit deadline. Check the schedule, actual pay…
Your Simple Guide to Home Office Mistakes and Better Records

Working from home does not automatically create a deduction. Check eligibility, space, dates…

Connect on our Socials!