Every year, thousands of business owners walk into their accountant’s office hoping for one thing:
“Can we reduce this year’s tax bill?”
Unfortunately, the answer is often disappointing.
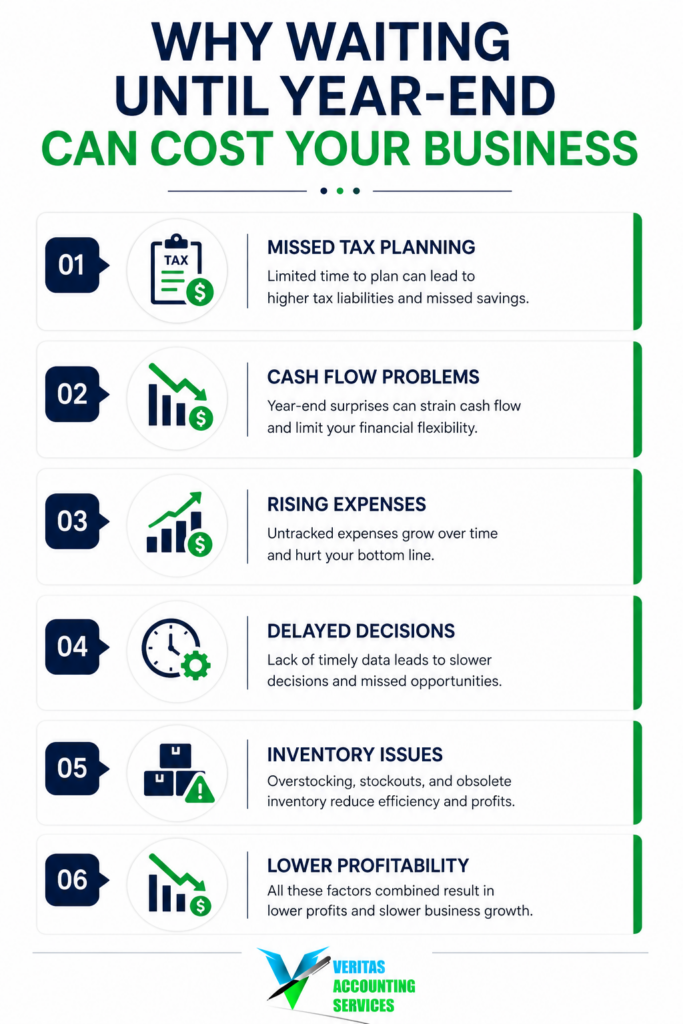
By the time the financial year has ended, most opportunities to reduce taxes have already disappeared.
Many business owners believe they are paying too much tax because tax rates are high.
The reality is often very different.
They aren’t paying more because of tax laws.
They’re paying more because they never had a tax strategy.
This is where tax planning becomes one of the most valuable financial tools available to any business.
Unlike tax filing, which records what has already happened, tax planning focuses on making better financial decisions throughout the year. It helps businesses legally minimize tax liabilities, improve cash flow, and make smarter investment decisions before deadlines arrive.
The biggest tax savings rarely happen in March, April, or during the filing season.
They happen months earlier.
Whether you’re a startup, a growing SME, an e-commerce business, or an established company, proactive tax planning can significantly improve your financial position while keeping your business fully compliant.
In this article, we’ll explain why businesses often overpay taxes, the difference between tax filing and tax planning, and the strategies successful businesses use to keep more of their hard-earned profits.
Tax Filing and Tax Planning Are Not the Same Thing
One of the biggest misconceptions among business owners is believing that filing taxes and tax planning are the same service.
They are not.
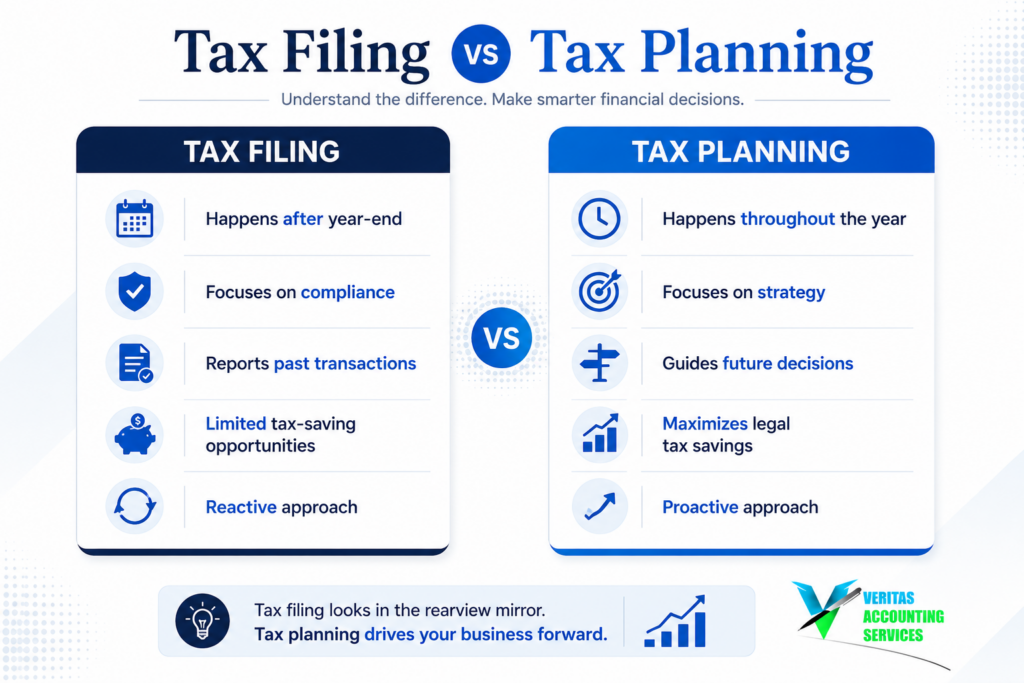
Tax filing is a compliance activity.
Tax planning is a strategic activity.
Tax filing focuses on preparing accurate tax returns based on transactions that have already occurred.
Tax planning focuses on influencing those transactions before they happen.
Think of it this way.
Tax filing looks in the rear-view mirror.
Tax planning looks through the windshield.
Once the financial year has ended, your accountant can only calculate the tax based on the information available.
Very little can be changed.
However, when tax planning takes place throughout the year, businesses have time to make informed financial decisions that can legally reduce their tax burden.
These decisions may include:
Timing major purchases
Choosing the right business structure
Managing depreciation claims
Planning dividend distributions
Utilizing available deductions and credits
Forecasting taxable income
Structuring owner compensation efficiently
This is why effective tax planning creates opportunities that tax filing simply cannot.
Veritas Expert Insight
The best tax savings don’t happen when your tax return is prepared. They happen months before the financial year ends through proactive planning and informed financial decisions.
Why Most Businesses End Up Paying More Tax
Many businesses don’t intentionally ignore tax planning.
They’re simply too busy running daily operations.
Sales.
Customer service.
Hiring.
Inventory.
Marketing.
Cash flow.
Tax planning often gets postponed until the accountant requests financial records.
Unfortunately, that’s exactly when it’s too late.
One of the biggest advantages of proactive tax planning is having enough time to make financial decisions that affect taxable income before the year closes.
Without that planning, businesses often:
Miss legitimate deductions
Delay important investments
Purchase assets at the wrong time
Pay unnecessary penalties
Lose available tax benefits
Make inefficient compensation decisions
These missed opportunities can cost thousands of dollars every year.
Good tax planning is not about avoiding taxes.
It’s about understanding the rules and using them effectively.
Businesses that plan ahead usually retain more cash, improve profitability, and gain greater financial flexibility.
1. Waiting Until Tax Season
One of the biggest tax mistakes businesses make is treating tax planning as a once-a-year activity.
By the time tax season arrives, your income has already been earned.
Expenses have already been incurred.
Investment decisions have already been made.
At that stage, your accountant is primarily reporting history—not creating tax-saving opportunities.
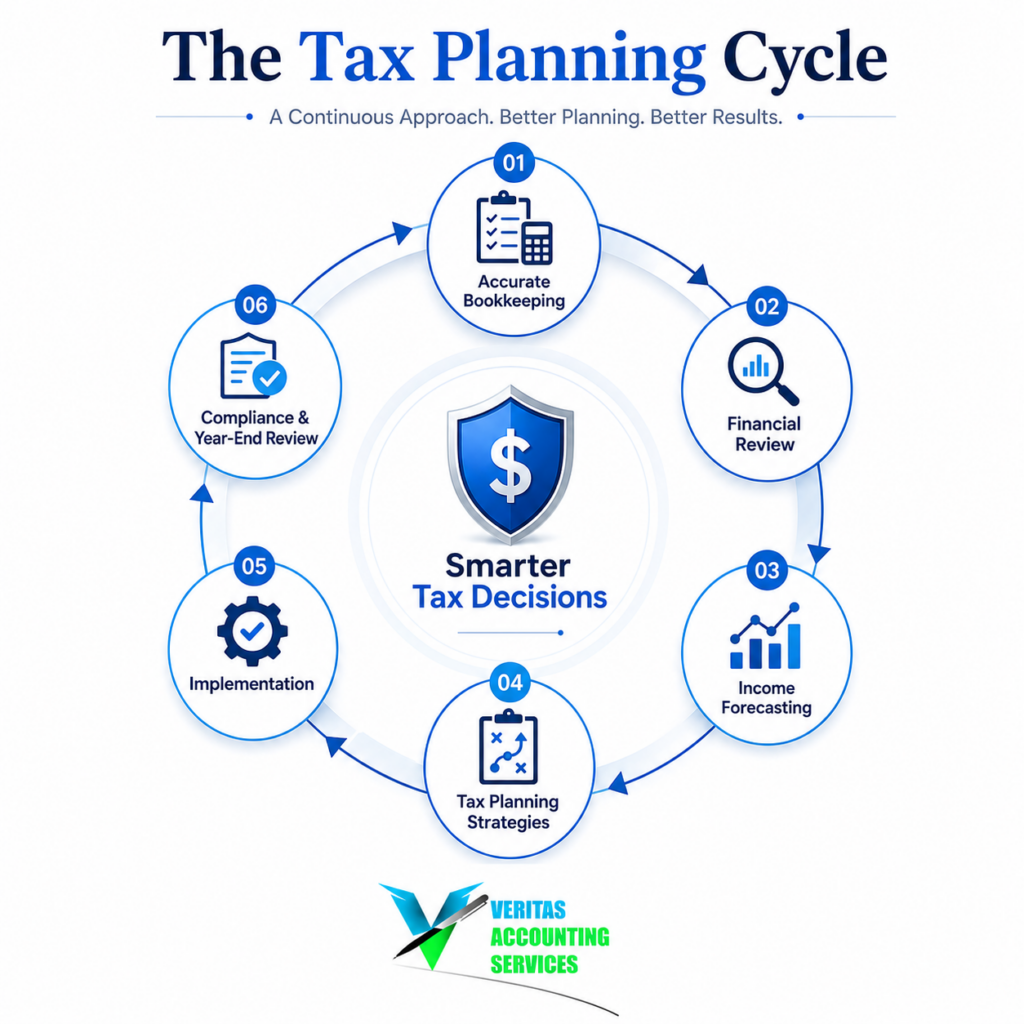
Successful businesses understand that tax planning is a continuous process.
They review financial performance throughout the year, estimate taxable income regularly, and adjust business decisions before deadlines arrive.
This proactive approach provides greater control over tax liabilities while reducing year-end surprises.
2. Poor Record Keeping Leads to Lost Deductions
Accurate bookkeeping is the foundation of successful tax planning.
Without reliable financial records, businesses struggle to identify deductible expenses, monitor profitability, and prepare accurate tax returns.
Missing invoices.
Incomplete expense records.
Unreconciled bank accounts.
Poor documentation.
All of these increase the likelihood of missed deductions and unnecessary tax payments.
Proper bookkeeping doesn’t just help during tax season.
It supports effective tax planning throughout the year by providing reliable financial information for better decision-making.
3. Choosing the Wrong Business Structure
Many entrepreneurs select a business structure when starting their company and never review it again.
As the business grows, that structure may no longer be the most tax-efficient option.
Depending on the country and applicable tax laws, operating as a sole proprietor, partnership, limited liability company, or corporation can produce very different tax outcomes.
A periodic review helps ensure that the business structure continues to align with operational needs, profitability, and long-term goals.
This is another area where strategic tax planning can generate substantial savings.
4. Ignoring Timing Differences
Timing plays a significant role in taxation.
The same business transaction can produce different tax consequences depending on when it occurs.
For example:
Purchasing equipment before year-end may accelerate depreciation deductions.
Deferring certain income may shift taxable profits into a later period where appropriate.
Paying eligible business expenses before year-end may increase allowable deductions.
These decisions are rarely accidental.
They are the result of proactive tax planning supported by accurate financial forecasting.
Business owners who understand timing strategies often create meaningful tax savings without changing their overall business operations.
5. Making Decisions Without Financial Forecasts
Many businesses prepare budgets but never estimate future taxable income.
Without forecasts, it becomes difficult to identify potential tax liabilities until they have already occurred.
Forecasting allows management to estimate profits, evaluate investment decisions, and prepare for upcoming tax obligations well before payment deadlines.
This makes tax planning significantly more effective.
Instead of reacting to tax bills, businesses begin managing them strategically.
Forecasting also improves cash flow because taxes become predictable rather than unexpected. 6. Smart Tax Planning Starts with Accurate Bookkeeping
Many business owners think tax planning begins when they meet their accountant.
In reality, tax planning begins with accurate bookkeeping.
Every business decision relies on reliable financial data. If your books are incomplete, transactions are misclassified, or bank accounts haven’t been reconciled, it becomes difficult to identify legitimate tax-saving opportunities.
Good bookkeeping provides the foundation for effective tax planning.
It allows businesses to:
Monitor deductible expenses throughout the year.
Track profitability accurately.
Estimate taxable income regularly.
Identify unusual expenses before year-end.
Prepare for tax obligations without surprises.
Without accurate records, even the best tax advisor has limited options.
This is why businesses that maintain clean financial records are usually in a much stronger position to benefit from proactive tax planning.
7. Cash Flow and Tax Planning Go Hand in Hand
One of the biggest misconceptions is that tax planning is only about reducing taxes.
Good tax planning also improves cash flow.
Unexpected tax liabilities often create financial pressure because businesses haven’t planned for them.
When tax obligations are estimated throughout the year, management can:
Set aside sufficient funds.
Avoid borrowing to pay taxes.
Improve budgeting.
Make investment decisions with confidence.
Maintain healthy working capital.
Cash flow problems rarely happen overnight.
They develop when businesses fail to anticipate future obligations.
Strategic tax planning helps eliminate those surprises by making taxes part of the financial planning process rather than a last-minute emergency.
8. A Virtual CFO Makes Tax Planning More Effective
Tax planning shouldn’t happen in isolation.
It works best when combined with budgeting, forecasting, cash flow management, and financial reporting.
This is where a Virtual CFO creates significant value.
Instead of focusing only on tax compliance, a Virtual CFO helps business owners understand how every major financial decision affects profitability, cash flow, and future tax obligations.
A Virtual CFO regularly reviews:
Revenue forecasts
Profitability trends
Capital expenditure plans
Business expansion
Owner compensation
Cash flow projections
Working capital requirements
These insights allow businesses to make informed decisions before the financial year ends.
Effective tax planning is no longer just about filing returns.
It becomes part of an overall financial strategy that supports sustainable business growth.
Veritas Expert Insight
The most successful businesses don’t wait until tax season to discuss taxes. They make tax planning part of every major financial decision throughout the year.
9. Common Tax Planning Mistakes That Cost Businesses Money
Even profitable businesses make avoidable mistakes that increase their tax liability.
Some of the most common include:
Waiting Until Year-End
By the time the financial year closes, many tax-saving opportunities are no longer available.
Mixing Personal and Business Expenses
Poor separation creates bookkeeping errors, increases compliance risks, and makes tax planning less effective.
Ignoring Business Growth
As businesses grow, their tax strategy should evolve.
A structure that worked during the startup phase may no longer be the most tax-efficient.
Failing to Review Financial Statements
Business owners often review financial reports only when required by lenders or tax authorities.
Regular reviews provide valuable insights that improve tax planning throughout the year.
Assuming Compliance Equals Strategy
Submitting tax returns on time is important.
However, compliance alone does not create tax savings.
Strategic tax planning goes far beyond filing deadlines.
Tax Planning Is a Competitive Advantage
Businesses that invest in tax planning don’t simply pay less tax.
They make better financial decisions.
They improve cash flow.
They allocate capital more efficiently.
They invest with greater confidence.
They avoid unnecessary financial stress.
Perhaps most importantly, they gain greater control over their future.
Every dollar legally saved through effective tax planning is a dollar that can be reinvested into the business.
That could mean hiring new employees, expanding into new markets, purchasing equipment, investing in technology, or strengthening cash reserves.
Tax planning is not about finding loopholes.
It is about understanding the law, planning ahead, and making informed financial decisions that support long-term success.
Final Thoughts
Many business owners believe they are paying too much tax.
In reality, the problem often isn’t the amount of tax they pay.
The problem is the absence of a proactive tax strategy.
Waiting until tax season limits your options.
Planning throughout the year creates opportunities.
It transforms taxation from a year-end obligation into an ongoing business strategy.
At Veritas Accounting Services, we work closely with business owners to develop practical tax planning strategies that align with their financial goals.
From bookkeeping and financial reporting to forecasting and advisory services, our focus is not only on compliance but also on helping businesses make smarter financial decisions throughout the year.
Because successful businesses don’t leave tax savings to chance.
They plan for them.
Ready to Build a Smarter Tax Strategy?
If your business only thinks about taxes during filing season, you’re probably missing valuable opportunities to improve cash flow and reduce your tax liability.
At Veritas Accounting Services, we help businesses move beyond compliance with proactive tax planning, accurate bookkeeping, and strategic financial advisory services.
Running a business is demanding. Every day brings new decisions—winning customers, managing employees, controlling operations, and finding ways to grow. Most business owners naturally spend their time focusing on sales, customer satisfaction, and expansion. While these priorities are essential, they often leave little time to step back and analyze the financial health of the business.
This is where the perspective changes.
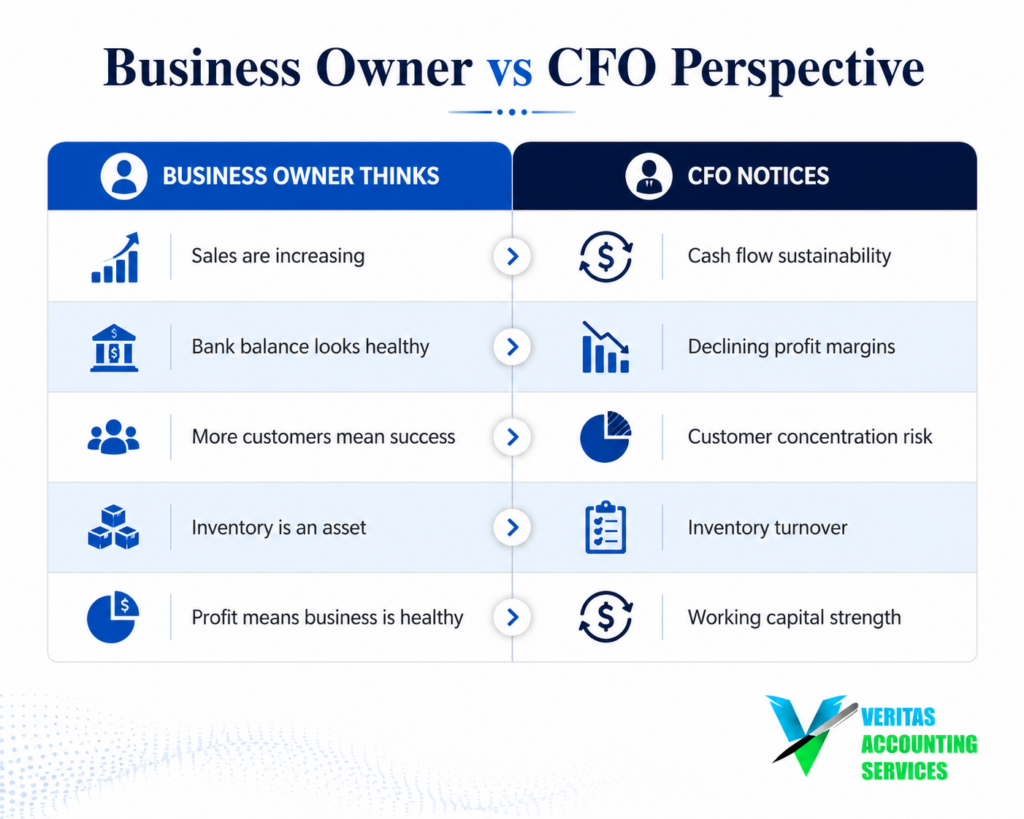
A business owner usually asks, “Are we making money?”
A Chief Financial Officer asks, “Will this business still be financially strong six months from now?”
That difference in thinking is what makes CFO insights so valuable. Rather than looking only at revenue or bank balances, CFO insights uncover hidden trends, financial risks, and opportunities that influence the long-term success of a business.
Many companies don’t fail because they lack customers or innovative ideas. They struggle because important financial warning signs go unnoticed until they become serious problems. The numbers were always there—but no one interpreted them correctly.
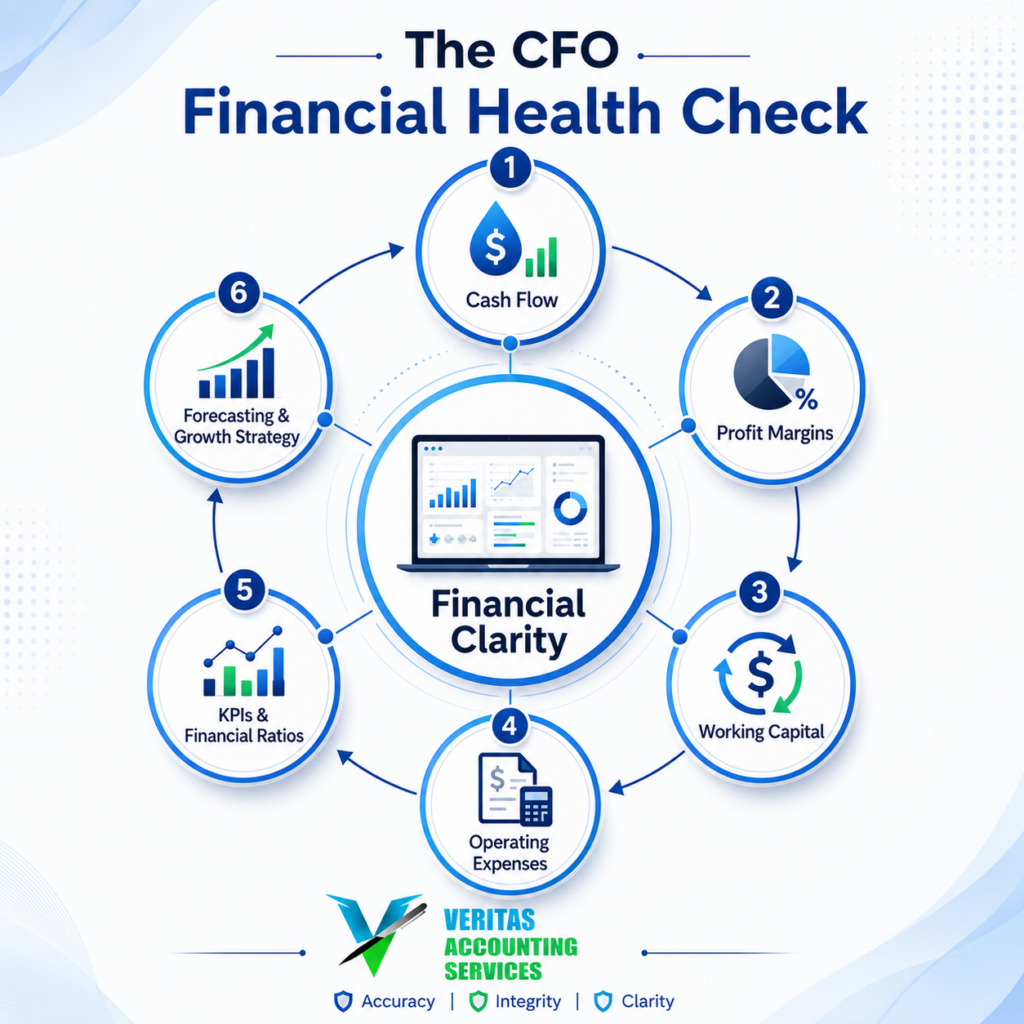
Experienced CFOs don’t rely on guesswork. They evaluate financial statements, operational trends, and key performance indicators to understand what is really happening behind the scenes. Their ability to connect different financial metrics allows them to identify risks long before they appear on a profit and loss statement.
Whether you own a startup, an e-commerce business, a manufacturing company, or a professional services firm, understanding these CFO insights can help you make smarter business decisions and avoid costly mistakes.
Let’s look at the first things a CFO notices almost immediately.
Why Business Owners and CFOs See Businesses Differently
Entrepreneurs are naturally optimistic.
They focus on opportunities, new markets, customer relationships, and increasing revenue. Their attention is directed toward growing the business.
A CFO has a different responsibility.
Instead of asking how quickly the business can grow, they ask whether the business can grow sustainably.
For example, a business owner may celebrate a 30% increase in sales.
A CFO immediately wants to know:
Did profit margins improve?
Is cash flow keeping pace with growth?
Are operating expenses increasing faster than revenue?
Is the business becoming too dependent on one customer?
Will current working capital support future expansion?
These questions represent practical CFO insights that go beyond traditional bookkeeping. They reveal whether growth is creating long-term value or simply increasing financial pressure.
Business owners often look at individual numbers.
CFOs look at relationships between numbers.
That difference changes everything.
Veritas Expert Insight
Financial statements don’t just report what happened—they reveal what is likely to happen next. The ability to interpret those signals is what separates financial reporting from strategic financial leadership.
1. Cash Flow Always Comes Before Profit
One of the firstCFO insightsis understanding that revenue does not pay the bills.
Cash does.
Many businesses proudly report record sales while quietly struggling to meet payroll, pay suppliers, or invest in future growth.
How is that possible?
Because profit and cash are not the same thing.
Imagine a business that invoices customers for $500,000 during the month.
Its Profit & Loss Statement looks impressive.
However, most customers pay after 60 or 90 days.
Meanwhile, employee salaries, rent, inventory purchases, software subscriptions, taxes, and supplier invoices must all be paid immediately.
On paper, the business appears profitable.
In reality, cash is disappearing every week.
This is why experienced CFOs often review the Cash Flow Statement before looking at the income statement.
Strong CFO insights focus on questions such as:
How much cash is generated from operations?
Are customers paying on time?
Is working capital improving or declining?
How much cash is tied up in receivables?
Can the business comfortably fund future growth?
Businesses rarely close because sales suddenly stop.
More often, they fail because they run out of cash.
Understanding this distinction is one of the most valuable CFO insights any business owner can learn.
2. Revenue Growth Doesn’t Always Mean Better Performance
Higher revenue usually feels like success.
But experienced CFOs know that’s only part of the story.
Imagine two companies with identical annual sales.
Each generates $3 million in revenue.
At first glance, both businesses appear equally successful.
A deeper financial review tells a different story.
Company A maintains healthy gross margins, carefully manages expenses, and consistently improves profitability.
Company B wins more customers but offers larger discounts, experiences rising supplier costs, and spends significantly more on operations.
Revenue increases every quarter.
Profit decreases every quarter.
A business owner may celebrate the growing sales.
A CFO immediately identifies shrinking margins as an early warning sign.
These CFO insights help management understand whether growth is actually improving the financial position of the company.
Healthy businesses don’t simply sell more.
They earn more from every dollar of revenue.
When margins begin declining, experienced CFOs investigate the underlying reasons before profitability suffers.
Possible causes include:
Increased supplier costs
Aggressive discounting
Poor pricing strategies
Operational inefficiencies
Rising freight expenses
Higher employee costs
Finding these issues early gives businesses time to respond before financial performance deteriorates.
3. Expenses That Increase Quietly Every Month
Most businesses don’t experience financial problems because of one major expense.
Instead, profitability slowly declines through dozens of small increases.
A new software subscription.
Additional marketing campaigns.
Extra administrative staff.
Higher insurance premiums.
Growing travel expenses.
Professional service fees.
Individually, these costs seem reasonable.
Collectively, they begin reducing profit margins.
One of the most practical CFO insights is identifying expense trends rather than reviewing expenses individually.
Experienced CFOs compare monthly operating costs against revenue growth.
If expenses consistently rise faster than sales, long-term profitability becomes difficult to maintain.
This doesn’t necessarily mean costs should always be reduced.
Instead, every expense should generate measurable business value.
Strong financial leadership asks:
“Is this expense helping the business become more profitable?”
If the answer is unclear, it deserves closer attention.
4. Working Capital Reveals the Business’s Financial Strength
Many business owners focus primarily on profit.
A CFO focuses equally on liquidity.
Working capital measures whether a business has enough short-term resources to meet its financial obligations.
Healthy working capital allows businesses to pay suppliers, invest in growth, purchase inventory, and manage unexpected challenges without unnecessary financial pressure.
When reviewing financial statements, one of the first CFO insights involves evaluating:
Accounts Receivable collection periods
Inventory turnover
Supplier payment terms
Current assets versus current liabilities
Cash available for operations
A profitable business can still experience financial stress if too much money remains tied up in unpaid invoices or excess inventory.
Likewise, businesses with strong working capital often have greater flexibility to invest in new opportunities.
This is why CFOs monitor liquidity just as closely as profitability.
Strong cash management provides stability during both periods of growth and economic uncertainty.
5. Customer Concentration Can Become a Hidden Risk
Winning a large customer often feels like a significant achievement.
And it usually is.
However, experienced CFOs immediately ask another question:
“How dependent has the business become on that customer?”
Suppose one client generates 45% of total annual revenue.
If that customer changes suppliers, delays payments, reduces orders, or negotiates lower prices, the financial impact could be substantial.
Business owners often celebrate the revenue.
A CFO evaluates the risk behind that revenue.
One of the most valuable CFO insights is recognizing concentration risk before it becomes a serious problem.
When no single customer has excessive influence over financial performance, the business becomes more resilient and better prepared for unexpected market changes.
6. Inventory Can Be an Asset—or a Hidden Liability
Most business owners see inventory as a valuable asset because it represents products ready to be sold.
A CFO sees something different.
One of the most practical CFO insights is that inventory only creates value when it moves quickly. Inventory sitting in a warehouse for months ties up cash, increases storage costs, raises insurance expenses, and may eventually become obsolete.
When reviewing financial statements, a CFO immediately asks:
How many days does inventory remain in stock?
Which products haven’t sold in the last six months?
Are we buying faster than we’re selling?
How much cash is trapped in slow-moving inventory?
Suppose your balance sheet shows $500,000 in inventory.
That might sound impressive.
However, if nearly half of that inventory hasn’t moved for a year, it isn’t strengthening the business—it is reducing liquidity.
These CFO insights help businesses optimize purchasing decisions, improve inventory turnover, and release cash that can be invested in marketing, expansion, technology, or hiring.
Healthy inventory supports growth.
Excess inventory silently reduces profitability.
7. Debt Isn’t the Problem—Poor Debt Management Is
Many business owners worry whenever they see debt on the balance sheet.
A CFO doesn’t automatically see debt as negative.
Instead, they evaluate whether the debt is helping the business grow.
One of the most valuable CFO insights is understanding the purpose behind borrowing.
Debt used to purchase productive equipment, expand operations, or increase revenue may generate long-term value.
Debt used simply to pay monthly operating expenses usually signals a cash flow problem.
A CFO immediately evaluates questions like:
Can operating cash comfortably cover loan repayments?
Is the debt generating a measurable return?
Are interest expenses increasing every quarter?
Is borrowing replacing healthy cash flow?
Businesses often succeed because they use financing strategically.
Businesses struggle when debt becomes a substitute for profitability.
These CFO insights allow management to make smarter financing decisions before debt becomes a burden.
8. KPIs Tell the Story Behind the Financial Statements
Financial statements explain what happened.
Key Performance Indicators explain why it happened.
That is why experienced CFOs spend significant time reviewing KPIs instead of relying only on monthly profit reports.
Important KPIs include:
Gross Profit Margin
Net Profit Margin
Operating Cash Flow
Current Ratio
Accounts Receivable Days
Inventory Turnover
Customer Acquisition Cost
Customer Lifetime Value
EBITDA Margin
Operating Expense Ratio
Each KPI provides another layer of financial understanding.
For example, revenue may increase by 20%.
At first glance, that looks excellent.
However, if customer acquisition costs increase by 35% and gross margins decline, profitability may actually be weakening.
These are the kinds of CFO insights that help business owners move beyond surface-level reporting.
Instead of celebrating every increase in sales, they begin measuring whether growth is creating sustainable value.
Businesses that consistently monitor KPIs usually identify financial issues months before they become serious.
Veritas Expert Insight
Great financial decisions are rarely based on a single report. They come from combining accurate financial statements with meaningful KPIs, cash flow analysis, and forward-looking planning.
9. A CFO Focuses on the Future, Not Just the Past
Most accounting reports describe what has already happened.
A CFO uses those reports to predict what will happen next.
This forward-looking approach is one of the biggest differences between bookkeeping and strategic financial leadership.
Strong CFO insights are built around forecasting.
Instead of asking, “How did we perform last month?” a CFO asks:
What will cash flow look like three months from now?
Can the business afford planned hiring?
Will seasonal demand affect working capital?
Is expansion financially sustainable?
What happens if sales decline by 15%?
Scenario planning allows businesses to prepare for multiple outcomes rather than reacting when problems arise.
This proactive mindset helps organizations avoid financial surprises and make confident decisions.
The most successful businesses don’t simply report history.
They plan for the future.
Why Every Growing Business Benefits from CFO Insights
Many small and medium-sized businesses believe that hiring a CFO is something only large corporations can afford.
That is no longer true.
Today’s businesses face rising operating costs, economic uncertainty, changing tax regulations, increasing competition, and rapid technological change.
These challenges require more than accurate bookkeeping.
They require strategic financial guidance.
This is where CFO insights create real value.
A Virtual CFO helps business owners understand financial trends, improve profitability, strengthen cash flow, prepare realistic budgets, and develop long-term growth strategies.
Instead of making decisions based on instinct alone, business owners gain access to reliable financial analysis that supports confident decision-making.
The result is better planning, stronger financial control, and improved business performance.
Final Thoughts
Successful businesses are not built solely on higher sales or bigger profits.
They are built on informed decisions.
Every financial statement contains valuable information, but numbers alone never tell the complete story.
Interpreting those numbers correctly is what creates a competitive advantage.
The best CFO insights go beyond accounting.
They reveal hidden risks before they become expensive problems.
They uncover opportunities to improve profitability.
They strengthen cash flow.
They support sustainable growth.
Most importantly, they help business owners make decisions with confidence instead of assumptions.
At Veritas Accounting Services, we believe financial reports should do more than satisfy compliance requirements.
They should provide clear direction for the future.
Our Virtual CFO services help businesses transform financial data into meaningful CFO insights, empowering owners to improve performance, manage risk, and achieve long-term success.
Because the best business decisions begin with understanding what your numbers are really saying.
Frequently Asked Questions
What are CFO insights?
CFO insights are strategic financial observations that help business owners understand profitability, cash flow, operational efficiency, and financial risks beyond standard accounting reports.
Why are CFO insights important for small businesses?
Small businesses often focus on daily operations. CFO insights help identify hidden risks, improve financial planning, strengthen cash flow, and support better business decisions before problems become costly.
How often should businesses review financial performance?
Monthly financial reviews combined with regular cash flow monitoring and KPI analysis provide timely CFO insights that support informed decision-making.
What is the difference between bookkeeping and CFO services?
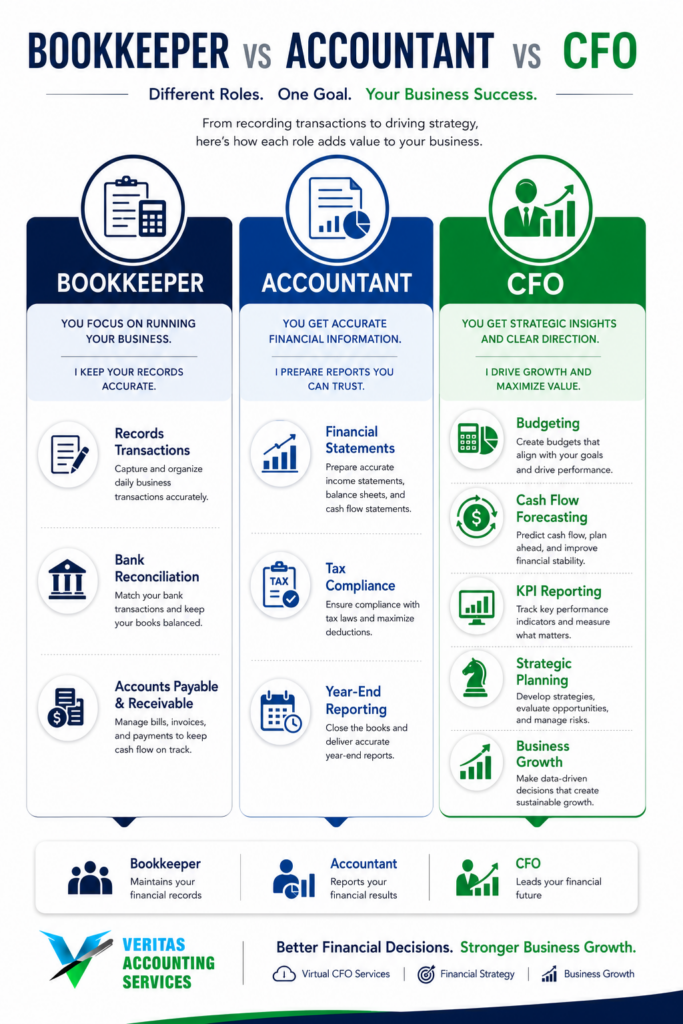
Bookkeeping records financial transactions and prepares reports. CFO services analyze those reports, provide CFO insights, develop financial strategies, forecast future performance, and advise management on growth and risk management.
Can a Virtual CFO help growing businesses?
Absolutely. A Virtual CFO provides experienced financial leadership, strategic planning, budgeting, forecasting, and valuable CFO insights without the cost of employing a full-time Chief Financial Officer.
Ready to Gain Expert CFO Insights?
If you’re making business decisions based only on revenue and bank balances, you could be missing opportunities to improve profitability and reduce financial risk.
At Veritas Accounting Services, our Virtual CFO solutions provide practical CFO insights that help business owners strengthen cash flow, improve financial performance, and build sustainable growth.
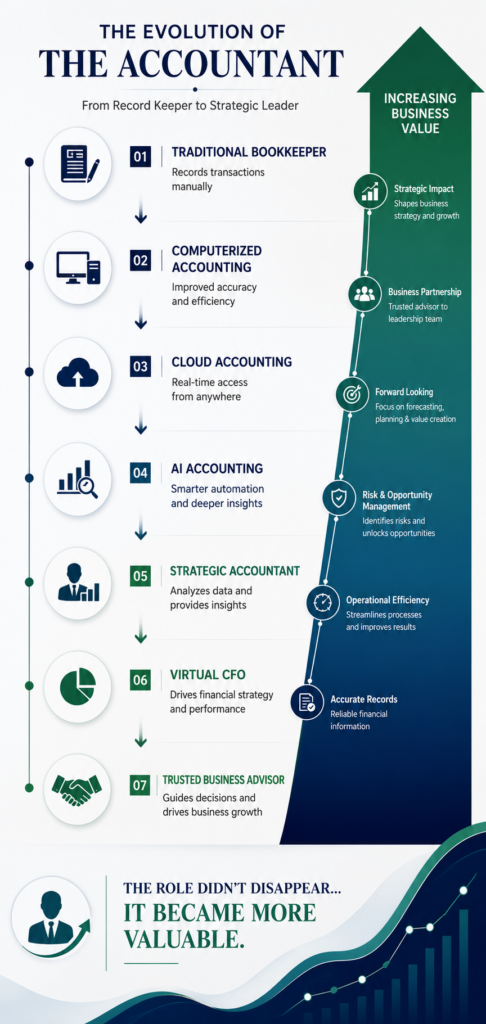
For decades, the accounting profession has evolved alongside technology. From spreadsheets replacing handwritten ledgers to cloud accounting transforming collaboration, every major innovation has sparked the same question: Will technology replace accountants?
Today, that question has resurfaced with artificial intelligence.
The rapid growth of AI accounting has generated excitement, curiosity, and concern in equal measure. Businesses are using AI-powered software to automate bookkeeping, process invoices, reconcile bank transactions, detect anomalies, and generate financial reports within seconds. As these tools become more sophisticated, many professionals wonder whether the role of the accountant is slowly disappearing.
The reality is very different.
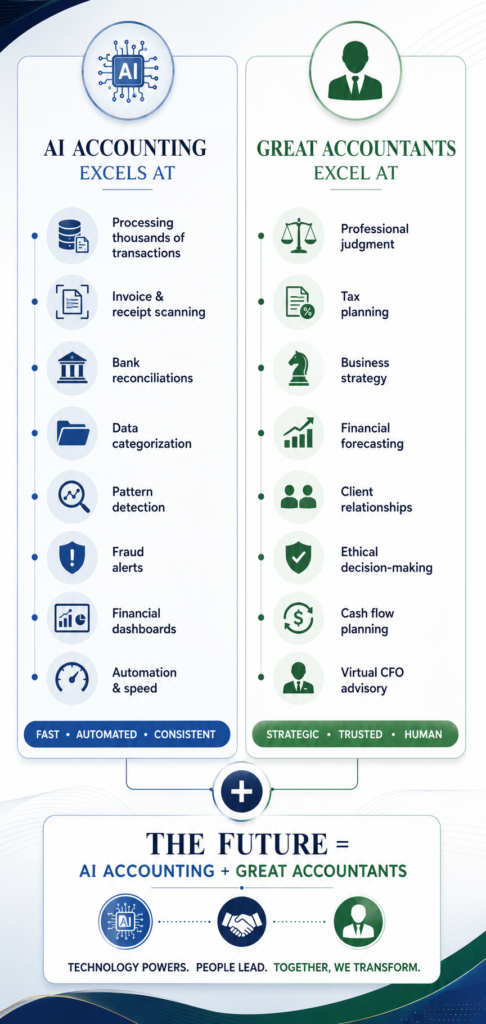
AI accounting is not replacing great accountants. It is replacing repetitive work that prevents accountants from delivering their highest value. Rather than making professionals obsolete, AI is reshaping the profession by allowing accountants to spend less time processing data and more time helping businesses make smarter financial decisions.
The firms and professionals who embrace AI accounting will become more productive, more strategic, and more valuable than ever before. Those who ignore technological change may struggle—not because artificial intelligence replaced them, but because competitors learned how to combine technology with professional expertise.
The future belongs to accountants who understand both numbers and business strategy.
In this article, we’ll explore why AI accounting is transforming the profession, what artificial intelligence can genuinely do, where its limitations remain, and why experienced accountants will continue to play a critical role in business success.
Why AI Accounting Is Creating So Much Discussion
Artificial intelligence has advanced at an extraordinary pace over the past few years.
Modern accounting platforms now incorporate machine learning, predictive analytics, and automation into everyday financial processes. What once required hours of manual effort can often be completed within minutes.
This rapid progress has naturally raised concerns within the profession.
Business owners see software performing bookkeeping tasks automatically.
Accounting firms see automation reducing administrative work.
Students entering the profession hear predictions that AI accounting will eventually eliminate accounting jobs altogether.
These headlines generate attention, but they rarely explain what is actually changing.
Technology has always automated routine work. Calculators replaced manual calculations. Spreadsheet software reduced paper-based bookkeeping. Cloud accounting simplified collaboration. Optical Character Recognition eliminated much of the manual data entry associated with invoices and receipts.
Each innovation changed the way accountants worked.
None of them eliminated the profession.
AI accounting represents another major step in that evolution.
Instead of replacing accountants, it changes where accountants create value.
The profession is moving away from transaction processing and toward business advisory, financial strategy, risk management, and decision support.
That shift should be viewed as an opportunity rather than a threat.
The Biggest Misconception About AI Accounting
One of the biggest misconceptions surrounding AI accounting is that accounting is simply about recording financial transactions.
In reality, bookkeeping is only one component of the profession.
Businesses don’t hire accountants merely to record expenses or prepare reports.
They rely on experienced professionals to answer questions such as:
Why is profit increasing while cash flow is declining?
Can the business afford to expand this year?
Which expenses should be reduced first?
How can tax liabilities be managed legally and efficiently?
What financial risks should management address immediately?
These questions require judgment, commercial awareness, and practical experience.
Artificial intelligence can provide information.
It cannot fully understand a company’s long-term objectives, risk appetite, industry challenges, or the personal priorities of business owners.
That difference is significant.
Technology produces information.
Great accountants transform that information into better business decisions.
Veritas Expert Insight
AI accounting should be viewed as a productivity tool rather than a replacement for professional expertise. Businesses still need accountants who can interpret financial information, provide strategic guidance, and help leaders make informed decisions.
What AI Accounting Already Does Better Than Humans
To understand where the profession is heading, accountants must first acknowledge where artificial intelligence already excels.
Ignoring these capabilities does not protect the profession.
Understanding them does.
1. Transaction Processing
One of the greatest strengths of AI accounting is processing large volumes of financial transactions quickly and consistently.
Instead of manually reviewing every expense, modern systems can categorize transactions based on historical patterns, vendor information, and predefined accounting rules.
This dramatically reduces repetitive bookkeeping work while improving efficiency.
2. Invoice and Receipt Processing
AI-powered document recognition has transformed one of the most time-consuming accounting tasks.
Invoices, bills, and receipts can now be scanned automatically.
Key information—including supplier names, invoice dates, tax amounts, and payment details—is extracted within seconds.
Rather than entering data manually, accountants simply review exceptions and verify unusual transactions.
3. Bank Reconciliations
Bank reconciliations have traditionally required careful matching of deposits, withdrawals, transfers, and outstanding transactions.
AI accounting platforms can automatically match thousands of transactions using predefined rules and historical behavior.
Instead of spending hours comparing bank statements line by line, accountants can focus on investigating genuine discrepancies.
4. Identifying Patterns
Artificial intelligence is exceptionally effective at recognizing patterns hidden within large datasets.
For example, AI accounting systems can quickly identify:
Duplicate payments
Unusual vendor activity
Missing invoices
Abnormal spending trends
Cash flow irregularities
Potential fraud indicators
These insights help accountants investigate issues much earlier than traditional manual reviews.
5. Faster Financial Analysis
Artificial intelligence can summarize large volumes of financial information almost instantly.
Instead of manually compiling reports from multiple sources, AI accounting tools organize data, generate dashboards, and highlight significant changes automatically.
This allows accountants to spend less time preparing reports and more time discussing what the results actually mean.
The difference is important.
Preparing information is becoming increasingly automated.
Interpreting that information remains a uniquely human responsibility.
Where Artificial Intelligence Still Falls Short
Despite remarkable progress, AI accounting has clear limitations.
Technology processes information.
It does not truly understand businesses in the way experienced professionals do.
Accounting involves far more than mathematical accuracy.
Every financial decision exists within a broader commercial context.
That context often determines the correct answer.
Professional Judgment Cannot Be Automated
Accounting standards frequently require interpretation rather than simple calculations.
Two businesses may record similar transactions while requiring completely different accounting treatments because their underlying circumstances differ.
Determining the appropriate treatment requires:
Professional skepticism
Industry knowledge
Regulatory understanding
Ethical responsibility
Commercial judgment
Artificial intelligence can recommend possible approaches.
Qualified accountants remain responsible for deciding which treatment is appropriate.
That responsibility cannot simply be delegated to software.
Business Owners Need Advice—Not Just Reports
Financial statements are valuable.
But they are only the starting point.
Most business owners are not looking for another report.
They want answers.
Questions such as:
Should we hire more employees?
Can we afford another location?
Why has profitability declined?
Are we charging enough?
Is cash flow healthy?
What should management prioritize next quarter?
These conversations require more than financial data.
They require someone who understands strategy, operations, and business growth.
AI accounting provides faster information.
Great accountants provide meaningful direction.
Relationships Still Matter
Trust has always been one of the accounting profession’s greatest assets.
Business owners often discuss sensitive financial matters, long-term goals, succession planning, tax concerns, funding requirements, and investment decisions with their accountant.
These conversations depend on trust, communication, confidentiality, and professional relationships developed over many years.
Artificial intelligence cannot replace that human connection.
Technology supports relationships.
It does not build them.
For decades, the accounting profession has evolved alongside technology. From spreadsheets replacing handwritten ledgers to cloud accounting transforming collaboration, every major innovation has sparked the same question: Will technology replace accountants?
Today, that question has resurfaced with artificial intelligence.
The rapid growth of AI accounting has generated excitement, curiosity, and concern in equal measure. Businesses are using AI-powered software to automate bookkeeping, process invoices, reconcile bank transactions, detect anomalies, and generate financial reports within seconds. As these tools become more sophisticated, many professionals wonder whether the role of the accountant is slowly disappearing.
The reality is very different.
AI accounting is not replacing great accountants. It is replacing repetitive work that prevents accountants from delivering their highest value. Rather than making professionals obsolete, AI is reshaping the profession by allowing accountants to spend less time processing data and more time helping businesses make smarter financial decisions.
The firms and professionals who embrace AI accounting will become more productive, more strategic, and more valuable than ever before. Those who ignore technological change may struggle—not because artificial intelligence replaced them, but because competitors learned how to combine technology with professional expertise.
The future belongs to accountants who understand both numbers and business strategy.
In this article, we’ll explore why AI accounting is transforming the profession, what artificial intelligence can genuinely do, where its limitations remain, and why experienced accountants will continue to play a critical role in business success.
Why AI Accounting Is Creating So Much Discussion
Artificial intelligence has advanced at an extraordinary pace over the past few years.
Modern accounting platforms now incorporate machine learning, predictive analytics, and automation into everyday financial processes. What once required hours of manual effort can often be completed within minutes.
This rapid progress has naturally raised concerns within the profession.
Business owners see software performing bookkeeping tasks automatically.
Accounting firms see automation reducing administrative work.
Students entering the profession hear predictions that AI accounting will eventually eliminate accounting jobs altogether.
These headlines generate attention, but they rarely explain what is actually changing.
Technology has always automated routine work. Calculators replaced manual calculations. Spreadsheet software reduced paper-based bookkeeping. Cloud accounting simplified collaboration. Optical Character Recognition eliminated much of the manual data entry associated with invoices and receipts.
Each innovation changed the way accountants worked.
None of them eliminated the profession.
AI accounting represents another major step in that evolution.
Instead of replacing accountants, it changes where accountants create value.
The profession is moving away from transaction processing and toward business advisory, financial strategy, risk management, and decision support.
That shift should be viewed as an opportunity rather than a threat.
The Biggest Misconception About AI Accounting
One of the biggest misconceptions surrounding AI accounting is that accounting is simply about recording financial transactions.
In reality, bookkeeping is only one component of the profession.
Businesses don’t hire accountants merely to record expenses or prepare reports.
They rely on experienced professionals to answer questions such as:
Why is profit increasing while cash flow is declining?
Can the business afford to expand this year?
Which expenses should be reduced first?
How can tax liabilities be managed legally and efficiently?
What financial risks should management address immediately?
These questions require judgment, commercial awareness, and practical experience.
Artificial intelligence can provide information.
It cannot fully understand a company’s long-term objectives, risk appetite, industry challenges, or the personal priorities of business owners.
That difference is significant.
Technology produces information.
Great accountants transform that information into better business decisions.
Veritas Expert Insight
AI accounting should be viewed as a productivity tool rather than a replacement for professional expertise. Businesses still need accountants who can interpret financial information, provide strategic guidance, and help leaders make informed decisions.
What AI Accounting Already Does Better Than Humans
To understand where the profession is heading, accountants must first acknowledge where artificial intelligence already excels.
Ignoring these capabilities does not protect the profession.
Understanding them does.
1. Transaction Processing
One of the greatest strengths of AI accounting is processing large volumes of financial transactions quickly and consistently.
Instead of manually reviewing every expense, modern systems can categorize transactions based on historical patterns, vendor information, and predefined accounting rules.
This dramatically reduces repetitive bookkeeping work while improving efficiency.
2. Invoice and Receipt Processing
AI-powered document recognition has transformed one of the most time-consuming accounting tasks.
Invoices, bills, and receipts can now be scanned automatically.
Key information—including supplier names, invoice dates, tax amounts, and payment details—is extracted within seconds.
Rather than entering data manually, accountants simply review exceptions and verify unusual transactions.
3. Bank Reconciliations
Bank reconciliations have traditionally required careful matching of deposits, withdrawals, transfers, and outstanding transactions.
AI accounting platforms can automatically match thousands of transactions using predefined rules and historical behavior.
Instead of spending hours comparing bank statements line by line, accountants can focus on investigating genuine discrepancies.
4. Identifying Patterns
Artificial intelligence is exceptionally effective at recognizing patterns hidden within large datasets.
For example, AI accounting systems can quickly identify:
Duplicate payments
Unusual vendor activity
Missing invoices
Abnormal spending trends
Cash flow irregularities
Potential fraud indicators
These insights help accountants investigate issues much earlier than traditional manual reviews.
5. Faster Financial Analysis
Artificial intelligence can summarize large volumes of financial information almost instantly.
Instead of manually compiling reports from multiple sources, AI accounting tools organize data, generate dashboards, and highlight significant changes automatically.
This allows accountants to spend less time preparing reports and more time discussing what the results actually mean.
The difference is important.
Preparing information is becoming increasingly automated.
Interpreting that information remains a uniquely human responsibility.
Where Artificial Intelligence Still Falls Short
Despite remarkable progress, AI accounting has clear limitations.
Technology processes information.
It does not truly understand businesses in the way experienced professionals do.
Accounting involves far more than mathematical accuracy.
Every financial decision exists within a broader commercial context.
That context often determines the correct answer.
Professional Judgment Cannot Be Automated
Accounting standards frequently require interpretation rather than simple calculations.
Two businesses may record similar transactions while requiring completely different accounting treatments because their underlying circumstances differ.
Determining the appropriate treatment requires:
Professional skepticism
Industry knowledge
Regulatory understanding
Ethical responsibility
Commercial judgment
Artificial intelligence can recommend possible approaches.
Qualified accountants remain responsible for deciding which treatment is appropriate.
That responsibility cannot simply be delegated to software.
Business Owners Need Advice—Not Just Reports
Financial statements are valuable.
But they are only the starting point.
Most business owners are not looking for another report.
They want answers.
Questions such as:
Should we hire more employees?
Can we afford another location?
Why has profitability declined?
Are we charging enough?
Is cash flow healthy?
What should management prioritize next quarter?
These conversations require more than financial data.
They require someone who understands strategy, operations, and business growth.
AI accounting provides faster information.
Great accountants provide meaningful direction.
Relationships Still Matter
Trust has always been one of the accounting profession’s greatest assets.
Business owners often discuss sensitive financial matters, long-term goals, succession planning, tax concerns, funding requirements, and investment decisions with their accountant.
These conversations depend on trust, communication, confidentiality, and professional relationships developed over many years.
Artificial intelligence cannot replace that human connection.
For many business owners, revenue is the first number they look at when evaluating business performance.
Sales reports show increasing revenue. Monthly dashboards highlight record-breaking sales. Teams celebrate crossing new revenue milestones.
While these achievements are exciting, they don’t necessarily mean the business is becoming stronger.
Many businesses generate millions of dollars in revenue yet struggle to pay suppliers, delay payroll, or rely on short-term borrowing to fund daily operations. At the same time, some businesses with lower revenue consistently generate healthy profits, maintain strong cash reserves, and continue growing year after year.
The difference lies in what they measure.
Successful businesses understand that revenue is only one financial metric. To understand the true health of a business, owners must also monitor profitability, liquidity, operational efficiency, and cash flow management.
Without effective cash flow management, even a business experiencing rapid sales growth can face financial difficulties.
This is why experienced entrepreneurs, investors, and Virtual CFOs rarely judge a business solely by its revenue. They look deeper into the numbers that reveal whether the business is financially stable and capable of sustainable growth.
In this article, you’ll discover why revenue doesn’t tell the whole story and learn which financial metrics deserve your attention if you want to build a stronger, more profitable business.
Why Revenue Doesn’t Tell the Whole Story
Revenue represents the total income generated from selling products or services before deducting expenses.
Although it’s an important indicator of market demand and business activity, revenue alone cannot answer several critical questions.
For example:
Is the business generating consistent profits?
Can it comfortably pay employees and suppliers?
Is there enough cash available to cover daily operations?
Are customers paying invoices on time?
Is the business prepared for unexpected expenses?
The answers to these questions come from analyzing financial performance beyond revenue.
This is where cash flow management becomes essential.
A business can report exceptional sales while simultaneously experiencing cash shortages because revenue and cash are not the same thing.
Imagine two companies, each generating $2 million in annual revenue.
Company A
Revenue: $2 million
Positive operating cash flow
Healthy profit margins
Strong working capital
No overdue supplier payments
Consistent cash reserves
Company B
Revenue: $2 million
Negative operating cash flow
Declining profit margins
Frequent cash shortages
Overdue vendor balances
Dependence on short-term financing
On paper, both businesses appear equally successful because they generate identical revenue.
In reality, Company A has the financial strength to grow confidently, while Company B spends most of its time managing financial pressure.
The difference isn’t sales—it’s effective cash flow management and sound financial decision-making.
Looking beyond revenue enables business owners to identify potential risks before they become serious problems.
Veritas Expert Insight
Revenue tells you how much business you’re generating. Cash flow management tells you whether your business can survive, grow, and invest confidently in the future.
Cash Flow Is the Foundation of a Healthy Business
Every business depends on cash.
Employees expect salaries on time. Suppliers need to be paid. Taxes must be settled. Rent, utilities, insurance, inventory, and operating expenses continue regardless of how much revenue appears on the income statement.
That’s why cash flow management is often described as the lifeblood of a business.
Simply put, cash flow management involves monitoring, planning, and controlling how money moves into and out of your business.
When managed effectively, it helps ensure there is always enough cash available to meet financial obligations while supporting future growth.
Consider a consulting firm that completes a large project worth $300,000.
The invoice is issued immediately, and the revenue is recorded in the financial statements.
However, the client has 90-day payment terms.
For the next three months, the consulting firm must continue paying employee salaries, office rent, software subscriptions, insurance, and other operating expenses—even though the cash hasn’t yet arrived.
Without strong cash flow management, profitable businesses can still experience financial stress simply because cash is delayed.
This situation is more common than many business owners realize.
Businesses that prioritize cash flow management are better positioned to:
Pay suppliers without delays.
Meet payroll confidently.
Build emergency cash reserves.
Reduce reliance on loans and overdrafts.
Invest in expansion opportunities.
Navigate seasonal fluctuations.
Rather than reacting to financial challenges, these businesses anticipate them and plan accordingly.
Early Warning Signs of Poor Cash Flow
Cash flow problems rarely appear overnight.
Most businesses receive warning signs long before a financial crisis develops.
Some common indicators include:
Consistently delaying supplier payments.
Frequently using credit cards to cover expenses.
Relying on overdraft facilities every month.
Struggling to pay taxes on time.
Increasing customer outstanding balances.
Limited cash despite growing sales.
Difficulty funding day-to-day operations.
Recognizing these warning signs early allows businesses to improve cash flow management before small issues become expensive problems.
Regular cash flow forecasting and monthly financial reviews help identify these risks well in advance.
Revenue Growth Doesn’t Always Mean Financial Growth
One of the biggest misconceptions in business is believing that increasing revenue automatically leads to greater financial success.
Unfortunately, this isn’t always true.
As revenue grows, expenses often grow as well.
Businesses may hire additional employees, lease larger office space, purchase more inventory, increase marketing budgets, or invest in new technology.
If these additional costs increase faster than profits, revenue growth may actually reduce financial stability.
Similarly, businesses that offer extended credit terms may record higher sales while waiting months to receive customer payments.
Without proper cash flow management, rapid business growth can create cash shortages instead of financial strength.
This is why many successful companies focus on sustainable growth rather than simply chasing higher revenue.
Healthy growth balances increasing sales with profitability, liquidity, and effective cash flow management.
Gross profit margin tells you how efficiently your business earns those sales.
Gross profit is the amount remaining after deducting direct costs such as inventory, raw materials, manufacturing costs, or direct labor.
A strong gross profit margin indicates that pricing strategies, supplier negotiations, and operational efficiency are working together effectively.
For example, two companies may each generate $1 million in annual revenue.
However:
Business A: Gross Profit Margin – 58%
Business B: Gross Profit Margin – 31%
Although their revenue is identical, Business A retains significantly more money to cover operating expenses, strengthen cash flow management, invest in growth, and improve profitability.
Monitoring gross profit margin regularly helps business owners identify:
Rising supplier costs.
Pricing issues.
Production inefficiencies.
Inventory challenges.
Declining profitability.
When analyzed alongside cash flow management, gross profit margin provides a much clearer picture of financial performance than revenue alone.
Net Profit Margin Shows What You Actually Keep
Revenue measures the money coming into your business.
Net profit measures the money that actually stays in your business after paying operating expenses, salaries, rent, marketing costs, taxes, interest, and other business expenses.
This is one of the most important indicators of long-term financial success.
Many businesses proudly report increasing revenue while overlooking shrinking profit margins.
Common reasons include:
Rising operating expenses.
Poor pricing decisions.
Excessive overhead costs.
Inefficient business processes.
Uncontrolled discretionary spending.
A business generating $3 million in annual revenue with a 3% net profit margin earns less than another business generating $1.5 million in revenue with a 12% net profit margin.
This demonstrates why profitability should always be reviewed together with cash flow management.
Strong profits improve financial stability, while effective cash flow management ensures those profits are available to support future growth, business investments, and unexpected challenges.
Working Capital Is Your Financial Safety Net
Revenue may show how much your business sells, but working capital determines whether your business can continue operating without interruption.
Working capital is the difference between current assets and current liabilities. It measures your ability to meet short-term financial obligations using the resources you already have.
Think of working capital as the financial cushion that keeps your business running smoothly.
Businesses with healthy working capital can:
Pay suppliers on time.
Meet payroll without stress.
Purchase inventory when demand increases.
Take advantage of new business opportunities.
Handle unexpected expenses with confidence.
On the other hand, businesses with weak working capital often delay vendor payments, rely on overdrafts, or postpone important investments—even when revenue continues to grow.
This is why working capital and cash flow management should always be reviewed together. Strong sales may attract attention, but strong liquidity keeps the business operating.
Business owners should review their working capital every month to ensure they have enough financial flexibility to support both daily operations and future growth.
Accounts Receivable Can Strengthen or Weaken Your Cash Flow
Making a sale is only the first step.
Receiving payment is what keeps your business financially healthy.
Many businesses proudly report increasing revenue while waiting 60, 90, or even 120 days for customers to pay their invoices. During that waiting period, operating expenses continue to accumulate.
Imagine your business generates $250,000 in monthly revenue.
If customers consistently pay after 90 days, you still need enough cash to cover:
Employee salaries
Rent and utilities
Inventory purchases
Software subscriptions
Marketing expenses
Taxes
Supplier payments
Without proper cash flow management, delayed collections can create unnecessary financial pressure—even when revenue continues to increase.
To improve collections, businesses should:
Send invoices immediately.
Clearly communicate payment terms.
Review Accounts Receivable aging reports every month.
Follow up on overdue invoices consistently.
Offer convenient payment options.
Improving collection times by even two weeks can significantly strengthen cash flow management without generating a single additional sale.
Veritas Expert Insight
The easiest way to improve cash flow isn’t always increasing revenue. Often, it’s collecting existing invoices faster and improving your overall cash flow management process.
Not Every Customer Is Profitable
Many business owners focus on acquiring more customers.
Successful businesses focus on acquiring better customers.
Two customers may generate the same revenue, yet deliver completely different financial results.
For example:
Customer A
Pays invoices within 15 days.
Places repeat orders.
Requires minimal support.
Accepts standard pricing.
Customer B
Frequently requests discounts.
Pays invoices late.
Requires significant administrative support.
Generates numerous service requests.
Although both customers contribute to revenue, Customer A contributes much more to profitability and cash flow management.
Growing revenue is important, but growing profitable revenue creates a healthier and more sustainable business.
Financial KPIs Every Business Owner Should Monitor
Revenue is only one financial metric.
To understand the complete financial picture, business owners should monitor several key performance indicators every month.
Financial KPI
Why It Matters
Cash Flow
Ensures enough cash is available to operate and grow the business.
Gross Profit Margin
Measures pricing effectiveness and direct cost control.
Net Profit Margin
Shows how much profit the business actually keeps.
Working Capital
Indicates short-term financial stability.
Accounts Receivable Days
Measures how quickly customers pay invoices.
Operating Expenses
Helps identify unnecessary spending.
Customer Profitability
Identifies the customers that generate the greatest long-term value.
Reviewing these KPIs together provides a complete picture of business performance.
Rather than reacting to financial problems after they occur, business owners can identify trends early and make informed decisions that strengthen profitability and cash flow management.
Why Every Growing Business Needs a Virtual CFO
As businesses grow, financial decisions become more complex.
Questions such as:
Can we afford to hire more employees?
Should we expand into a new market?
Is our pricing strategy profitable?
Do we have enough cash for future investments?
cannot be answered by looking at revenue alone.
This is where a Virtual CFO provides significant value.
A Virtual CFO transforms financial reports into strategic business insights by helping owners:
Improve cash flow management.
Develop realistic budgets.
Forecast future cash requirements.
Monitor financial KPIs.
Improve profitability.
Optimize working capital.
Identify financial risks before they become major problems.
Instead of making decisions based on assumptions, business owners gain confidence by using reliable financial data.
A Virtual CFO doesn’t simply explain what happened last month—they help you prepare for what comes next.
Final Thoughts
Revenue is an important indicator of business growth, but it should never be the only measure of success.
The businesses that thrive over the long term focus on much more than sales. They monitor profitability, working capital, customer collections, operating efficiency, and cash flow management to understand the true financial health of their organization.
When business owners shift their attention from revenue alone to the financial metrics that drive long-term stability, they make better decisions, reduce financial risk, and create stronger foundations for sustainable growth.
At Veritas Accounting Services, we help businesses gain that financial clarity through accurate bookkeeping, cash flow management, management reporting, and Virtual CFO services. Our goal is to help business owners understand their numbers, improve profitability, and make confident financial decisions.
Frequently Asked Questions
Why isn’t revenue enough to measure business success?
Revenue measures sales, but it doesn’t show whether the business is profitable, financially stable, or generating enough cash to meet its obligations. Reviewing profitability, working capital, and cash flow management provides a much clearer picture.
Why is cash flow management important?
Cash flow management helps ensure your business always has enough cash to pay employees, suppliers, taxes, and operating expenses while supporting future growth.
What financial KPI should business owners monitor every month?
Every business should regularly review revenue, cash flow, gross profit margin, net profit margin, working capital, accounts receivable, and operating expenses.
Can a profitable business still run out of cash?
Yes. A business can report strong profits while experiencing cash shortages if customers delay payments or operating expenses exceed available cash. Effective cash flow management helps prevent these situations.
What does a Virtual CFO do?
A Virtual CFO helps businesses improve financial performance by providing budgeting, forecasting, KPI analysis, strategic planning, and cash flow management support.
Ready to Look Beyond Revenue?
Revenue may tell you how fast your business is growing, but the right financial metrics tell you how strong your business really is.
At Veritas Accounting Services, we help businesses strengthen cash flow management, improve financial reporting, monitor key performance indicators, and make informed decisions through our bookkeeping and Virtual CFO services.
If you’re ready to build a financially stronger business, contact Veritas Accounting Services today and discover how better financial insights can drive long-term success.
Expanding into international markets opens the door to exciting growth opportunities. Businesses can reach new customers, work with overseas suppliers, and build a global presence without establishing offices in every country. However, as international operations grow, so does financial complexity.
Receiving payments in Euros, paying suppliers in British Pounds, maintaining a bank account in U.S. Dollars, and reporting financial statements in another currency can quickly become overwhelming if the right systems are not in place.
Many businesses assume that converting one currency into another is all that is required. In reality, managing multiple currencies involves much more than simple exchange rate calculations. Every foreign currency transaction affects revenue recognition, expenses, cash flow, financial reporting, and profitability.
Without proper multi-currency accounting, businesses may experience inaccurate financial reports, unexpected exchange gains or losses, reconciliation issues, and poor financial decision-making.
Fortunately, these challenges can be managed with the right accounting processes, technology, and financial expertise.
In this guide, we’ll explore how international businesses can effectively manage multiple currencies while maintaining accurate financial records and making better business decisions.
Why Multi-Currency Management Matters More Than Ever
International business is no longer limited to large multinational corporations.
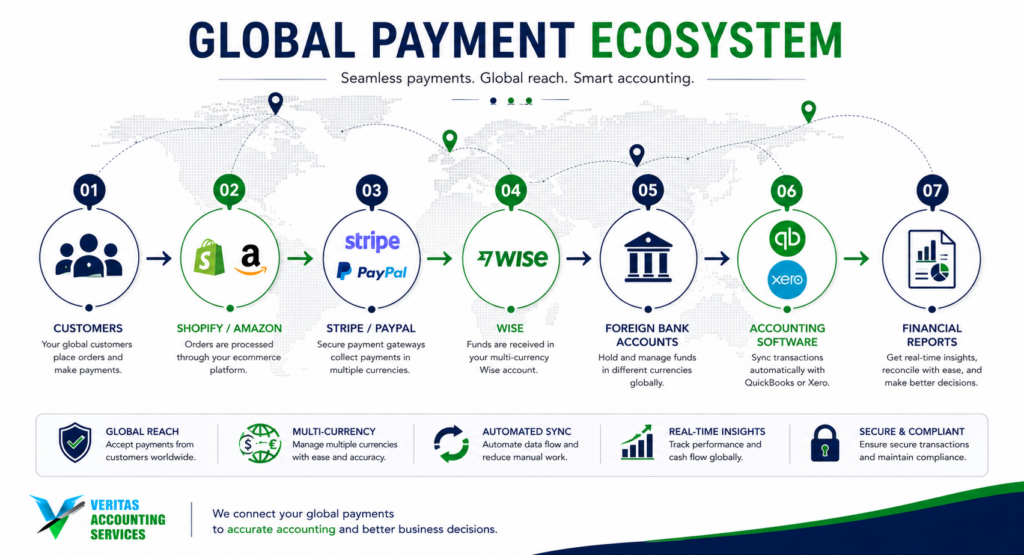
Today, even small businesses regularly sell products through Shopify, Amazon, Etsy, and WooCommerce to customers around the world. Service-based companies invoice overseas clients, while importers purchase inventory from international suppliers using different currencies.
As a result, businesses often deal with:
Customers paying in multiple currencies.
International suppliers issuing invoices in foreign currencies.
Overseas bank accounts.
Payment gateways such as Stripe and PayPal.
Global money transfer platforms like Wise.
Currency fluctuations affecting profitability.
Managing all these transactions manually increases the likelihood of errors and consumes valuable time.
This is why multi-currency accounting has become an essential part of modern financial management rather than an optional feature.
When businesses maintain accurate multi-currency accounting, they gain a clearer understanding of profitability, improve cash flow management, and make better financial decisions based on reliable information.
Veritas Expert Insight
Many businesses focus only on exchange rates when dealing with international transactions. In reality, accurate multi-currency accounting also depends on proper bookkeeping, timely reconciliations, consistent reporting, and understanding how foreign currency movements affect overall profitability.
Understanding the Challenges of Multi-Currency Accounting
Managing multiple currencies introduces several accounting challenges that domestic businesses rarely encounter.
Recognizing these challenges is the first step toward building an efficient financial system.
Exchange Rate Fluctuations
Currency values change continuously.
A payment received today may have a different value tomorrow simply because exchange rates have moved.
For example, an invoice issued in Euros may convert into more or fewer U.S. Dollars by the time the customer pays.
Without proper multi-currency accounting, these differences may be overlooked, leading to inaccurate financial statements and incorrect profit calculations.
Multiple Bank Accounts
Many international businesses maintain bank accounts in different currencies.
For example:
U.S. Dollar account
Euro account
British Pound account
Australian Dollar account
Each account requires separate reconciliation, accurate currency conversion, and proper financial reporting.
Trying to manage these accounts manually often results in reconciliation differences and reporting inconsistencies.
Payment Gateways Create Additional Complexity
Modern businesses rarely receive payments directly into their primary bank account.
Instead, payments may flow through:
Stripe
PayPal
Wise
Amazon
Shopify Payments
Each platform applies its own settlement schedules, processing fees, currency conversions, and exchange rates.
For example, a customer may pay €1,000 through Stripe, but after processing fees and currency conversion, the amount deposited into your U.S. Dollar bank account may be significantly different.
Without proper multi-currency accounting, reconciling these transactions becomes increasingly difficult.
Currency Gains and Losses
One of the most misunderstood aspects of international accounting is exchange gains and losses.
Suppose your business invoices a customer for £10,000.
When the invoice is issued, it converts to $13,000.
Thirty days later, the customer pays when the exchange rate has changed, and the payment now converts to $13,350.
Your business hasn’t earned additional revenue.
Instead, it has experienced a foreign exchange gain created solely by changes in currency values.
Similarly, if exchange rates move in the opposite direction, the business records an exchange loss.
Understanding these adjustments is an important part of accurate multi-currency accounting and helps businesses present reliable financial statements.
Best Practices for Managing Multiple Currencies
Managing international finances becomes much easier when businesses establish clear accounting procedures from the beginning.
Here are some of the most effective practices.
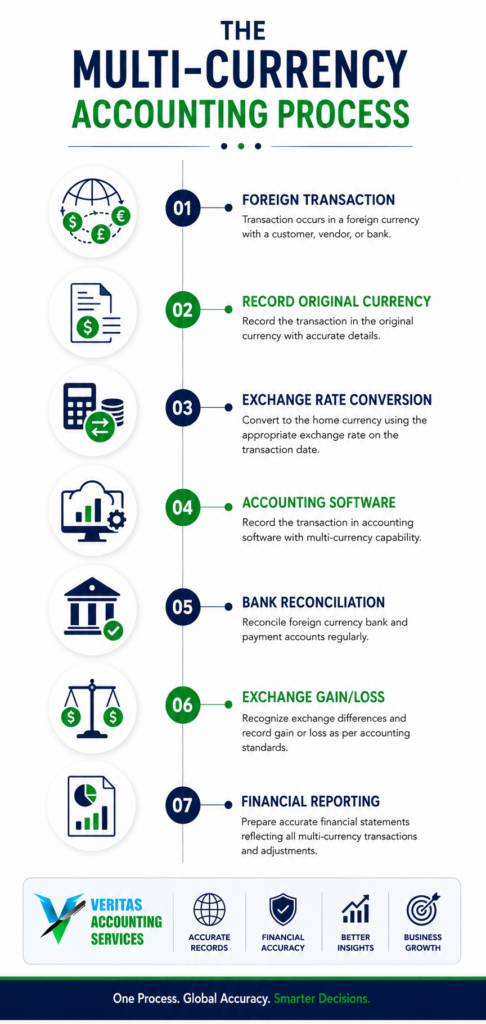
Record Every Transaction in Its Original Currency
One of the biggest mistakes businesses make is converting transactions before recording them.
Instead, every invoice, bill, expense, and receipt should first be recorded in the original transaction currency.
Modern accounting software automatically converts amounts into the business’s reporting currency while preserving the original transaction details.
This approach improves accuracy, simplifies audits, and makes reconciliation significantly easier.
Use Accounting Software That Supports Multi-Currency Accounting
Managing multiple currencies using spreadsheets may work temporarily, but it becomes increasingly risky as transaction volumes grow.
Modern accounting platforms such as QuickBooks Online and Xero include built-in multi-currency accounting features that automatically:
Track exchange rates.
Convert foreign transactions.
Calculate exchange gains and losses.
Generate consolidated financial reports.
Support multiple foreign currency bank accounts.
These capabilities reduce manual work and improve the accuracy of financial reporting.
Each foreign currency bank account, payment gateway, and digital wallet should be reconciled against accounting records to identify:
Missing transactions.
Duplicate entries.
Incorrect exchange rates.
Unrecorded bank charges.
Currency conversion differences.
Regular reconciliation ensures that financial statements remain accurate and that issues are identified before they become significant problems.
Monitor Exchange Rates Regularly
Exchange rates can change several times throughout the day, and even small fluctuations can significantly affect businesses with high transaction volumes.
For example, an exporter receiving payments in Euros may see a noticeable difference in the amount converted into U.S. Dollars simply because the exchange rate changed between the invoice date and the payment date.
Rather than relying on outdated or manually entered rates, businesses should use accounting software that updates exchange rates automatically or establish a consistent process for reviewing them regularly.
Accurate exchange rates improve financial reporting, reduce reconciliation differences, and provide a more realistic picture of business performance.
Separate Exchange Gains and Losses from Operating Income
Currency fluctuations should never distort the true performance of your business.
A profitable month shouldn’t appear even more profitable simply because exchange rates moved in your favour. Likewise, a temporary currency loss shouldn’t hide the fact that your operations performed well.
Good multi-currency accounting separates foreign exchange gains and losses from normal operating income.
Doing so allows management to understand whether profitability improved because the business performed better or simply because currencies moved in a favourable direction.
This distinction is particularly important when reviewing financial performance, preparing budgets, or making strategic decisions.
Review Cash Flow by Currency
Many international businesses focus only on total cash balances.
However, knowing you have $200,000 in total cash doesn’t tell the whole story if those funds are spread across several currencies.
For example:
USD Account – $90,000
EUR Account – €45,000
GBP Account – £20,000
AUD Account – AU$30,000
Each currency may be required for different suppliers, payroll obligations, taxes, or operating expenses.
Monitoring cash flow by currency helps businesses avoid unnecessary conversion costs and maintain sufficient balances where they are needed most.
This is one of the most practical benefits of effective multi-currency accounting.
Veritas Expert Insight
Businesses often lose money through unnecessary currency conversions rather than exchange rate movements. Holding the right currency for future payments can reduce banking fees, minimise conversion costs, and improve cash flow efficiency.
How Technology Simplifies Global Finance
Managing international finances manually is no longer practical for growing businesses.
Today’s accounting platforms integrate with banks, payment gateways, and business applications to automate much of the work involved in multi-currency accounting.
Cloud accounting software such as QuickBooks Online and Xero automatically records foreign currency transactions, calculates exchange gains and losses, updates exchange rates, and produces consolidated financial reports.
Businesses using platforms like Shopify and Amazon can integrate sales data directly into their accounting systems, while payment processors such as Stripe, PayPal, and Wise simplify international collections and settlements.
Automation offers several advantages:
Faster bookkeeping.
Reduced manual errors.
Automatic exchange rate calculations.
Easier bank reconciliations.
Improved financial reporting.
Better visibility across multiple currencies.
Technology doesn’t eliminate the need for professional accounting advice, but it significantly improves efficiency and accuracy.
Common Multi-Currency Accounting Mistakes
Even experienced businesses can make mistakes when managing international finances.
Avoiding these common errors can save considerable time and money.
Recording Transactions in the Wrong Currency
Every transaction should be recorded in the currency in which it originally occurred.
Converting amounts before recording them often creates reconciliation issues later.
Mixing Different Currencies in One Bank Account
Each foreign currency account should be maintained separately within the accounting system.
Combining different currencies into a single account makes reconciliation difficult and reduces reporting accuracy.
Ignoring Exchange Gains and Losses
Some businesses record only the amount deposited into their bank account.
This approach overlooks exchange gains or losses and results in inaccurate financial statements.
Proper multi-currency accounting recognises these adjustments automatically.
Delaying Bank Reconciliations
Waiting several months before reconciling foreign currency accounts often creates larger problems.
Monthly reconciliations help identify missing transactions, duplicate entries, bank fees, and exchange differences before they become difficult to resolve.
Depending on Manual Spreadsheets
While spreadsheets remain useful for analysis, they should not be the primary system for managing international accounting.
As transaction volumes increase, manual calculations become time-consuming and more susceptible to errors.
Managing multiple currencies successfully requires more than good software.
It requires consistent accounting processes, regular reconciliations, and an understanding of international financial reporting.
An experienced accounting professional can help businesses:
Maintain accurate multi-currency accounting records.
Reconcile foreign bank accounts and payment gateways.
Record exchange gains and losses correctly.
Prepare reliable financial statements.
Monitor international cash flow.
Improve profitability through better financial reporting.
Support tax compliance across multiple jurisdictions.
As international operations grow, having professional financial guidance becomes increasingly valuable.
Instead of spending hours resolving reconciliation issues or investigating currency differences, business owners can focus on expanding their business with confidence.
Final Thoughts
Expanding internationally creates exciting opportunities, but it also introduces financial complexity that cannot be managed with basic bookkeeping alone.
Successful global businesses understand that multi-currency accounting is more than converting one currency into another. It involves managing exchange rate fluctuations, reconciling foreign currency accounts, monitoring international cash flow, recording exchange gains and losses accurately, and producing reliable financial reports that support informed decision-making.
By combining strong accounting processes with modern cloud accounting software and experienced financial guidance, businesses can reduce risk, improve reporting accuracy, and operate confidently across international markets.
At Veritas Accounting Services, we help international businesses simplify complex financial processes through accurate bookkeeping, multi-currency accounting, financial reporting, and Virtual CFO services—allowing business owners to focus on growth while we manage the numbers.
Frequently Asked Questions
What is multi-currency accounting?
Multi-currency accounting is the process of recording, managing, and reporting financial transactions conducted in different currencies while maintaining accurate financial statements in the company’s reporting currency.
Which accounting software supports multi-currency accounting?
Popular platforms such as QuickBooks Online and Xero include built-in multi-currency accounting features that automatically handle exchange rates, foreign currency transactions, and exchange gains or losses.
What is the difference between realized and unrealized exchange gains?
A realized exchange gain or loss occurs when a foreign currency transaction is settled. An unrealized exchange gain or loss represents the change in value of an outstanding foreign currency balance before it is paid or received.
How often should foreign currency accounts be reconciled?
Foreign currency bank accounts, payment gateways, and digital wallets should ideally be reconciled every month to ensure accurate financial reporting and identify discrepancies promptly.
Why is multi-currency accounting important for international businesses?
Multi-currency accounting helps businesses maintain accurate financial records, manage exchange rate fluctuations, improve cash flow visibility, comply with accounting standards, and make better business decisions.
Ready to Simplify Your International Accounting?
Managing multiple currencies doesn’t have to be complicated. At Veritas Accounting Services, we help international businesses maintain accurate multi-currency accounting, reconcile global payment platforms, manage foreign currency bank accounts, and produce reliable financial reports that support smarter decisions.
Whether you sell globally, work with overseas suppliers, or operate across multiple countries, our team can help streamline your international accounting processes.
Many entrepreneurs assume that hiring a Chief Financial Officer (CFO) is something only multinational corporations or large enterprises need. After all, if the bookkeeping is accurate, the taxes are filed on time, and the financial statements are prepared every month, why would a small business need another financial expert?
It’s a reasonable question—but it’s also one that many growing businesses ask a little too late.
As your business expands, financial decisions become more complex. Revenue increases, operating expenses rise, cash flow becomes harder to predict, and opportunities for growth require larger investments. At this stage, simply knowing your bank balance or monthly profit is no longer enough.
Business owners need someone who can interpret financial data, identify potential risks, forecast future performance, and provide strategic advice before important decisions are made.
That is where a small business CFO becomes invaluable.
A CFO isn’t responsible for recording transactions or preparing tax returns. Their role is to transform financial information into business intelligence that helps owners make confident decisions.
Whether you’re planning to hire more employees, expand into new markets, purchase equipment, or improve profitability, having strategic financial leadership can significantly reduce risk and increase the likelihood of long-term success.
The good news is that today’s small businesses don’t necessarily need to hire a full-time executive. Virtual CFO services have made high-level financial expertise accessible and affordable, allowing businesses to benefit from experienced financial leadership without the cost of a permanent executive.
So, how do you know when it’s time to bring a CFO into your business?
Let’s explore the signs.
Why Many Business Owners Delay Hiring a CFO
Most business owners begin with a straightforward financial structure.
A bookkeeper records transactions.
An accountant prepares financial statements and tax returns.
Everything appears to be under control.
As long as sales continue to grow and bills are paid on time, it feels unnecessary to invest in additional financial support.
The challenge is that growth often creates financial complexity much faster than business owners expect.
Multiple products, services, or business locations introduce additional reporting requirements.
Loans, equipment financing, and expansion plans add new financial responsibilities.
Without strategic financial oversight, owners often find themselves making important business decisions based on instinct rather than reliable financial analysis.
By the time cash flow becomes tight or profits begin to decline, correcting the problem is usually more expensive than preventing it.
A small business CFO helps businesses stay ahead of these challenges by providing forward-looking financial guidance instead of simply reviewing historical results.
Veritas Expert Insight
One of the most common mistakes we see is business owners seeking strategic financial advice only after experiencing cash flow issues or declining profits. The most successful businesses use financial planning to prevent problems—not just solve them.
Bookkeeping Keeps You Compliant, a CFO Helps You Grow
Bookkeeping and accounting are the foundation of every successful business.
Without accurate records, financial decisions become unreliable.
However, accurate records alone don’t create growth.
Think of bookkeeping as a rear-view mirror.
It tells you where your business has been.
A CFO acts more like a GPS.
They help you determine where you’re going and identify the best route to get there.
For example, your monthly Profit and Loss Statement might show a healthy increase in revenue.
At first glance, that seems like excellent news.
But a closer review could reveal that marketing costs have increased at a faster rate than sales, gross margins have declined because of rising supplier prices, or customer payment delays are creating cash flow pressure.
The financial statements provide information.
A CFO provides interpretation.
Instead of asking, “How much profit did we make last month?” they ask:
Why did profitability change?
Which products generate the strongest margins?
Where are unnecessary expenses increasing?
Can the business afford expansion?
What will cash flow look like over the next six months?
These are the questions that influence the future of a business.
Strategic financial leadership helps business owners make informed decisions based on data rather than assumptions.
Signs Your Business Needs a Small Business CFO
Every business reaches a stage where basic accounting support is no longer enough.
If any of the following situations sound familiar, it may be time to consider bringing in a small business CFO.
Your Business Is Growing Faster Than Expected
Growth is exciting, but it also increases financial complexity.
More revenue usually means more inventory, additional employees, higher operating expenses, larger supplier commitments, and increased working capital requirements.
Without careful planning, rapid growth can actually create financial pressure instead of improving profitability.
A small business CFO develops financial forecasts that help ensure growth remains sustainable.
Rather than reacting to challenges as they arise, business owners gain the confidence to plan ahead.
Cash Flow Is Becoming More Difficult to Manage
Many businesses are profitable on paper but still struggle to pay suppliers, employees, or loan instalments on time.
Why?
Because profit and cash flow are not the same.
Customer payment delays, inventory purchases, tax liabilities, loan repayments, and seasonal fluctuations all affect available cash.
A small business CFO prepares detailed cash flow forecasts, helping businesses identify potential shortages before they occur.
This allows owners to make informed decisions about financing, spending, and investment instead of responding to unexpected cash flow problems.
You’re Making Major Business Decisions Without Financial Analysis
Every growing business eventually faces important decisions.
Should you hire another salesperson?
Can you afford a second office?
Is it the right time to invest in new equipment?
Should prices be increased?
Would taking a business loan improve growth or create unnecessary risk?
These decisions should never rely solely on intuition.
A small business CFO evaluates multiple financial scenarios, measures potential risks, and provides objective recommendations that support long-term business success.
Instead of relying on guesswork, every significant decision is supported by reliable financial analysis. Your Financial Reports Raise More Questions Than They Answer
Receiving monthly financial statements is important.
Understanding what those numbers actually mean is even more valuable.
Many business owners review their Profit and Loss Statement and Balance Sheet every month but still struggle to answer questions like:
Why is profit decreasing even though sales are increasing?
Which products or services generate the highest margins?
Are overhead costs growing too quickly?
How much cash will the business have three months from now?
Which customers are the most profitable?
Financial reports should provide clarity, not confusion.
A small business CFO doesn’t just prepare reports—they explain what the numbers mean, identify trends, and recommend actions that improve business performance.
Instead of looking backward, your business starts making decisions based on where it’s heading.
Banks, Investors, or Lenders Need Better Financial Information
As your business grows, there may come a time when you need external funding.
Whether you’re applying for a bank loan, attracting investors, or negotiating with lenders, historical financial statements alone are rarely enough.
Financial institutions often expect:
Cash flow forecasts
Financial projections
Budgets
Key Performance Indicators (KPIs)
Business growth plans
Profitability analysis
Preparing these documents requires strategic financial expertise.
A small business CFO helps present your financial position professionally, improves credibility with lenders, and ensures your business is financially prepared before seeking funding.
Being proactive can significantly increase your chances of securing financing on favourable terms.
You’re Spending More Time Managing Finances Than Running Your Business
Every entrepreneur starts by wearing multiple hats.
You’re the salesperson, operations manager, customer service representative, and finance manager—all at the same time.
While this works in the early stages, it eventually becomes unsustainable.
If you find yourself spending evenings reviewing reports, worrying about cash flow, or trying to understand financial data instead of focusing on customers and growth, it’s a clear sign your business needs stronger financial leadership.
A small business CFO takes ownership of financial strategy, allowing you to concentrate on growing the business rather than constantly managing the numbers.
After all, your time is one of your company’s most valuable assets.
Veritas Expert Insight
The most successful business owners don’t try to become financial experts themselves. They surround themselves with specialists who provide the insights needed to make confident business decisions.
How a Small Business CFO Creates Long-Term Value
Hiring a CFO isn’t simply about solving today’s financial challenges.
It’s about preparing your business for tomorrow’s opportunities.
A small business CFO helps build a stronger financial foundation by introducing processes and strategies that support sustainable growth.
Some of the key areas where a CFO adds value include:
Preparing realistic budgets that align with business goals.
Forecasting cash flow to avoid unexpected shortages.
Improving profitability through cost and margin analysis.
Building KPI dashboards that monitor business performance.
Supporting pricing and investment decisions with financial data.
Identifying financial risks before they become costly problems.
Developing long-term financial strategies for expansion.
Rather than reacting to financial issues, businesses become proactive and make decisions with greater confidence.
This shift often results in better profitability, healthier cash flow, and stronger financial stability.
Why a Virtual CFO Is the Smart Choice for Small Businesses
Many business owners assume hiring a CFO requires a significant investment.
Fortunately, that is no longer the case.
A Virtual CFO provides the same strategic expertise as a traditional CFO but on a flexible, cost-effective basis.
Instead of paying a full-time executive salary, businesses receive experienced financial leadership tailored to their specific needs.
A Virtual CFO can assist with:
Financial planning and budgeting
Cash flow forecasting
Management reporting
KPI development
Business performance reviews
Strategic planning
Funding support
Growth planning
This approach allows small businesses to access executive-level financial expertise without increasing fixed overhead costs.
As a result, a small business CFO becomes an affordable investment rather than an expensive luxury.
Final Thoughts
Many businesses believe they need a CFO only after reaching a certain revenue target.
In reality, the right time to bring in strategic financial leadership is when financial decisions become more complex than routine bookkeeping can support.
If your business is experiencing rapid growth, managing tighter cash flow, planning expansion, seeking financing, or simply struggling to understand what your financial reports are telling you, it may be time to consider working with a small business CFO.
Strategic financial guidance helps businesses move beyond compliance and focus on long-term success.
At Veritas Accounting Services, we believe finance should do more than record the past—it should help shape the future.
Whether you need budgeting, forecasting, cash flow management, management reporting, or Virtual CFO services, our goal is to provide the financial insights that help your business grow with confidence.
Frequently Asked Questions
What does a small business CFO do?
A small business CFO provides strategic financial leadership by helping business owners with budgeting, cash flow forecasting, financial analysis, KPI reporting, profitability improvement, and long-term business planning. small business CFO
When should a small business hire a CFO?
A business should consider hiring a CFO when financial decisions become more complex, cash flow is difficult to manage, rapid growth creates new challenges, or external funding requires detailed financial planning and small business CFO planning.
What is the difference between a bookkeeper and a CFO?
A bookkeeper records financial transactions and maintains accurate records. A CFO analyses financial information, develops strategies, forecasts future performance, and supports important business decisions.
Is a Virtual CFO better than a full-time CFO?
For many SMEs, a Virtual CFO offers the same strategic expertise as a full-time small business CFO at a significantly lower cost, making it a practical and cost-effective solution. small business CFO
Can startups benefit from a small business CFO?
Yes. Startups can benefit from financial forecasting, budgeting, investor reporting, and strategic planning long before they are ready to hire a full-time finance executive.
Call to Action
Ready to Take Your Business Beyond Bookkeeping?
As your business grows, so do your financial challenges. At Veritas Accounting Services, our Virtual CFO services help business owners make smarter decisions through strategic financial planning, cash flow forecasting, budgeting, KPI reporting, and management insights.
Whether you’re preparing for expansion, improving profitability, or seeking better financial visibility, we’re here to help.
Contact Veritas Accounting Services today and discover how expert financial leadership can support your next stage of growth.
For many years, finance was viewed as a support function. Business owners expected their accountant to record transactions, prepare financial statements, reconcile bank accounts, and ensure taxes were filed correctly. While those responsibilities remain important, they no longer represent the full value that finance can bring to a growing business.
Today’s business environment is very different. Markets change quickly, customer expectations evolve, technology advances rapidly, and competition is stronger than ever. In this environment, making decisions based on outdated financial reports can mean missed opportunities, shrinking profit margins, or unexpected cash flow challenges.
Modern business finance has moved beyond compliance. It now plays a central role in helping businesses make informed decisions, improve profitability, manage risks, and plan for sustainable growth. Rather than looking only at what happened last month, business owners are increasingly using financial information to understand what is happening today and what is likely to happen next.
Imagine running an online retail business during a busy sales season. Revenue appears strong, orders are increasing, and the business feels successful. However, advertising costs are rising faster than sales, shipping expenses have increased, and several high-value customers are delaying payments. If these issues are only identified after month-end, valuable time has already been lost.
Now imagine receiving a dashboard that highlights these trends as they develop. Instead of reacting after profits decline, you can adjust pricing, review marketing campaigns, negotiate supplier costs, or improve collection procedures before small problems become major financial challenges.
That is the direction business finance is taking.
The future is not about producing more reports. It is about producing better insights that allow business owners to act with confidence.
Business Finance Is No Longer Just About the Numbers
Successful businesses rarely fail because they lack financial reports.
More often, they struggle because they lack timely financial insight.
A Profit and Loss Statement may show that revenue increased during the year, but it doesn’t always explain why profitability declined. A Balance Sheet can show available cash, but it doesn’t reveal whether future obligations will create pressure over the coming months.
This is why business finance has become increasingly strategic.
Business owners now expect finance professionals to answer questions such as:
Which products generate the strongest margins?
Are operating expenses increasing too quickly?
Which customers contribute the highest long-term value?
Will current cash reserves support future expansion?
Where can unnecessary costs be reduced without affecting quality?
Answering these questions requires more than accurate bookkeeping.
It requires analysing trends, understanding operational performance, and translating financial information into practical business recommendations.
Finance professionals are no longer simply preparing reports. They are helping businesses interpret those reports and use them to make better decisions.
Veritas Expert Insight
One of the most common challenges we see is businesses reviewing financial statements only after month-end. Companies that monitor cash flow, profitability, and key performance indicators throughout the month often identify issues earlier and make more confident business decisions.
Smarter Decisions Begin with Better Financial Insights
Many business decisions are still based on experience and intuition.
While experience remains valuable, combining it with accurate financial information leads to better outcomes.
Consider a professional services firm deciding whether to hire additional staff.
Revenue may be increasing, but is the business generating enough consistent cash flow to support higher salaries? Will current projects continue long enough to justify the additional cost? How will the new hire affect profitability over the next twelve months?
Without reliable financial analysis, these decisions become educated guesses.
Modern business finance provides the information needed to evaluate different scenarios before committing valuable resources.
Forecasting tools can estimate future cash flow, profitability reports can identify high-performing service lines, and budgeting models can measure the financial impact of expansion plans.
Instead of relying on assumptions, management gains confidence because decisions are supported by accurate financial data.
The goal is not simply to understand where the business stands today. The goal is to understand where it is heading.
Technology Is Changing How Businesses Manage Finance
Technology has transformed almost every part of running a business, and finance is no exception.
Cloud accounting platforms, artificial intelligence, automation, and integrated financial systems are changing how businesses collect, process, and analyse financial information.
Artificial intelligence, for example, can identify unusual spending patterns, detect potential cash flow issues, analyse customer payment behaviour, and highlight declining profit margins long before those trends become obvious through traditional reporting.
Instead of searching through multiple spreadsheets, business owners receive meaningful insights presented in a clear and practical way.
This allows finance teams to spend less time gathering information and more time helping management solve problems.
Technology is not replacing financial professionals.
Instead, it is strengthening business finance by improving the quality, speed, and accuracy of financial information available for decision-making.
Businesses that combine modern technology with experienced financial advisors will be far better positioned to adapt, grow, and compete in an increasingly dynamic marketplace.
Automation Creates Time for Strategic Thinking
One of the biggest challenges many finance teams face isn’t a lack of knowledge—it’s a lack of time.
Hours are often spent downloading bank statements, entering supplier invoices, matching customer payments, reconciling accounts, and correcting manual errors. While these activities are essential, they rarely contribute directly to business growth.
Automation is changing that.
Modern accounting software can import bank transactions automatically, capture receipts through mobile apps, generate recurring invoices, match payments, and perform many reconciliations with minimal manual intervention. Instead of repeating the same administrative tasks every month, finance professionals can focus on analysing results and supporting strategic decisions.
Consider a wholesale business processing hundreds of supplier invoices each month. Previously, an employee might spend several days entering invoice details manually before preparing management reports. By introducing automated invoice processing and approval workflows, those same reports can be available much earlier, giving management additional time to review performance and respond to changing business conditions.
This shift is one of the most significant developments in business finance. Automation is not simply about saving time; it is about creating time for higher-value activities such as forecasting, budgeting, profitability analysis, and financial planning.
Businesses that automate routine processes often discover another important benefit—greater consistency. Standardised workflows reduce manual errors, improve internal controls, and provide more reliable financial information for decision-making.
Real-Time Reporting Is Becoming the New Standard
Traditional financial reporting answers one important question:
“What happened?”
Modern businesses need answers to a different question:
“What is happening right now?”
Waiting until the end of the month to understand financial performance is becoming increasingly risky, particularly in industries where conditions change rapidly.
Imagine a restaurant experiencing higher sales during a holiday season. At first glance, revenue looks impressive. However, food costs have increased, labour expenses are exceeding budget, and wastage is reducing profitability.
If management discovers these issues only after month-end, the opportunity to correct them has already passed.
With real-time reporting, business owners can monitor gross profit, operating expenses, cash balances, inventory levels, and outstanding receivables every day. Instead of reacting to historical information, they can respond while there is still time to improve the outcome.
This is where business finance becomes a genuine management tool rather than an administrative requirement.
Real-time dashboards also improve communication across the organisation. Department managers, business owners, and finance teams all work from the same accurate information, making planning meetings more productive and decisions more consistent.
Veritas Expert Insight
Financial reports should never surprise business owners. If a major issue appears in the month-end reports for the first time, it usually means the business wasn’t monitoring the right performance indicators throughout the month.
Virtual CFO Services Are Redefining Financial Leadership
As businesses grow, financial decisions become more complex.
Questions about expansion, financing, pricing, staffing, and investment require more than accurate bookkeeping. They require experienced financial leadership.
Many small and medium-sized businesses cannot justify employing a full-time Chief Financial Officer, yet they still need strategic financial guidance.
This is why Virtual CFO services have become an increasingly valuable part of modern business finance.
A Virtual CFO works alongside business owners to develop budgets, forecast cash flow, monitor key performance indicators, evaluate profitability, and support long-term planning. Instead of reviewing financial statements only after they have been prepared, they help management understand what those reports mean and what actions should follow.
For example, imagine two businesses generating similar annual revenue.
The first reviews financial statements once a quarter.
The second holds monthly strategy meetings with a Virtual CFO, reviews budgets against actual performance, analyses cash flow forecasts, and evaluates business risks regularly.
Although both businesses have access to the same accounting information, the second business is far more likely to make proactive decisions, identify opportunities earlier, and maintain stronger financial stability.
The future of business finance is not simply about having more information. It is about using that information effectively.
Preparing Your Business for the Future
The future of finance is already here, but adopting every new technology immediately is neither practical nor necessary.
Instead, businesses should focus on building a strong financial foundation that supports continuous improvement.
Start by ensuring bookkeeping records are accurate and up to date. Reliable financial information is the foundation of every good decision.
Next, identify repetitive accounting tasks that can be automated. Even small improvements in efficiency can free valuable time for financial analysis and planning.
Review key performance indicators regularly rather than relying solely on annual financial statements. Monitor cash flow, profitability, operating expenses, and customer payment trends throughout the year.
Finally, seek financial advice before making significant business decisions rather than after problems arise.
The businesses that achieve sustainable growth are rarely those with the most complex financial systems.
They are the ones that consistently use financial information to guide everyday decisions.
That is the true purpose of modern business finance.
Final Thoughts
The role of finance is changing faster than ever before.
Technology, automation, artificial intelligence, and cloud-based systems are transforming how businesses collect and analyse financial information. At the same time, business owners increasingly expect finance professionals to provide practical advice that supports growth rather than simply preparing reports for compliance.
The future of business finance belongs to organisations that combine modern technology with experienced financial expertise.
Businesses that invest in better reporting, stronger financial processes, and strategic decision-making will be better positioned to improve profitability, strengthen cash flow, manage risk, and adapt to future challenges.
Finance should never be viewed as a function that simply records the past.
It should become one of the most valuable tools for shaping the future of your business.
Frequently Asked Questions
What is business finance?
Business finance is the process of managing a company’s financial resources, including budgeting, cash flow management, financial reporting, forecasting, investment decisions, and strategic planning to achieve long-term growth.
Why is business finance becoming more important?
Business finance now plays a strategic role by helping owners make informed decisions, improve profitability, manage risks, and prepare for future opportunities rather than simply meeting compliance requirements.
How does automation improve business finance?
Automation reduces manual data entry, speeds up reconciliations, improves reporting accuracy, and allows finance professionals to focus on analysis and strategic planning with Business finance instead of repetitive administrative work.
What are the benefits of a Virtual CFO?
A Virtual CFO provides expert Business finance – financial leadership through budgeting, forecasting, cash flow management, profitability analysis, and strategic guidance without the cost of employing a full-time Chief Financial Officer.
How can businesses prepare for the future of finance?
Businesses should maintain accurate bookkeeping, adopt cloud accounting, automate routine processes, monitor key performance indicators regularly, and use financial insights to support everyday decision-making.
Ready to Transform Your Business Finance?
At Veritas Accounting Services, we help businesses move beyond traditional bookkeeping by providing financial reporting, management insights, budgeting, cash flow forecasting, and Virtual CFO services that support confident decision-making.
Whether you’re a startup, an established SME, or a growing e-commerce business, our experienced team can help you build a stronger financial foundation and prepare for future growth.
Running a successful business requires hundreds of decisions throughout the year. You decide when to hire employees, purchase inventory, increase prices, invest in equipment, launch marketing campaigns, or expand into new markets. Every one of these decisions has a financial impact.
Yet many business owners don’t review their financial performance until it’s time for year-end accounting.
By the time financial statements are prepared, taxes are calculated, and the financial year is closed, the opportunity to correct many problems has already passed. What could have been addressed months earlier often becomes an expensive lesson rather than a simple adjustment.
While year-end accounting is essential for compliance and tax reporting, it should never be the only time you evaluate your business’s financial health. Businesses that consistently grow and remain profitable use financial information throughout the year—not just after it ends.
Monthly bookkeeping, timely management reports, and regular financial reviews provide business owners with the information they need to make confident decisions while there is still time to influence the outcome.
Why Looking at Your Numbers Once a Year Isn’t Enough
Think about driving a car across the country. Would you check your fuel gauge, speed, and engine temperature only after reaching your destination?
Of course not.
Running a business works the same way. Financial reports are your dashboard. They tell you whether your business is moving in the right direction or whether immediate action is required.
Many small business owners view year-end accounting as the primary indicator of business performance. In reality, it is a summary of what has already happened.
It tells you:
How much profit you earned
What taxes you owe
Your assets and liabilities
Your overall financial position
What it doesn’t do is give you enough time to change the outcome.
If your gross profit declined steadily over the past eight months, discovering that fact after the financial year closes doesn’t help recover those lost profits. Likewise, if operating expenses increased every month, waiting until year-end accounting means those costs have already reduced your profitability.
The most successful companies don’t manage their businesses once a year. They review financial information regularly and make adjustments before small issues become major financial challenges.
The Hidden Cost of Waiting Until Year-End
Many business owners assume that if sales are growing, the business must be performing well.
Unfortunately, revenue alone tells only part of the story.
Without regular financial reviews, businesses often overlook problems that quietly reduce profitability month after month.
Cash Flow Problems Develop Gradually
One of the biggest misconceptions in business is that profit equals cash.
A company may report healthy profits while struggling to pay suppliers, payroll, or loan repayments.
Regular financial reviews help identify:
Declining bank balances
Slow customer collections
Increasing operating expenses
Rising supplier payments
Seasonal cash shortages
Waiting for year-end accounting to uncover these issues often leaves business owners reacting instead of planning.
Tax Planning Opportunities Are Missed
Effective tax planning rarely happens after the financial year has ended.
Throughout the year, businesses have opportunities to:
Time major purchases strategically
Maximize available deductions
Plan capital investments
Improve business structures
Forecast tax liabilities
When financial information is reviewed regularly, business owners can make informed decisions that may reduce tax surprises at year-end.
Instead of viewing year-end accounting as a tax-saving exercise, successful businesses use it as the final step in a year of proactive financial management.
Rising Costs Often Go Unnoticed
Many businesses experience gradual increases in expenses.
Utility bills rise.
Subscription costs increase.
Supplier prices change.
Payroll expenses expand.
Marketing campaigns become more expensive.
Because these changes happen gradually, they often escape attention until year-end accounting reveals lower-than-expected profits.
Monthly reporting highlights these trends much earlier, giving management time to renegotiate contracts, improve efficiency, or adjust pricing before margins suffer.
Small Problems Become Expensive Problems
Very few financial problems appear overnight.
Most begin as small warning signs.
An increase in overdue customer invoices.
Inventory that isn’t moving.
Declining gross margins.
Higher refund rates.
Lower sales conversion.
These issues are far easier to correct when identified after one month rather than after twelve.
Businesses that review financial performance every month gain the ability to solve problems while they are still manageable instead of discovering them during year-end accounting when the financial year is already over. Why Successful Businesses Review Their Finances Every Month
Businesses that achieve sustainable growth don’t rely solely on year-end accounting. They treat financial reporting as an ongoing management tool rather than a once-a-year compliance exercise.
Monthly financial reviews provide timely information that helps business owners respond quickly to changing market conditions, control costs, and identify new opportunities.
Instead of asking, “How did we perform last year?” successful business owners ask, “What can we improve this month?”
That shift in mindset makes a significant difference.
Revenue Trends Become Clear
Sales figures alone rarely tell the whole story.
A monthly review helps answer important questions such as:
Which products or services generate the highest profit?
Which customers contribute the most revenue?
Are sales increasing or becoming seasonal?
Is growth slowing in a particular market?
Understanding these trends allows businesses to adjust pricing, marketing, and sales strategies before revenue begins to decline.
Rather than waiting for year-end accounting to reveal annual sales performance, monthly reporting provides continuous insight that supports faster and more informed decision-making.
Profitability Can Be Improved Throughout the Year
Revenue growth does not always translate into higher profits.
Businesses often experience:
Rising supplier costs
Higher freight charges
Increased labour expenses
Discounts that reduce margins
Inefficient production processes
Monthly Profit and Loss reports help identify these issues before they significantly affect the bottom line.
If gross margins begin to fall, management can investigate the cause immediately instead of discovering the problem during year-end accounting, when the opportunity to recover lost profit has already passed.
Cash Flow Becomes Predictable
Cash flow is often the biggest challenge for growing businesses.
Even profitable companies can struggle if customer payments are delayed or operating expenses increase unexpectedly.
Monthly cash flow monitoring helps businesses:
Forecast future cash requirements
Plan major purchases
Avoid unnecessary borrowing
Schedule supplier payments efficiently
Maintain sufficient working capital
This proactive approach reduces financial stress and gives business owners greater confidence when making investment decisions.
Customer Receivables Stay Under Control
Outstanding invoices directly affect cash flow.
When receivables are reviewed every month, businesses can quickly identify:
Overdue customer accounts
Collection issues
Credit risks
Payment trends
Following up on overdue invoices promptly improves cash flow and reduces the likelihood of bad debts.
Waiting until year-end accounting to review receivables often means that unpaid invoices have become much harder—or even impossible—to collect.
Inventory Is Managed More Efficiently
For product-based businesses, inventory represents a significant investment.
Without regular monitoring, businesses may experience:
Instead of tying up valuable capital in excess inventory, businesses can invest those funds in growth opportunities.
Financial Reports That Drive Better Decisions
Many business owners think financial reports exist only for accountants or tax authorities.
In reality, they are powerful management tools that support smarter business decisions every month.
Some of the most valuable reports include:
Profit and Loss Statement
Shows whether the business is generating sustainable profits and identifies areas where expenses are increasing.
Balance Sheet
Provides a clear picture of assets, liabilities, and business equity, helping owners understand the company’s overall financial strength.
Cash Flow Report
Tracks how money moves through the business and helps identify potential liquidity issues before they become serious.
Accounts Receivable Aging Report
Highlights overdue customer balances and improves collection efforts.
Accounts Payable Aging Report
Helps manage supplier payments, maintain healthy vendor relationships, and improve working capital.
Budget vs. Actual Report
Compares planned financial performance with actual results, allowing management to identify variances and take corrective action promptly.
Reviewing these reports regularly transforms financial data into practical business intelligence instead of historical information.
Build a Habit of Financial Review
Strong businesses are built on consistent financial discipline rather than annual surprises.
A simple monthly review meeting can include:
Reviewing financial statements
Comparing current performance with previous months
Monitoring key performance indicators (KPIs)
Evaluating cash flow forecasts
Reviewing outstanding customer balances
Monitoring inventory performance
Identifying opportunities to reduce unnecessary costs
Planning future investments
This routine doesn’t require hours of analysis.
With accurate bookkeeping and timely reporting, most businesses can complete a meaningful financial review in less than an hour each month.
Working with experienced bookkeeping professionals or a Virtual CFO ensures that financial information is accurate, relevant, and focused on helping management make better decisions—not just preparing reports for compliance. Conclusion
Many businesses still view year-end accounting as the primary measure of financial success. While it plays a vital role in meeting tax and compliance obligations, it should never be the only time you evaluate your business performance.
The businesses that grow consistently don’t wait until the end of the financial year to understand their numbers. They review their financial position regularly, identify challenges early, and make informed decisions before those challenges become costly problems.
Whether it’s improving cash flow, increasing profitability, controlling expenses, or planning future investments, timely financial information gives business owners the confidence to act when it matters most.
Instead of relying solely on year-end accounting, build a habit of reviewing your financial reports every month. You’ll gain greater visibility into your business, make smarter decisions, and create a stronger foundation for long-term success.
Think of year-end accounting as the finish line for reporting—not the starting point for managing your business.
Frequently Asked Questions
What is year-end accounting?
Year-end accounting is the process of finalizing a company’s financial records at the end of the financial year. It includes preparing financial statements, reconciling accounts, calculating taxes, and ensuring compliance with applicable accounting and tax regulations. While year-end accounting is essential, businesses should also review their finances throughout the year to make timely decisions.
Why is monthly financial reporting better than relying only on year-end accounting?
Monthly reporting helps identify cash flow issues, declining profits, rising expenses, and operational inefficiencies while there is still time to take corrective action. Waiting until year-end accounting often means discovering problems after the opportunity to fix them has passed.
Which financial reports should business owners review every month?
Business owners should regularly review:
Profit & Loss Statement
Balance Sheet
Cash Flow Statement
Accounts Receivable Aging Report
Accounts Payable Aging Report
Budget vs. Actual Report
Key Performance Indicators (KPIs)
These reports provide valuable insights for better decision-making.
Can regular bookkeeping improve business profitability?
Yes. Accurate and timely bookkeeping helps businesses monitor expenses, improve cash flow, manage receivables, identify unnecessary costs, and make informed financial decisions that support long-term profitability.
How can a Virtual CFO help my business?
A Virtual CFO provides strategic financial guidance beyond traditional bookkeeping. Services typically include budgeting, cash flow forecasting, financial analysis, KPI reporting, business planning, and ongoing advice that helps business owners make confident decisions throughout the year—not just during year-end accounting.
Call to Action
Don’t Wait Until Year-End to Understand Your Business
At Veritas Accounting Services, we believe great financial decisions happen every month—not just at the end of the financial year.
Our experienced team provides:
Monthly Bookkeeping
Management Reporting
Cash Flow Analysis
Budgeting & Forecasting
Virtual CFO Services
Financial Performance Reviews
Whether you’re a startup, growing business, or established company, we’ll help you turn financial data into practical business insights that support smarter decisions and sustainable growth.
Many business owners believe having plenty of inventory is a sign of preparedness. Shelves full of products create a sense of security, ensuring customer orders can always be fulfilled.
However, what looks like a valuable business asset can quietly become one of your largest financial burdens.
Excess inventory doesn’t just occupy warehouse space—it locks up working capital, increases inventory costs, reduces profitability, and limits your ability to invest in business growth.
The most successful businesses don’t simply buy more inventory. They manage inventory strategically to maximize cash flow, reduce waste, and improve financial performance.
Inventory Isn’t Just Stock—It’s Money Sitting on the Shelf
Every item stored in your warehouse represents money that is no longer available for other business needs.
Until inventory is sold, your investment remains tied up.
That means less cash available for:
Marketing campaigns
Hiring skilled employees
Expanding operations
Purchasing faster-moving products
Investing in new technology
Many businesses focus only on purchasing costs while overlooking the long-term inventory costs associated with holding products for months—or even years.
Inventory should generate profits, not consume cash.
Why Excess Inventory Hurts Your Business
Holding extra stock may seem harmless, but it creates financial pressure in several ways.
Cash Flow Gets Trapped
Cash invested in slow-moving products cannot be used elsewhere.
Healthy businesses rely on strong cash flow to pay suppliers, employees, taxes, and operating expenses. Excess inventory reduces financial flexibility and often forces businesses to borrow money unnecessarily.
Storage Expenses Continue to Grow
Every additional pallet or shelf requires:
Warehouse space
Rent
Utilities
Insurance
Security
Inventory handling
These ongoing inventory costs continue whether products sell or not.
Products Lose Value
Inventory rarely becomes more valuable over time.
Businesses frequently experience:
Obsolete products
Expired inventory
Seasonal items losing demand
Packaging changes
New product launches replacing old models
When products become outdated, businesses often sell them at heavy discounts—or write them off completely.
Higher Risk of Damage and Theft
The longer products remain in storage, the greater the likelihood of:
Damage
Theft
Misplacement
Shrinkage
Quality deterioration
These losses directly reduce profits while increasing overall inventory costs.
The Hidden Costs Most Businesses Ignore
Many business owners calculate only the purchase price of inventory.
The true carrying cost is much higher.
Hidden expenses often include:
Hidden Cost
Business Impact
Storage
Higher warehouse expenses
Insurance
Increased operating costs
Financing
Interest on borrowed funds
Obsolescence
Inventory write-offs
Damage & Theft
Lost profit
Handling
Additional labour costs
Technology
Inventory software and tracking
Opportunity Cost
Missed investment opportunities
When combined, these costs can consume 20%–30% of inventory value annually, making effective inventory management essential for protecting profitability.
Warning Signs Your Inventory Is Too High
Your business may be carrying excessive inventory if you notice any of these warning signs:
Products haven’t sold for several months.
Warehouse shelves remain full year-round.
Cash flow is consistently tight despite healthy sales.
Frequent discounting is required to clear stock.
Inventory write-offs are increasing.
New inventory arrives before existing stock is sold.
Inventory value continues growing faster than revenue.
If several of these indicators apply to your business, it’s time to review your purchasing strategy and overall inventory costs.
How Better Inventory Management Improves Profitability
Reducing inventory doesn’t mean risking stock shortages.
It means maintaining the right inventory at the right time.
Consider these practical strategies:
Forecast Demand More Accurately
Use historical sales trends, seasonality, and customer demand to purchase smarter instead of simply buying more.
Track Inventory Turnover
Monitor how quickly products sell.
Slow-moving items should be reviewed regularly and removed before they become obsolete.
Establish reorder points based on actual demand rather than assumptions.
This reduces unnecessary purchasing while maintaining customer service levels.
Use Technology to Improve Accuracy
Modern inventory management systems provide real-time visibility into:
Stock levels
Sales trends
Purchase orders
Supplier lead times
Accurate information helps reduce inventory costs and improve operational efficiency.
Work With Financial Advisors
Inventory decisions should never be based solely on warehouse capacity.
Regular financial analysis helps determine:
Inventory turnover ratios
Gross margin by product
Cash conversion cycle
Working capital requirements
Combining operational data with financial reporting leads to stronger business decisions.
Final Thoughts
Inventory should support business growth—not quietly reduce profitability.
Businesses that actively monitor inventory costs gain stronger cash flow, lower operating expenses, and healthier profit margins. Every product sitting too long on a shelf represents capital that could be working harder elsewhere.
By reviewing purchasing decisions, monitoring inventory turnover, and using accurate financial reporting, you can transform inventory from a hidden expense into a strategic advantage.
The goal isn’t simply to reduce inventory—it’s to ensure every dollar invested in stock contributes to sustainable business growth.
Frequently Asked Questions
What are inventory costs?
Inventory costs include purchasing, storage, insurance, handling, financing, and losses from damage or obsolete stock.
Why is too much inventory bad for cash flow?
Excess inventory ties up working capital, reducing the cash available for payroll, marketing, supplier payments, and business expansion.
How often should businesses review inventory?
Most businesses should review inventory reports at least monthly to identify slow-moving or obsolete stock before it affects profitability.
What is inventory turnover?
Inventory turnover measures how quickly inventory is sold and replaced over a period. Higher turnover generally indicates more efficient inventory management.
How can businesses reduce inventory costs?
Businesses can reduce inventory costs by improving demand forecasting, setting reorder levels, monitoring inventory turnover, reviewing reports regularly, and using inventory management software.
Call to Action
Is your inventory helping your business—or quietly reducing your profits?
At Veritas Accounting Services, we help businesses analyze inventory performance, improve cash flow, optimize working capital, and make informed financial decisions through accurate bookkeeping and management reporting.
Contact us today to discover how better financial insights can strengthen your business.
Whether you’re hiring a new employee, investing in marketing, purchasing equipment, expanding into a new market, or launching a new product, every decision influences your company’s financial future. While experience and intuition certainly play a role, relying solely on instinct can expose your business to unnecessary risks.
Surprisingly, many businesses still operate this way.
Business owners often believe they know how their company is performing because sales appear healthy, customers seem satisfied, or bank balances look positive. However, these observations rarely reveal the complete picture. Without reliable data, it’s impossible to know whether profits are improving, operating costs are increasing, or cash flow is becoming a concern.
This is where business performance metrics become invaluable.
They transform assumptions into facts, helping business owners understand what is really happening inside the business. Instead of reacting to problems after they occur, you can identify trends early, make informed decisions, and build a stronger, more profitable organisation.
Think of your business like an aircraft. A skilled pilot doesn’t rely on instinct alone—they depend on instruments that provide accurate information about speed, altitude, direction, and fuel levels. Likewise, business owners need reliable business performance metrics to navigate challenges and achieve sustainable growth.
Why Every Business Needs Measurable Data
Every day, business owners make decisions that affect profitability, operations, employees, and customers. Some decisions are small, while others can influence the future of the company for years to come.
The challenge is that many of these decisions are based on opinions rather than evidence.
Questions like these should always have clear, measurable answers:
Is our profit improving every month?
Which products generate the highest margin?
Are operating expenses increasing faster than revenue?
Which customers contribute the most profit?
How much cash do we actually have available?
Without business performance metrics, these questions often receive responses such as “I think so” or “It feels like it.”
Successful organisations don’t manage their business based on feelings. They establish measurable indicators that reveal exactly where the business stands and where improvement is needed.
Numbers eliminate uncertainty and allow management teams to focus on solving real problems instead of reacting to assumptions.
Revenue Alone Doesn’t Define Success
One of the most common mistakes business owners make is using revenue as the primary measure of success.
While growing sales is important, revenue alone doesn’t guarantee a healthy business.
Imagine two companies generating the same annual sales. One maintains healthy profit margins, strong cash flow, and controlled expenses. The other struggles with rising costs, excessive discounts, and delayed customer payments.
Although their revenue is identical, their financial health is completely different.
This is why businesses should monitor revenue alongside other business performance metrics that provide greater insight into financial performance.
Some valuable revenue indicators include:
Monthly revenue growth
Revenue by product or service
Revenue by customer
Average sales value
Revenue by business location
These figures help identify where growth is occurring and whether that growth is sustainable.
Instead of celebrating sales alone, businesses should evaluate whether additional revenue is creating additional value.
Profitability Tells the Real Story
Revenue creates activity.
Profit creates sustainability.
Many businesses proudly announce record sales while quietly experiencing declining profitability. Rising supplier costs, increased labour expenses, excessive overheads, or poor pricing decisions can gradually reduce profit without immediately affecting sales.
Monitoring profitability allows business owners to understand whether the company is becoming stronger or simply becoming busier.
Important profitability indicators include:
Gross Profit Margin
Net Profit Margin
Operating Margin
Cost of Goods Sold
Operating Expenses as a percentage of revenue
These business performance metrics help identify pricing opportunities, unnecessary expenses, and operational inefficiencies before they become significant financial problems.
Businesses that regularly analyse profitability are better positioned to improve margins, invest confidently, and remain competitive even during challenging economic conditions.
Cash Flow Deserves Daily Attention
Profit may appear on financial statements, but cash keeps a business operating.
Many profitable businesses experience financial stress because they cannot convert profits into available cash quickly enough. Customer payment delays, inventory purchases, loan repayments, and tax obligations can all place pressure on working capital.
For this reason, every business owner should monitor cash flow consistently rather than waiting until the end of the month.
Key cash flow indicators include:
Operating Cash Flow
Available Cash Balance
Accounts Receivable Days
Accounts Payable Days
Cash Conversion Cycle
These business performance metrics provide early warning signs of liquidity issues, allowing management to take corrective action before cash shortages disrupt operations.
Healthy cash flow provides flexibility, supports future investment, and enables businesses to respond confidently to unexpected challenges. Customer Profitability Matters More Than Customer Volume
Many businesses focus heavily on acquiring new customers, believing that a growing customer base automatically leads to higher profits. While customer growth is important, not every customer contributes equally to the success of your business.
Some customers place frequent orders, pay on time, and require minimal support. Others negotiate lower prices, demand additional resources, make repeated service requests, or delay payments. Although both customers generate revenue, their profitability can be dramatically different.
This is why customer-focused business performance metrics deserve regular attention.
Consider tracking:
Customer Lifetime Value (CLV)
Customer Acquisition Cost (CAC)
Average Revenue per Customer
Gross Profit by Customer
Customer Retention Rate
Average Collection Period
Understanding these metrics helps businesses identify their most valuable customers, improve pricing strategies, and allocate marketing budgets more effectively.
Instead of asking, “How many customers do we have?” ask, “Which customers contribute the most value to our business?”
That single shift in thinking often leads to smarter decisions and stronger profitability.
Operational Efficiency Drives Sustainable Growth
Growth isn’t always about selling more. Often, it’s about doing more with the resources you already have.
Operational efficiency measures how effectively your business converts time, labour, and resources into profitable outcomes. Inefficient processes increase costs, delay customer service, and reduce overall productivity.
Imagine two businesses with identical revenue. One completes projects faster, manages staff efficiently, and minimises waste. The other experiences delays, duplicate work, and constant rework.
Although their revenue is similar, their profits won’t be.
Useful business performance metrics for measuring operational efficiency include:
Revenue per Employee
Employee Utilisation Rate
Project Completion Time
Order Fulfilment Time
Cost per Transaction
Labour Cost Percentage
Monitoring these indicators allows business owners to identify bottlenecks, improve workflows, and maximise the return on every resource invested.
Operational excellence rarely happens by accident. It is achieved by consistently measuring performance and making continuous improvements.
Inventory Can Become an Expensive Liability
For businesses that buy, manufacture, or sell products, inventory represents a significant investment. While maintaining sufficient stock is necessary to meet customer demand, excessive inventory can quietly reduce profitability.
Every product sitting on a shelf ties up cash that could otherwise be invested in marketing, technology, expansion, or business development.
Poor inventory management can also lead to:
Higher storage costs
Product obsolescence
Damaged goods
Slow-moving stock
Cash flow constraints
Important business performance metrics for inventory management include:
Inventory Turnover Ratio
Days Inventory Outstanding
Slow-Moving Inventory Value
Dead Stock Percentage
Stock-Out Frequency
Regular monitoring helps businesses maintain the right balance between customer service and efficient use of working capital.
Inventory should support growth—not become a financial burden.
Forecasting Helps You Stay Ahead
Looking at historical reports tells you where your business has been.
Forecasting helps you understand where it is heading.
One of the biggest advantages of reviewing business performance metrics regularly is the ability to predict future outcomes before problems arise.
For example, if operating expenses are increasing faster than revenue, management can take corrective action before profitability declines. If customer payment cycles are lengthening, steps can be taken to improve collections before cash flow becomes critical.
Every growing business should prepare forecasts for:
Revenue
Operating Expenses
Cash Flow
Staffing Requirements
Capital Expenditure
Seasonal Sales Trends
Forecasting is not about predicting the future with perfect accuracy. It is about preparing for different scenarios so that better decisions can be made today.
Businesses that forecast consistently are generally more resilient, more profitable, and better prepared for economic uncertainty.
Create a Dashboard That Supports Better Decisions
Business owners don’t need dozens of reports every week.
They need one dashboard that highlights the numbers that matter most.
An effective management dashboard provides an instant overview of financial performance, operational efficiency, and business health. Rather than searching through spreadsheets, decision-makers can quickly identify trends and respond accordingly.
A practical dashboard might include:
Monthly Revenue
Gross Profit Margin
Net Profit Margin
Operating Cash Flow
Accounts Receivable
Accounts Payable
Customer Retention Rate
Inventory Turnover
Budget vs Actual Performance
Monthly Operating Expenses
When reviewed consistently, these business performance metrics become an early warning system for the business.
Instead of reacting to problems after they occur, leaders can identify opportunities, manage risks, and make confident decisions backed by reliable information.
Conclusion
Every successful business relies on information to make informed decisions. Experience, intuition, and industry knowledge remain valuable, but they are most effective when supported by accurate data.
Without meaningful measurements, business owners risk making important decisions based on assumptions rather than facts. Over time, this can affect profitability, cash flow, customer relationships, and long-term growth.
Business performance metrics provide the visibility needed to understand what is working, what needs attention, and where opportunities exist. They replace uncertainty with confidence and transform financial reports into practical management tools.
Whether you’re running a startup, a growing business, or an established company, measuring the right indicators will help you make smarter decisions, improve operational efficiency, and build a stronger business for the future.
Remember, businesses don’t improve simply because owners work harder. They improve because owners measure what matters.
Frequently Asked Questions
What are business performance metrics?
Business performance metrics are measurable indicators that evaluate the financial and operational health of a business. They help business owners monitor profitability, cash flow, efficiency, customer performance, and overall business growth.
Why are business performance metrics important?
Business performance metrics provide reliable information that supports informed decision-making. They help identify trends, improve profitability, manage risks, and ensure the business remains financially healthy.
Which business performance metrics should every business monitor?
Most businesses should regularly track revenue growth, gross profit margin, net profit margin, operating cash flow, accounts receivable, customer profitability, operating expenses, and inventory turnover.
How often should business performance metrics be reviewed?
Critical indicators such as cash flow should be reviewed weekly, while financial and operational metrics are typically reviewed monthly. Businesses preparing for rapid growth may monitor certain KPIs even more frequently.
Call to Action
Are you managing your business with facts—or relying on assumptions?
At Veritas Accounting Services, we help businesses transform financial data into meaningful insights through bookkeeping, management reporting, KPI dashboards, budgeting, forecasting, and Virtual CFO services. By tracking the right business performance metrics, you gain the clarity needed to improve profitability, strengthen cash flow, and make confident business decisions.
Contact us today to discover how better financial reporting can help your business grow with confidence.